


EN
What Hasbro (HAS)'s My Little Pony Deal Means For Shareholders
- Hasbro has agreed a multi-year global licensing deal with 6KU for My Little Pony ride-on products and announced past leadership changes and new digital content such as Play-Doh with Margo, reflecting active use of its brands across toys, media and games.
- The 6KU partnership extends Hasbro’s My Little Pony franchise into wheeled ride-on products and offline retail, adding another route to monetize its intellectual property beyond traditional toys and card games.
- We will now look at how Hasbro's investment narrative could be influenced by the expanded My Little Pony licensing reach.
Scan how Hasbro is using licensing and digital content, then compare that playbook with a curated 19 high quality undiscovered gems that may be building brand strength away from the spotlight.
Hasbro Investment Narrative Recap
To own Hasbro, you need to believe that the pivot toward higher margin Wizards of the Coast and digital gaming can steadily offset a tougher traditional toy cycle. The immediate swing factor is execution in those gaming and licensing franchises, while keeping tariff and input cost volatility from eroding profitability. The recent licensing and content news supports the multi channel IP story, but does not change the near term profit drivers in a major way.
The biggest risk still sits in concentration on Magic: The Gathering and a soft Consumer Products backdrop, where retailer caution and shifting orders can disrupt earnings. High debt and recent insider selling add another layer of sensitivity if cash generation ever slows. The latest updates around digital content and licensing modestly help the thesis on IP monetization, but operational delivery in core franchises remains the key test.
The appointment of Dan Ayoub as President of Wizards of the Coast & Hasbro Digital Games is the announcement to watch. He now oversees Magic: The Gathering, Dungeons & Dragons and broader digital titles at a time when cross platform gaming and licensing are central to Hasbro’s growth ambitions and margin profile.
Ayoub’s track record inside Wizards and long experience in video games reduce some execution risk around large digital projects, which have meaningful development costs and timing uncertainty. If Wizards continues to extend into digital formats and partnerships under stable leadership, that can support the existing catalysts around recurring, higher margin earnings, while still leaving franchise fatigue and concentration as issues investors need to price in.
How Hasbro’s Licensing Story Lines Up With The Numbers
Hasbro's narrative projects US$5.8 billion revenue and US$1.1 billion earnings by 2029. This assumes 3.9% yearly revenue growth and an earnings increase of about US$145 million from current earnings of US$955.4 million.
Uncover why Hasbro's fair value aligns with its current price.
Exploring Other Perspectives
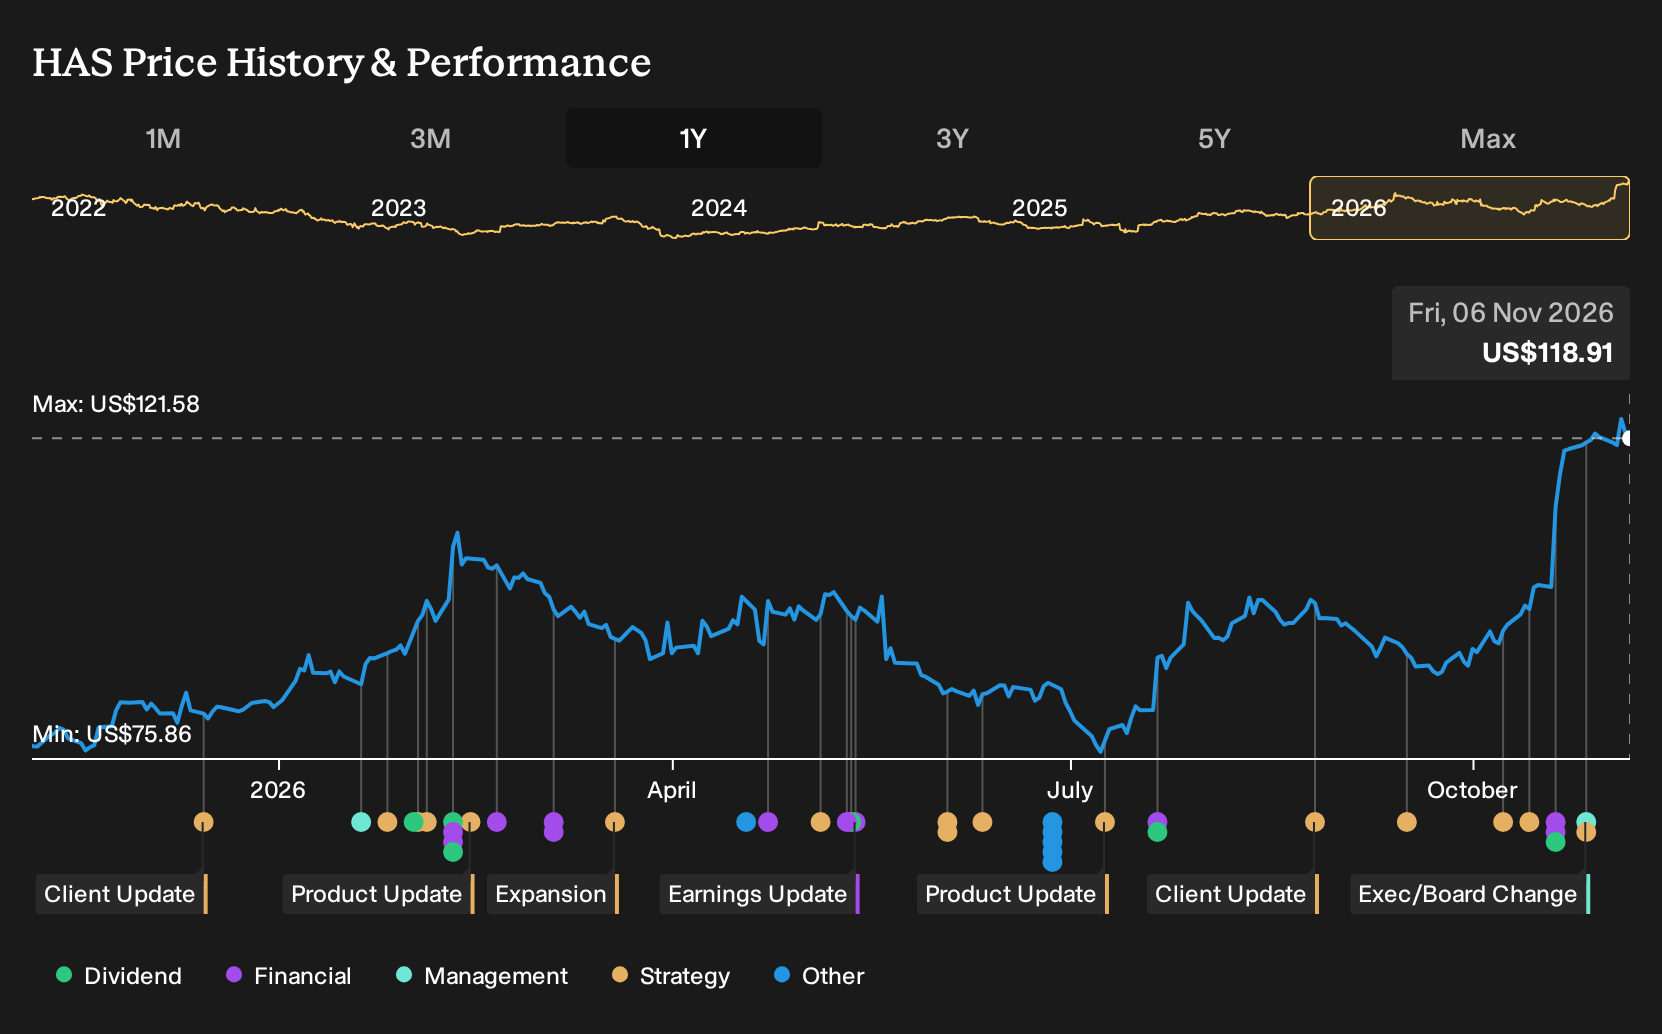
The Simply Wall St Community offers 2 fair value views for Hasbro, spanning roughly US$119 to US$144 per share, which already shows how far opinions can spread. Those figures do not reflect the latest digital content push or the Dan Ayoub promotion, so you are weighing them against fresh franchise risk and new gaming catalysts.
Explore another Hasbro fair value estimate, including one that suggests up to 21% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hasbro research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hasbro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hasbro's overall financial health at a glance.
Looking For More Ideas Beyond Hasbro?
Once you have a view on Hasbro, it can help to benchmark that thinking against other listed businesses with different risk and income profiles. The Simply Wall St Screener is a quick way to scan for companies that line up with your own preferences on quality, value and resilience.
- If you want potential value combined with quality fundamentals, take a look at a 36 high quality undervalued stocks that might warrant a closer review.
- For readers who care most about balance sheet strength and financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If smoother returns and capital protection are your priority, focus on a 31 resilient stocks with low risk scores that could complement a position in Hasbro.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com