


EN
Learn Why The Bull Case For OceanFirst Financial Stock Could Change Following Higher Loan Charge Offs
- OceanFirst Financial reported third quarter 2026 results with net interest income of US$172.12 million, net income of US$16.46 million and a quarterly dividend of US$0.20 per share, while recording US$1.456 million in net loan charge offs.
- The combination of higher net loan charge offs and lower earnings per share from continuing operations, together with a long running dividend stream, places credit costs and capital returns at the center of how OceanFirst Financial’s operating profile is evaluated.
- This article examines how OceanFirst Financial’s investment narrative is affected by softer earnings alongside higher net loan charge offs this quarter.
Compare how OceanFirst Financial’s rising credit costs stack up against peers by scanning our curated 31 resilient stocks with low risk scores that prioritize balance sheet resilience and more consistent earnings profiles.
OceanFirst Financial Investment Narrative Recap
For OceanFirst Financial, the core belief for any shareholder is that the enlarged franchise and C&I focused lending model can support steadier earnings once integration work and credit clean up settle down. The latest quarter does not change that basic thesis, but the combination of softer earnings and higher net loan charge offs keeps execution risk in clear view for the next few quarters.
In the near term, the main catalyst is still progress on cost saves and balance sheet reshaping from the Flushing acquisition, which directly affects pretax, pre provision earnings. Rising charge offs and compressed earnings per share highlight the biggest current risk. If credit costs or margins stay pressured for longer, the timeline for any margin and return improvement could stretch.
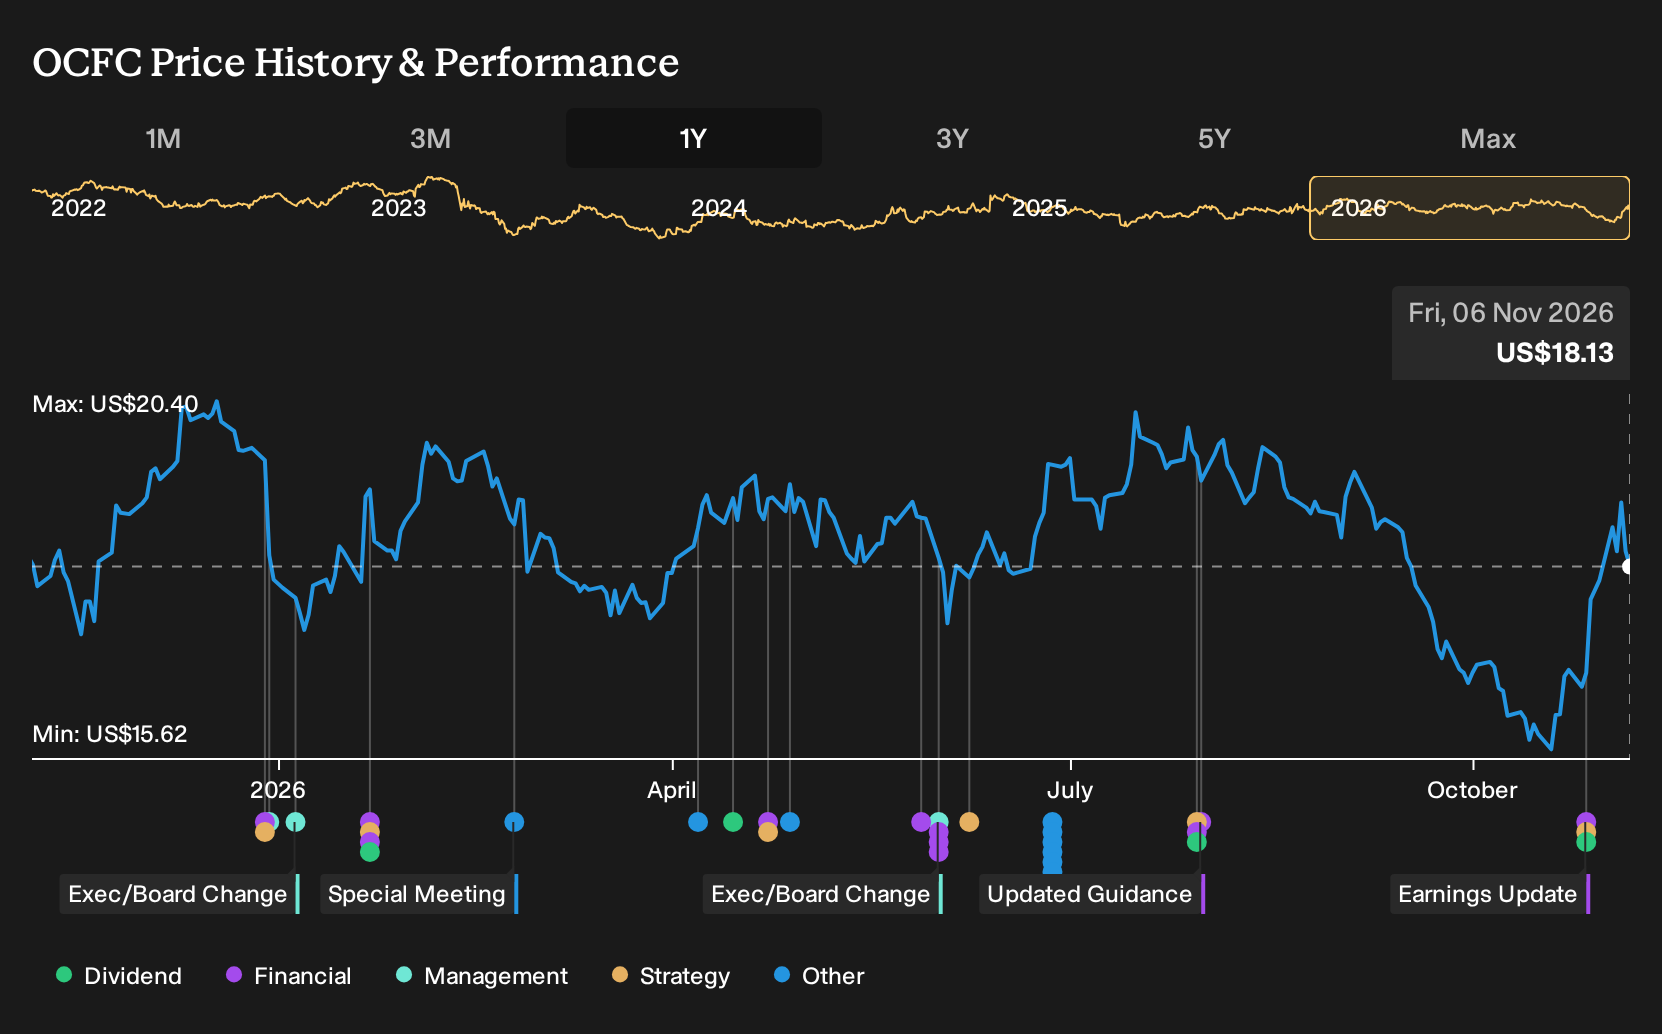
The most relevant recent announcement for that discussion is the third quarter 2026 earnings release. Net interest income of US$172.12 million, coupled with net income of US$16.46 million and basic earnings per share from continuing operations of US$0.17, illustrates how much earnings capacity OceanFirst Financial currently generates against its expanded balance sheet.
Net loan charge offs of US$1.456 million for the quarter, compared with US$617,000 a year ago, feed directly into investor focus on credit quality and capital deployment. When paired with a long dividend record at US$0.20 per share, the earnings and charge off profile helps you evaluate how much room management may have to keep funding growth initiatives while absorbing any further credit or funding pressure.
OceanFirst Financial's analyst narrative points to US$988.3 million of revenue and US$385.5 million of earnings by 2029, built on a forecast 32.2% yearly revenue growth rate and an increase in earnings of about US$337.6 million from current earnings of US$47.9 million.
Uncover why OceanFirst Financial's fair value indicates a 19% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
The Simply Wall St Community contributes three fair value estimates for OceanFirst Financial, clustered between about US$21.29 and US$26.76 per share, which already shows how far opinions can spread with only a handful of views. Those crowd forecasts were made before the latest dividend affirmation, softer earnings and higher charge offs, so use them as a starting point and explore several contrasting viewpoints before deciding how this mix of income stability and rising credit costs fits your own expectations.
Explore 2 other OceanFirst Financial fair value estimates, including one that suggests as much as 48% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OceanFirst Financial research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for OceanFirst Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OceanFirst Financial's overall financial health at a glance.
Looking for more investment ideas beyond OceanFirst Financial?
Once you have a view on OceanFirst Financial, it can help to widen the lens and compare it with other businesses that match the kind of balance sheet strength, income profile, or upside potential you are looking for. The Simply Wall St Screener lets you filter for these traits directly so you spend less time trawling through tickers and more time weighing the trade offs that matter to you.
- If capital preservation is your priority, you can start with companies that pair sturdy finances with relatively low risk profiles by checking the 31 resilient stocks with low risk scores, which is curated with that lens in mind.
- Income focused investors who want payout potential on their radar can scan for higher yield opportunities through the 7 dividend fortresses and then judge whether the cash flows support those distributions.
- For readers looking for opportunities that may be less crowded, you can cast a wider net using the 19 high quality undiscovered gems and compare those businesses with what you see at OceanFirst Financial.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com