


EN
How Investors Are Reacting To DaVita (DVA) Strong Quarterly Earnings
- DaVita reported third quarter 2026 revenue of US$3,578.13 million and net income of US$222.93 million, with both basic and diluted earnings per share from continuing operations above the prior year period.
- Across the first nine months of 2026, DaVita’s higher revenue and net income highlight how operating execution and cost management are influencing earnings per share from continuing operations.
- We will now look at how DaVita’s stronger earnings per share from continuing operations could influence the broader investment narrative.
Scan how DaVita’s earnings story compares with other healthcare operators by reviewing the hand-picked list of solid balance sheet and fundamentals (25 results).
DaVita Investment Narrative Recap
For DaVita, the core belief is that kidney care and U.S. dialysis can still support attractive earnings even when reimbursement and payer mix are tight, provided integrated care and cost control keep doing the heavy lifting. The latest quarter shows earnings per share from continuing operations running ahead of last year, which supports that execution story rather than changing it.
The near term swing factor remains how effectively DaVita manages rising operating expenses, especially technology and G&A, while payer mix headwinds from expiring ACA premium tax credits start to bite. The fresh earnings beat on basic and diluted EPS helps offset these pressures in the short run but does not remove reimbursement and cost inflation as key risks.
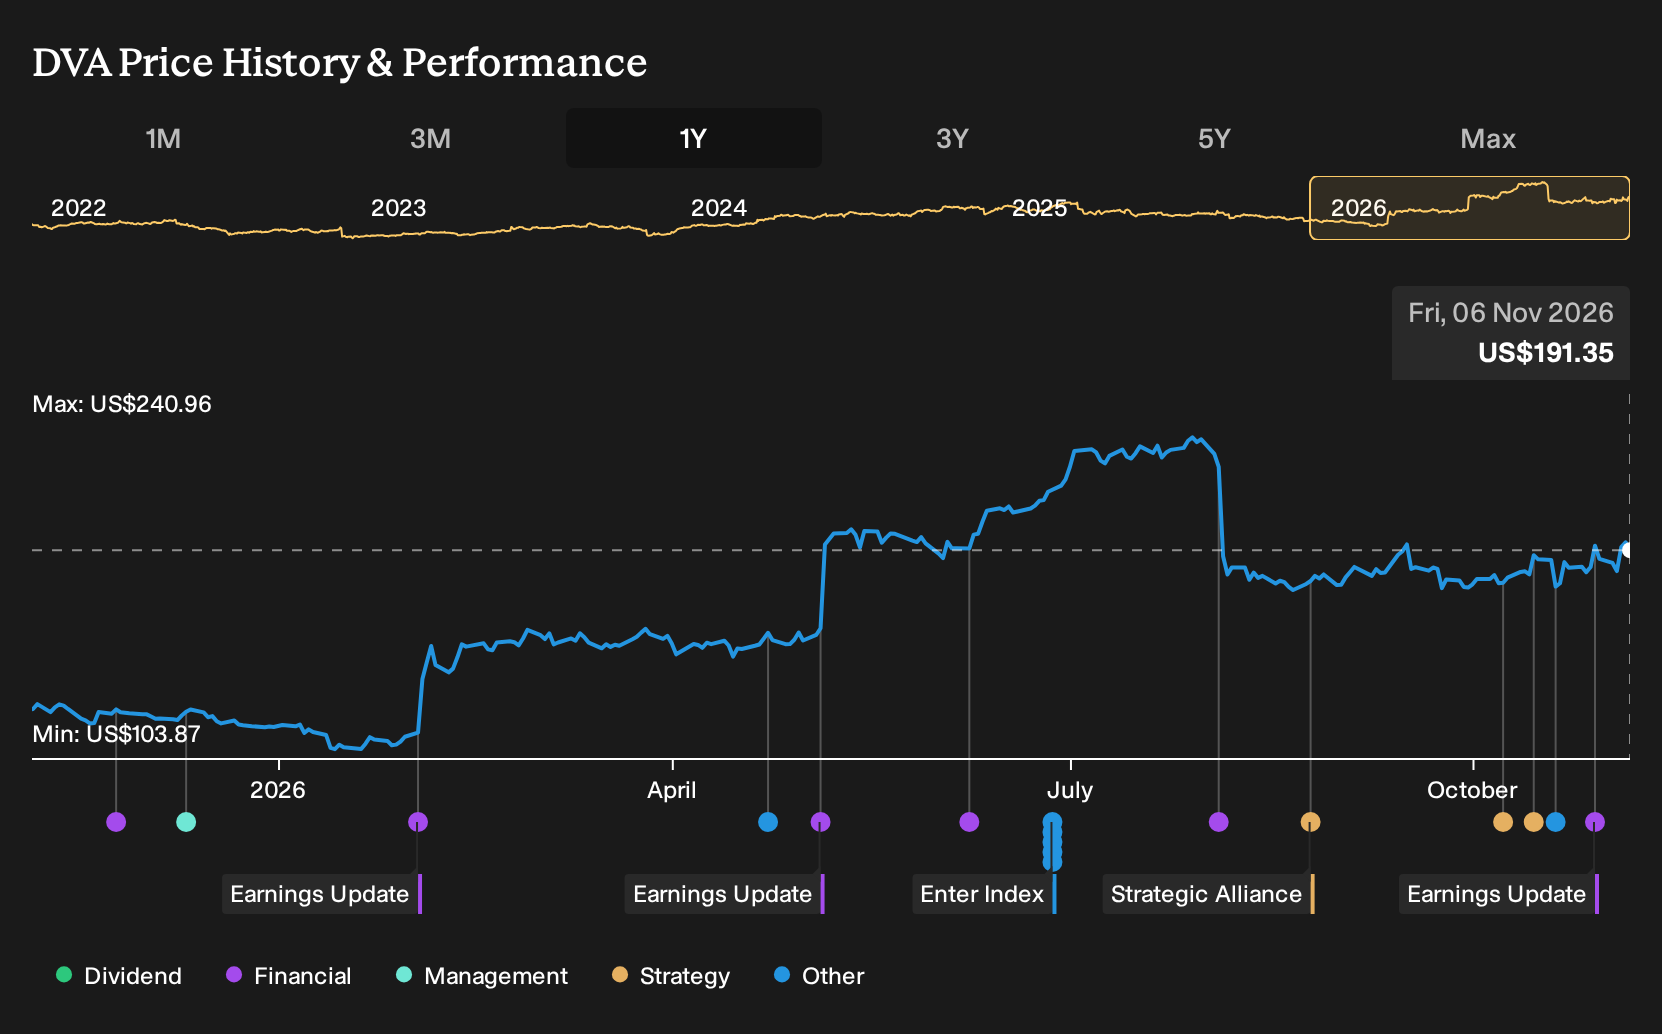
The most relevant update is the third quarter 2026 earnings release itself. It gives a clearer read on how DaVita is absorbing reimbursement pressure and higher operating costs. Revenue of US$3,578.13 million and net income of US$222.93 million, with both basic and diluted EPS above the prior year period, suggest the business model is still supporting higher profitability.
Over the first nine months of 2026, DaVita reported US$10,547.76 million of revenue and US$685.86 million of net income. This ties directly into the key catalysts investors watch. Integrated Kidney Care, new dialyzer technology and treatment volume plans all rely on consistent cash generation, so this earnings trajectory matters for funding technology spend, handling debt and staying flexible around future reimbursement outcomes.
DaVita's current earnings are US$822.5 million and analysts expect earnings to reach US$1.1 billion by 2029, which implies an increase of roughly US$280 million from today. Based on those estimates, the consensus outlook points to forecast revenue of US$16.1 billion in 2029, supported by an assumed 4.6% yearly expansion in revenue.
Uncover how DaVita's fair value indicates a 15% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
One alternate view on DaVita leans hard into cost pressure. The most bearish analysts were penciling in only 2.4% yearly revenue growth to about US$15.0b and a 9.8x P/E by 2029 before this earnings release. That creates a much more cautious story. Use this fresh report to evaluate which narrative you find more convincing.
Explore 3 other DaVita fair value estimates, including one that suggests it could be worth just $219.86.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your DaVita research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DaVita. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DaVita's overall financial health at a glance.
Looking for more DaVita-like investment ideas?
If DaVita has sharpened your view on what you want from a healthcare stock, use that clarity to broaden your watchlist. The Simply Wall St Screener can surface other companies with the balance sheets, cash flows or income profiles that fit the way you already think about risk and reward.
- For investors who want financial resilience front and centre, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching the finances.
- If you prefer to focus on quality at a price that looks interesting, scan the 36 high quality undervalued stocks that combine stronger fundamentals with what may be appealing valuations.
- When income and capital preservation matter most, narrow in on 7 dividend fortresses that pair higher yields with business profiles aimed at consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com