


EN
Do Mixed Earnings Change The Bull Case For Graham Holdings Stock?
- Graham Holdings reported third quarter 2026 revenue of US$1,326.04m and net income of US$75.11m, while nine month net income reached US$385.32m, alongside strong earnings per share from continuing operations on both a basic and diluted basis.
- The firm also added experienced capital allocator Robert J. Mylod, Jr. to its board, introducing deep online travel, software and financial expertise that could shape future decisions on portfolio management and capital deployment.
- The focus will now be on how Graham Holdings' mixed earnings profile and new board appointment could influence its broader investment narrative.
What Is Graham Holdings' Investment Narrative?
To own Graham Holdings, you need to be comfortable with a sprawling collection of education, media, healthcare and industrial operations that rely on disciplined execution rather than a single growth engine. The recent earnings print shows revenue at US$1,326.04m for the quarter and US$3,864.54m for the nine months, with profit margins at 9.6% versus 14.8% a year earlier. That mix of higher net income over nine months and lower margin points to ongoing work on cost control, pricing and business mix as the real near term story.
The appeal many shareholders lean on is a diversified portfolio that some see as attractively priced, given a P/E of 10.3x and internal estimates suggesting meaningful undervaluation. In that context, adding Robert J. Mylod, Jr. to the board looks more like an incremental upgrade to capital allocation depth than a near term catalyst on its own. His background in online travel, software and investing could shape how Graham Holdings thinks about reinvestment, divestitures and buybacks over time, although the key risk for you still comes back to margin pressure across such a capital intensive and varied set of businesses.
That said, when set against the apparent value case and seasoned leadership, there is a quieter operational tension that could still unsettle this story if...
There's only one way to know the right time to buy, sell or hold Graham Holdings. Head to Simply Wall St's company report for the latest analysis of Graham Holdings's Fair Value.
Exploring Other Perspectives
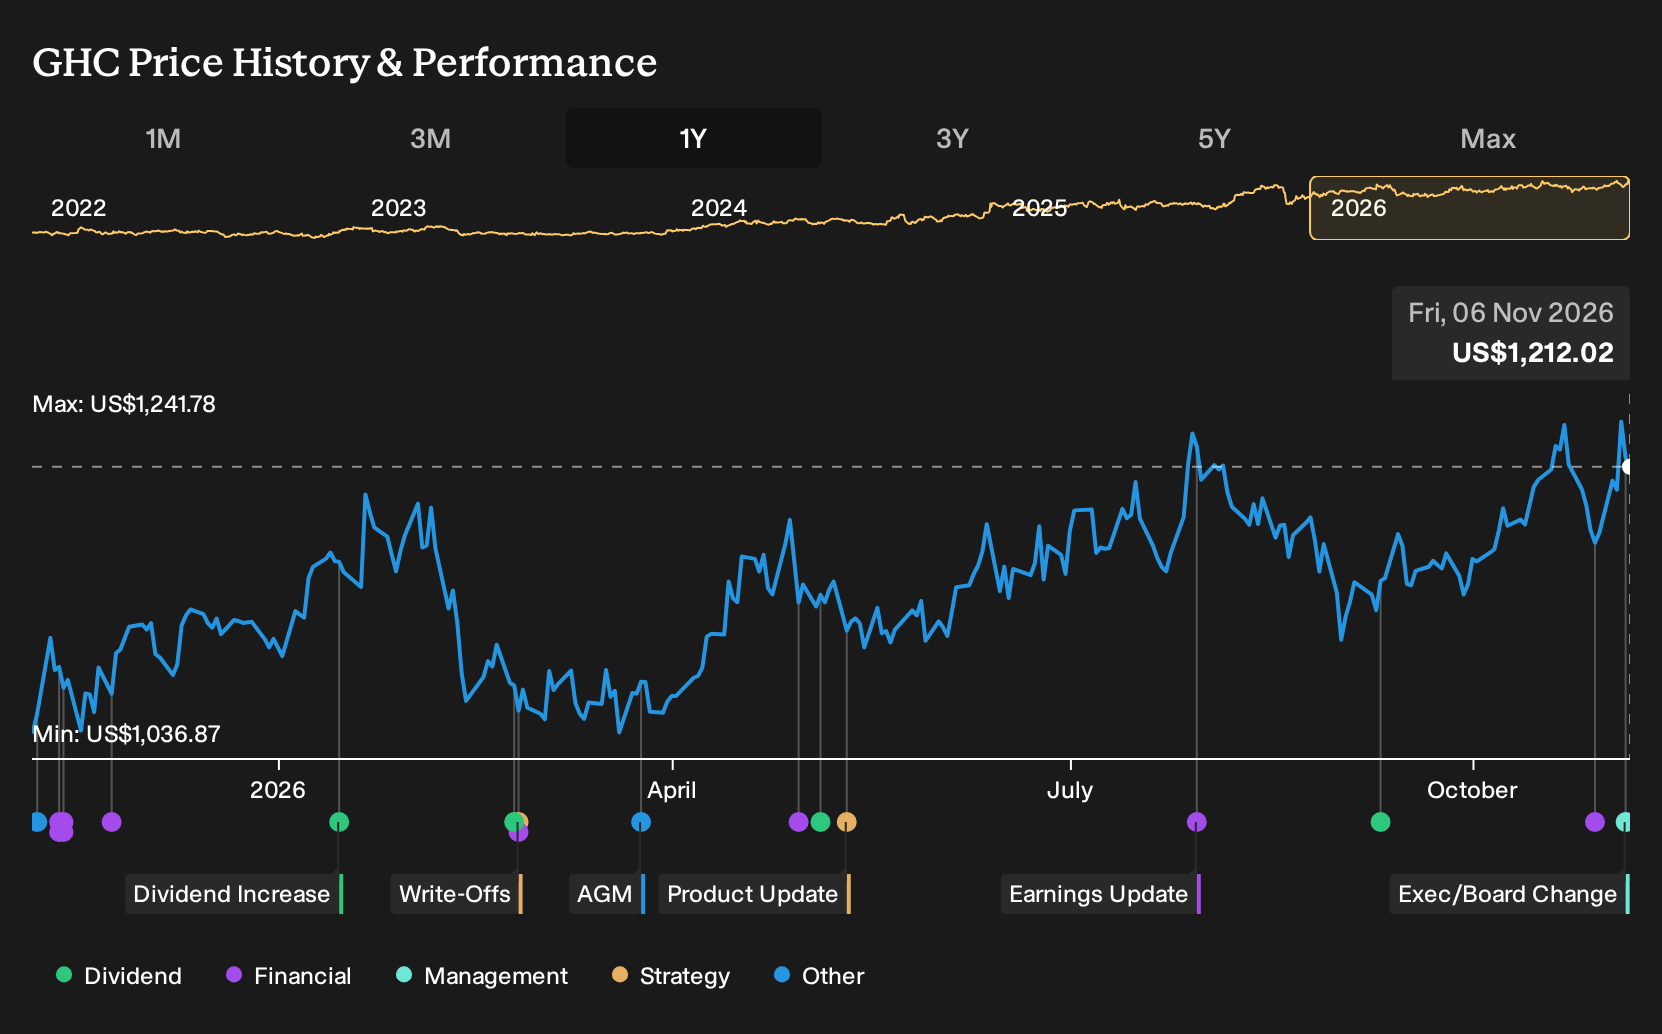
Three fair value estimates from the Simply Wall St Community range from just US$1,100 to over US$2.3m, a spread that shows how far apart private investors can be on Graham Holdings. You now have an earnings print with mixed signals and a new director in Robert Mylod. Both factors could reshape how you frame those community views.
Explore 2 other Graham Holdings fair value estimates, including one that suggests as much as 9% downside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Graham Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Graham Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graham Holdings' overall financial health at a glance.
Looking For More Graham Holdings Style Ideas?
If Graham Holdings has you thinking about complex businesses with layered earnings stories, it can help to widen the lens and see how other companies stack up on value, balance sheet strength or risk levels. The Simply Wall St Screener lets you filter for traits that matter to you so you can build a watchlist that fits your own approach rather than copying anyone else’s.
- If value is your starting point, scan for companies that combine supportive fundamentals with appealing pricing using the 36 high quality undervalued stocks.
- For readers who care most about financial resilience, narrow your focus to businesses with robust balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If you want comfort on risk before anything else, filter for companies with steadier profiles and fewer red flags by running the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com