


EN
What Publicis Groupe (ENXTPA:PUB)'s AI Leadership Reshuffle Means For Shareholders
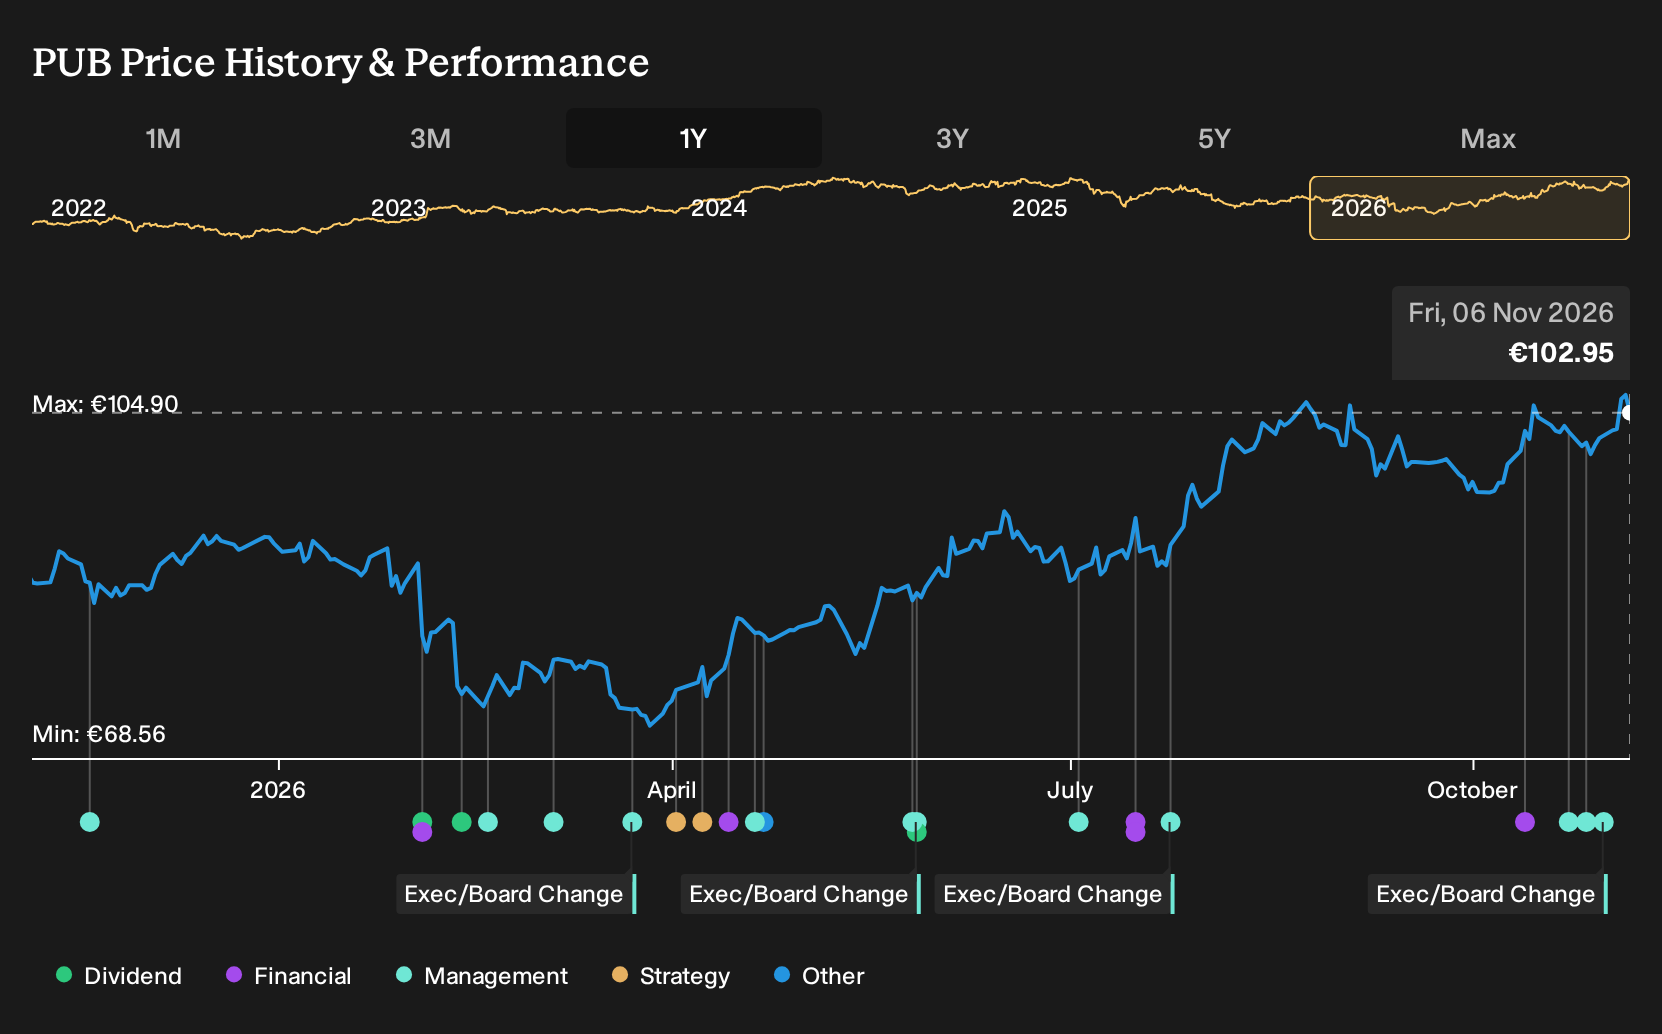
- Publicis Groupe has reshaped its data and AI leadership around the Marcel platform, appointing senior figures such as chief client officer Rohan Philips and media planning and buying director Robin Girdhar, after prior roles at dentsu, GroupM and Times Internet.
- The decision to put an AI focused client leader like Philips into a front line role indicates that Publicis wants its internal Marcel platform directly tied to client facing solutions, rather than treated as back office infrastructure.
- We will look at how Publicis Groupe's investment narrative evolves as Marcel's applied AI focus becomes central to client facing work.
Scan how Publicis Groupe's AI pivot compares with other potential beneficiaries of the same trend by tracking a curated set of 53 AI infrastructure stocks in one place.
Publicis Groupe Investment Narrative Recap
To own Publicis Groupe, you need to believe the group can keep turning its data and AI stack into dependable client demand, while holding margins near recent levels. The Marcel focused reshuffle fits that story by putting product builders into client facing roles. The near term swing factor still looks like execution on AI linked solutions and Connected Media.
The biggest near term risk remains pressure on profitability if cost inflation or pricing limits prevent progress from the 17.5% H1 2026 operating margin and 2025 levels of 18.2%. Leadership changes around Marcel do not remove that risk. They mainly refine who is accountable for delivering on it.
The Philips appointment tied directly to Marcel and applied AI for marketing looks most relevant here. Publicis Groupe is equipping the new chief client officer with a product heavy background just as the group leans on AI powered automation and targets a 25% cut to manual tasks across 114,000 employees. That links senior client roles to the same tools driving efficiency.
For catalysts, the overlap with the planned LiveRamp deal matters. If data co creation and CoreAI are going to support the 7 to 8% net revenue growth and 8 to 10% EPS growth aims for 2027 to 2028, then having Philips and Girdhar translating platforms into media and client solutions is operationally important, even if the regulatory and integration risks around LiveRamp remain unresolved.
Publicis Groupe Consensus Assumptions Around AI Execution
Analysts sketch a relatively steady top line for Publicis Groupe, with revenue expected to stay fairly flat over the next 3 years while profit margins move from 9.2% today to 12.2% by around 2029. That picture leans heavily on Marcel, CoreAI and the broader data stack doing more of the heavy lifting inside client work rather than simply cutting costs in the background.
Earnings forecasts carry more ambition than the revenue line. Consensus points to profit of €2.1b by 2029 compared with €1.6b today, with the most optimistic projections closer to €2.4b. That implies roughly a 31% uplift in earnings on the base case, anchored in a higher margin profile and some help from a modest 0.46% annual reduction in share count.
Valuation expectations align with this earnings bridge. To line up with the €114.38 consensus price target, the equity would need to support a P/E of 17.2x on those 2029 earnings, up from 15.8x today and above the 15.8x cited for the wider GB Media peer group. For anyone tracking Marcel and applied AI inside Publicis Groupe, that multiple effectively prices in both the margin uplift and the belief that AI enabled workflows become standard in client delivery.
Publicis Groupe's narrative projects €17.6b revenue and €2.1b earnings by 2029. This assumes revenue remains fairly flat over the next 3 years and requires an earnings increase of about €0.5b from current earnings of €1.6b.
Uncover how Publicis Groupe's fair value indicates an 11% potential upside to its current price, which could narrow quickly if Marcel execution lands with clients.
Exploring Other Perspectives
One alternate, more optimistic view hinges on Publicis Groupe squeezing more profit out of Marcel and LiveRamp together. The most bullish analysts were already pencilling in €17.9b of revenue and €2.3b of earnings by 2029, with a P/E of 18.5x, before these Philips and Girdhar moves. You can treat those as upper bound scenarios and compare them with your own expectations. Keep in mind that this week’s leadership changes could still reshape every forecast on the table.
Explore 2 other Publicis Groupe fair value estimates, including one that suggests up to 41% potential upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Publicis Groupe research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Publicis Groupe. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Publicis Groupe's overall financial health at a glance.
Looking for more investment ideas beyond Publicis Groupe?
If the Publicis Groupe story has sharpened your thinking on data, AI and margins, it can help to line it up against other listed businesses with very different profiles. Use the Simply Wall St Screener to compare fundamentals, risk and income potential side by side so you are not relying on a single narrative.
- For investors who want income to feel more reliable, scan for companies with stronger yields and payout histories through our curated set of 228 dividend fortresses.
- If balance sheet resilience matters most to you, focus on financially sturdy businesses in the list of solid balance sheet and fundamentals (192 results) and see how they stack up on debt, cash and core profitability.
- When you want to cast a wider net for opportunities the market may be overlooking, widen your search with a hand picked pool of 583 high quality undiscovered gems that combine solid fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com