


EN
Alliant Energy (LNT) Lifts Guidance And Dividend Target, Is The Valuation Still Reasonable?
Alliant Energy (LNT) just packed several developments into a two day window, including stronger third quarter earnings, fresh guidance for 2026 and 2027, a higher 2027 dividend target, and a US$5.1b federal loan package.
The stronger third quarter, higher 2027 dividend target and the US$5.1b loan package appear to have fed into a 10.36% 1 month share price return and an 11.28% 1 year total shareholder return. This suggests building momentum around Alliant Energy as investors reassess both growth potential and risk.
Scan how Alliant Energy’s recent earnings jump, dividend ambitions and federal loan support compare with other regulated utilities by reviewing our hand picked 41 power grid technology and infrastructure stocks in the sector.
So is Alliant Energy’s recent jump a clean read on stronger earnings, richer dividend targets and that US$5.1b loan win, or has sentiment simply swung too far ahead of what the valuation supports?
Most Popular Narrative: 5% Undervalued
On the most followed narrative, Alliant Energy’s fair value of $76.29 sits modestly above the recent $72.67 close, which points to a small gap between the current price and what that narrative suggests is reasonable value. The story focuses on whether contracted data center demand and a multi year capital plan eventually show up in reported earnings in the way forecasters expect.
The accelerating construction and onboarding of large-scale data centers under five executed electric service agreements totaling about 3.4 GW of contracted demand, plus a further 2 to 4 GW pipeline of large-load opportunities, points to a multi year step up in Alliant Energy’s electricity sales and regulated revenue base as these projects ramp through 2031.
See why 7 investors see Alliant Energy as 5% undervalued.
Result: Fair Value of $76.29 (UNDERVALUED)
Still, the Alliant Energy narrative leans heavily on hyperscale data center demand and assumes regulators and investors continue to support higher capital spending without compressing returns.
Find out about the key risks to this Alliant Energy narrative.
Another View on Alliant Energy’s Value
The narrative built around analyst targets presents Alliant Energy as modestly undervalued, with a fair value of $76.29 compared with a $72.67 share price. The SWS DCF model takes a stricter view. On that framework, the stock trades above an estimated future cash flow value of $67.92, which indicates potential overvaluation instead.
Both pictures cannot be correct at the same time. The key question is which lens you consider more reliable when earnings quality and cash generation begin to matter more than narratives about future growth.
Look into how the SWS DCF model arrives at its fair value.
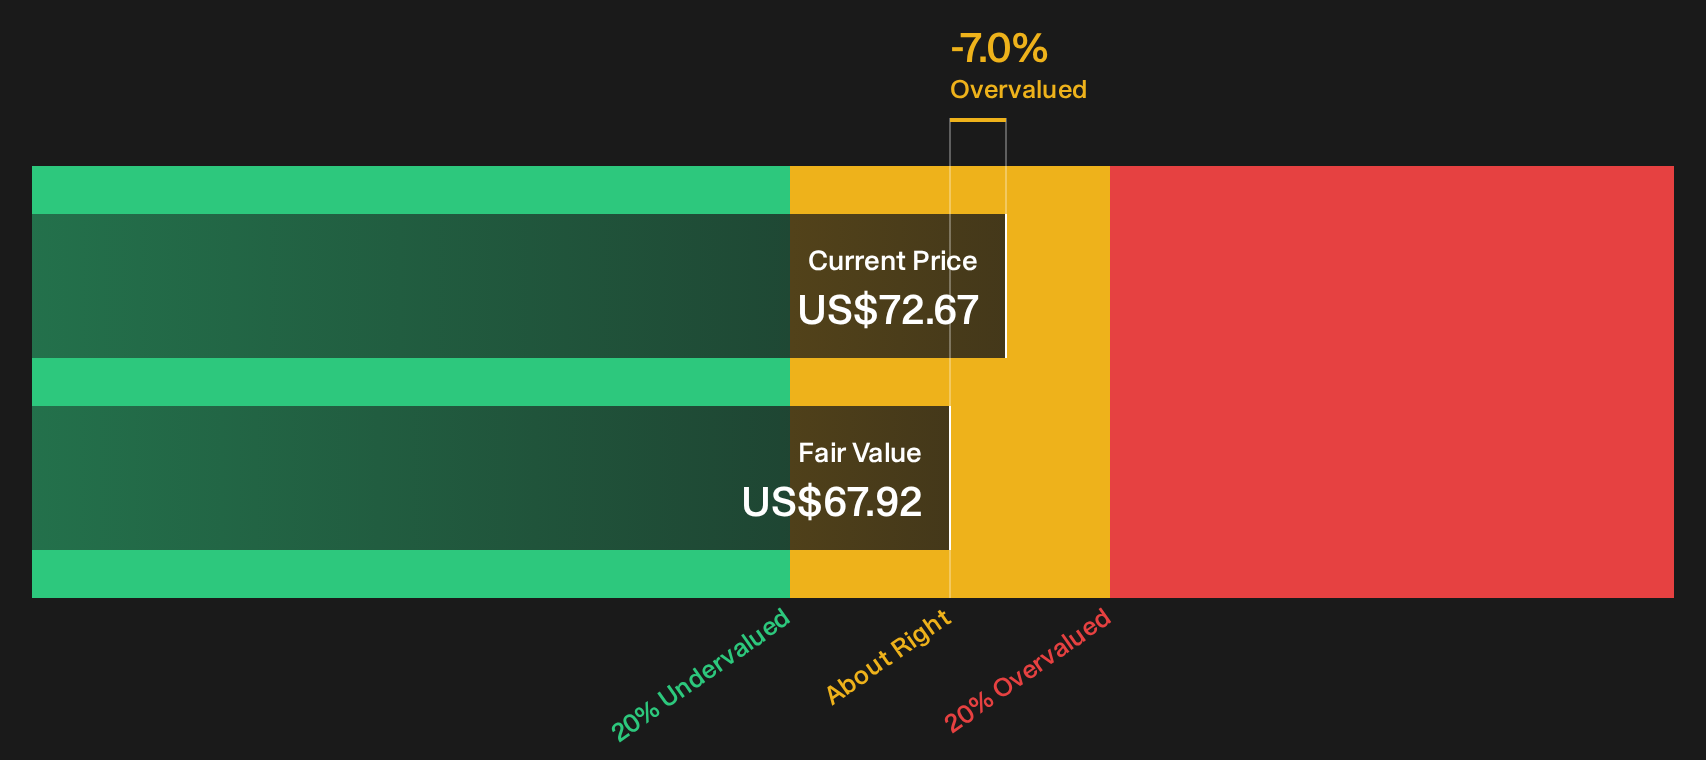
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alliant Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Alliant Energy is mixed, so move quickly from headline stories to hard numbers and weigh both risks and potential upsides through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Alliant Energy?
If you want to stress test your Alliant Energy view and avoid leaving attractive opportunities on the table, use the Simply Wall Street Screener to surface ranked ideas fast.
- Target stronger balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (25 results) that may better align with your risk comfort.
- Hunt for better value by comparing Alliant Energy with the 36 high quality undervalued stocks that combine quality fundamentals with attractive pricing.
- Strengthen your income watchlist by checking the 7 dividend fortresses that focus on higher yields alongside fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com