


EN
American Homes 4 Rent (AMH) Lifted Guidance, Is The Stock Still Undervalued?
Q3 earnings and raised guidance put American Homes 4 Rent in focus
American Homes 4 Rent (AMH) moved into the spotlight after raising its 2026 core FFO guidance alongside reporting third quarter results, updated occupancy metrics, and a fresh round of share repurchases.
The revised outlook now calls for core FFO of US$1.97 per share for 2026, which management framed as 5.3% growth compared with 2025. Investors received that update alongside third quarter core FFO growth of 7.4% year over year, supported by 96% occupancy and a 3.3% increase in renewal rates.
American Homes 4 Rent shares trade at US$32.82, with a 30 day share price return of 6.39% and a 7 day gain of 3.86%. This points to momentum building after the earnings and guidance update, while the 1 year total shareholder return of 6.93% contrasts with a softer 3 year and 5 year record.
Scan how American Homes 4 Rent compares with other income-focused REITs by reviewing a curated set of 7 dividend fortresses in the current rate backdrop.
After a strong run on raised guidance, American Homes 4 Rent now asks a simple question of investors: Does the current price still leave enough upside to justify the risk, once valuation is in focus?
Most Popular Narrative: 12% Undervalued
On the most followed view, American Homes 4 Rent screens as undervalued, with a fair value of $37.11 against the recent $32.82 share price. This puts the current rally up against a valuation gap the narrative still sees as open.
Portfolio optimization through MLS dispositions at cap rates in the 4% area, combined with recycling proceeds into higher yielding on balance sheet and joint venture development, creates a spread between sale yields and development yields. This can support higher net operating income and funds from operations per share.
See why 7 investors see American Homes 4 Rent as 12% undervalued.
Result: Fair Value of $37.11 (UNDERVALUED)
Still, the bullish American Homes 4 Rent story depends on a few pressure points, including the risk of persistently higher interest costs and softer rents in key markets like Texas or Florida.
Find out about the key risks to this American Homes 4 Rent narrative.
Another View On American Homes 4 Rent Using Earnings Multiples
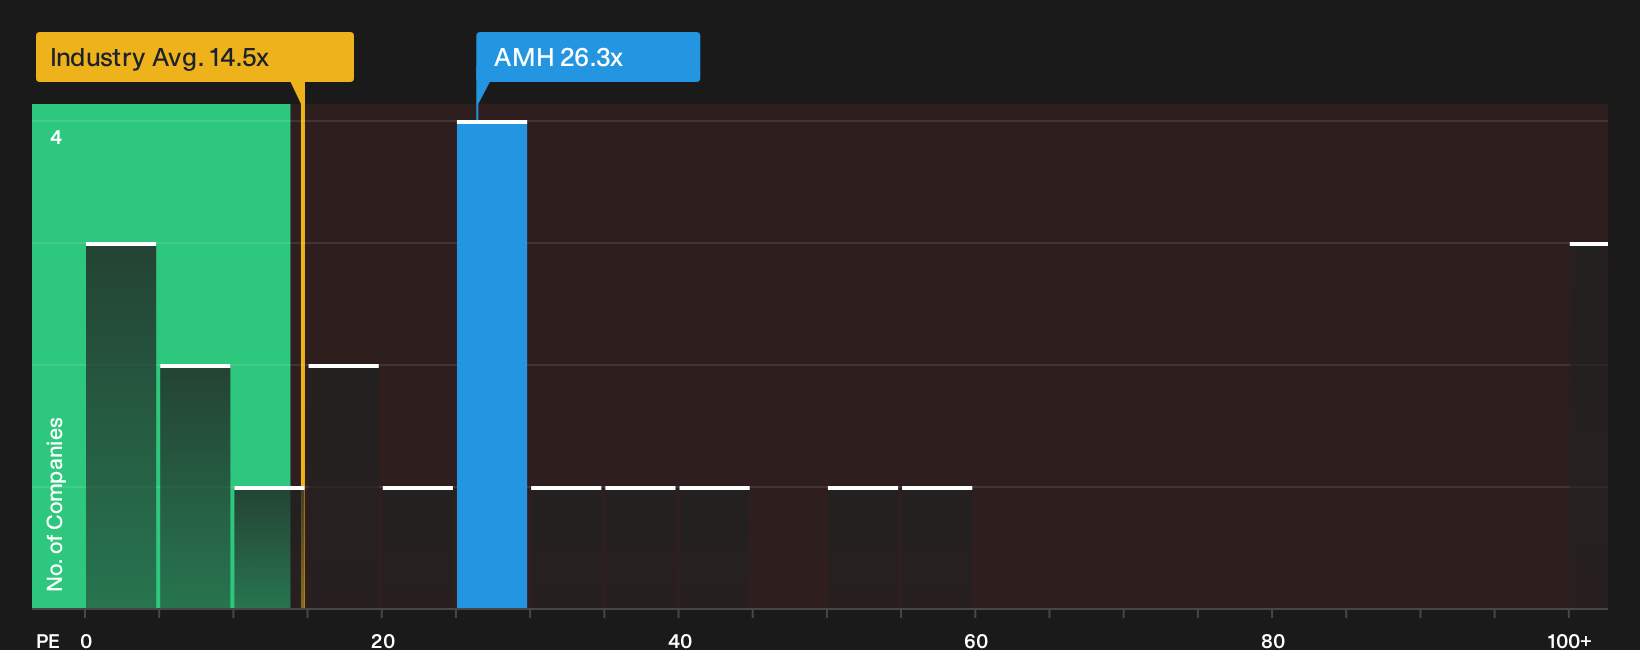
The first bullish story on American Homes 4 Rent leans on fair value of $37.11, yet the earnings multiple picture is less relaxed. The stock trades on a P/E of 26.3x versus a fair ratio of 22.3x, and the global Residential REITs average of 14.6x.
So AMH screens cheaper than close peers on P/E, while still rich relative to the wider industry and its own fair ratio. That mix points to valuation risk sitting alongside perceived upside, which leaves one question for investors to answer: Which reference point matters more to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and fundamentals can be confusing, so consider acting promptly, review the data on American Homes 4 Rent, and weigh both sides by checking 3 key rewards and 3 important warning signs.
Looking for more American Homes 4 Rent style investment ideas?
If you only stop at American Homes 4 Rent, you risk missing other opportunities that fit your style, so put the broader market to work for you.
- Target income potential by reviewing a curated set of 7 dividend fortresses that put dependable cash returns at the center of your watchlist.
- Look for mispriced opportunities and see which companies line up in the 19 high quality undiscovered gems before other investors start paying attention.
- Prioritize resilience under pressure and focus on businesses in the 31 resilient stocks with low risk scores that seek to balance return potential with measured downside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com