


EN
CVS Health (CVS) Stock Still Looks Cheap As Split Plans Take Shape
CVS Health has returned 38.7% over the past three years, even as the business prepares for a major breakup into two listed companies. That combination of share gains and structural change puts a simple question in front of you as an investor: does the current price around US$83.85 still line up with what its earnings can justify?
- A 38.7% gain over three years means long term holders have already seen substantial value creation, so the key issue now is how much of the business's future profit power might already be reflected in that move.
- The plan to split CVS Health into a retail pharmacy company and a separate healthcare solutions business can reshape how earnings are generated and allocated, which may change how the market prices each stream of profit.
- There is a second opinion on CVS Health worth weighing. See what analysts think CVS Health's shares could be worth.
The issue now is whether CVS Health's current share price is adequately supported by the earnings the company is producing today and is expected to produce in the years ahead.
If you want more options built around earnings support and business quality, a focused starting point is a list of 36 high quality undervalued stocks.
Is CVS Health a Bargain on Earnings?
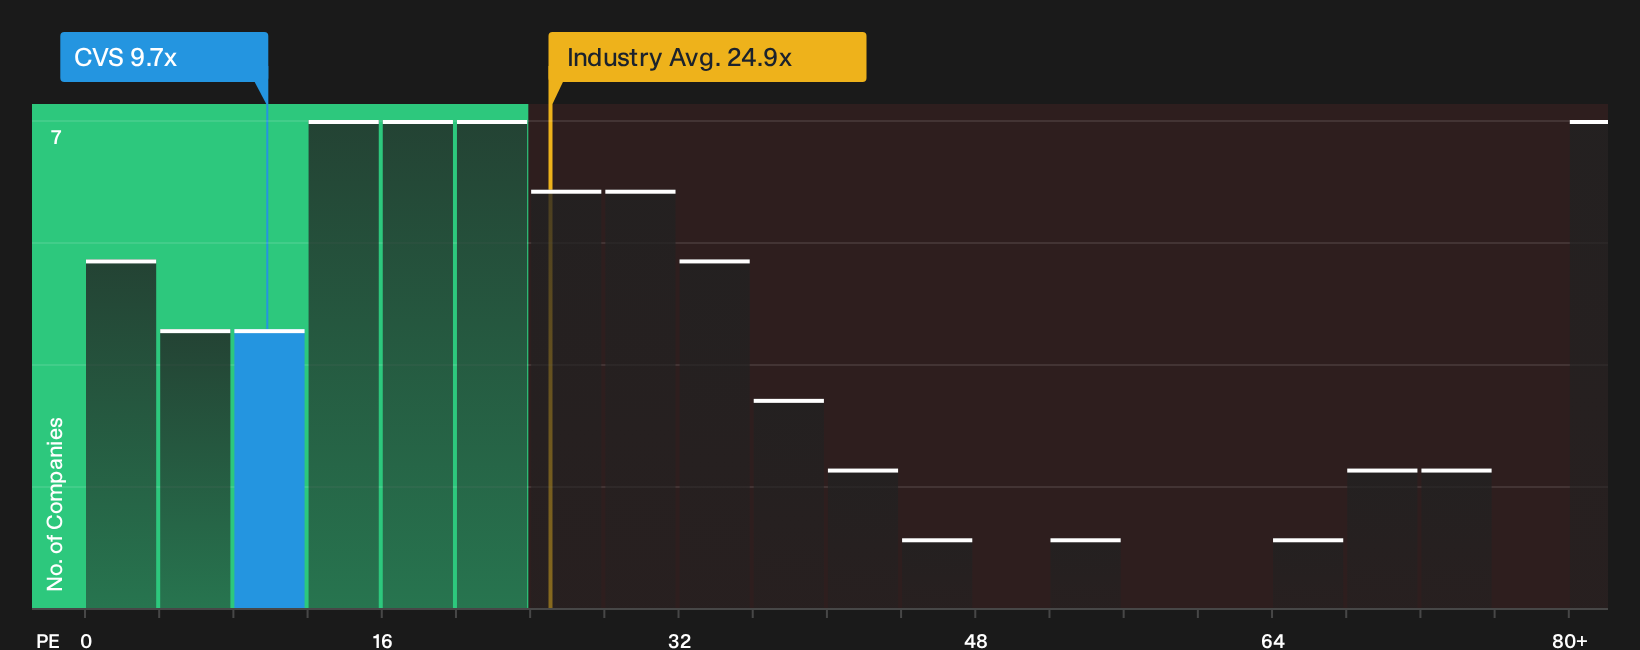
The P/E ratio fits CVS Health because earnings remain a central reference point for how investors value a combined healthcare and pharmacy operation. At roughly 9.7x earnings, the stock trades at a marked discount to the broader Healthcare industry on about 24.9x and also to peers nearer 20.3x. Based on a fair value multiple that reflects this specific mix of growth profile, margins, size and risk, the current P/E sits below where the model would expect CVS Health to trade, which points to the shares screening as undervalued on this measure.
Because the planned 2028 split follows stronger recent earnings guidance, the current discount suggests the market is still applying a cautious lens despite those updates. For you as an investor, the gap between today’s P/E and that tailored fair benchmark raises the question of whether the separation of CVS Pharmacy and the remaining healthcare solutions group could eventually narrow that spread or keep it in place. Explore the numbers behind CVS Health's P/E valuation.
The CVS Health Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for CVS Health by setting out the specific paths for growth, profitability and earnings that would need to hold for the shares to look meaningfully higher or lower than today’s valuation. Instead of stopping at a single output from a ratio or model, they unpack the future that figure relies on so you can watch how the actual business performance tracks against those assumptions over time on Simply Wall St’s Community page.
One of the top community narratives on CVS Health: 19% undervalued
"CVS is no longer trying to be a faster pharmacy. It’s trying to be a more complete healthcare system, and that distinction matters…"
Discover why this Narrative puts CVS Health at 19% undervalued.
Before you decide on CVS Health, one more check belongs beside the price tag
Valuation tells only part of the story for CVS Health. The research also flags specific business risks that deserve your attention before you draw your own conclusion. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com