


EN
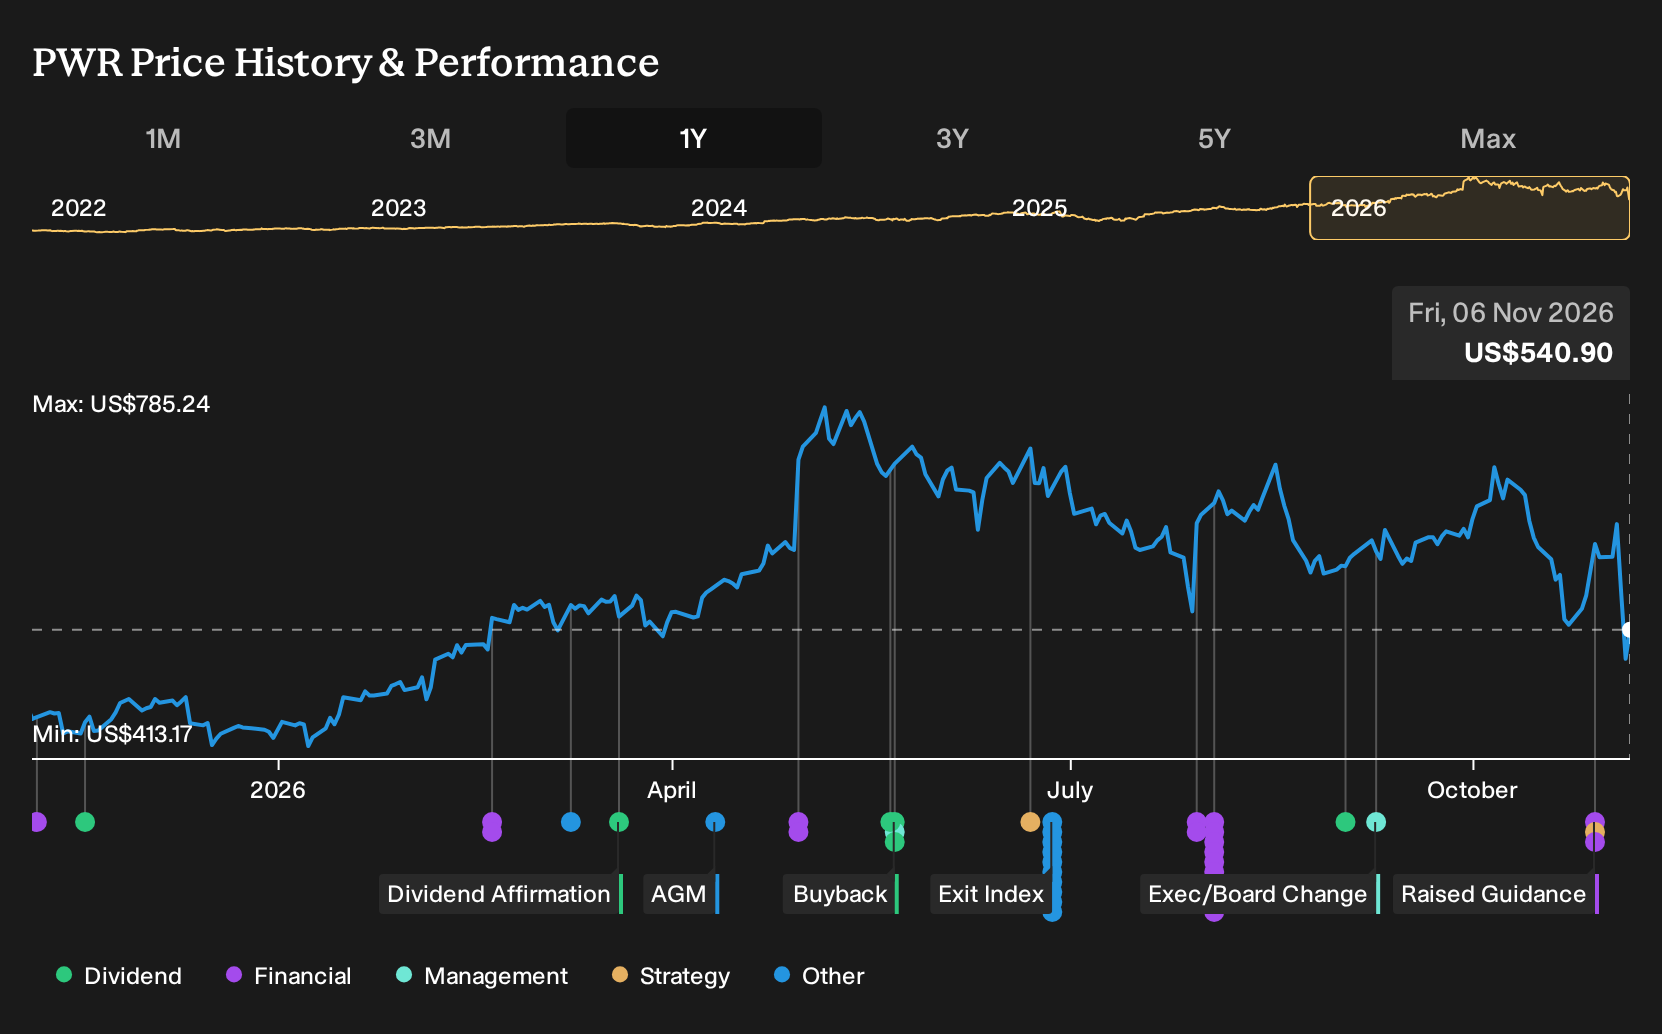
Quanta Services (PWR) Is Up 6.3% What's Changed After Raising 2026 Outlook
- Quanta Services raised its full year 2026 outlook after reporting third quarter revenue of US$12,014.88 million and net income of US$694.86 million, with updated guidance calling for US$41.3b to US$41.6b in revenue and a larger contribution from its record project backlog.
- The business is pairing this higher guidance with an active acquisition pipeline, as management highlights disciplined capital deployment and ongoing opportunities to add businesses that fit its infrastructure platform and support long range demand related to grid and large load projects.
- We will now see how Quanta Services' higher 2026 guidance and record backlog reshape the existing long term investment narrative.
Compare Quanta Services' raised outlook and acquisition appetite with other grid and infrastructure plays by scanning our curated list of 41 power grid technology and infrastructure stocks today.
Quanta Services Investment Narrative Recap
To hold Quanta Services, you need to believe that large scale grid work, data center power needs and underground infrastructure projects keep translating into executable contracts at solid margins. The raised 2026 revenue outlook to US$41.3b to US$41.6b leans on that idea and puts more weight on near term delivery from the record backlog.
The key short term catalyst is execution on high voltage and large load projects already in hand, plus smooth integration of acquired businesses. The biggest risk is that elevated expectations and a higher valuation collide with any project delays, policy hiccups in renewables or weaker earnings contribution from recent deals.
The most relevant update for this story is the third quarter 2026 earnings release. Quanta Services reported quarterly revenue of US$12,014.88 million and net income of US$694.86 million, with basic EPS from continuing operations at US$4.62. For the first nine months of 2026, sales reached US$29,446.66 million and net income was US$1,366.87 million.
Those figures give investors concrete evidence of how the current backlog and earlier acquisitions are flowing through the income statement. They also frame the raised 2026 guidance and ongoing acquisition appetite as an execution test. Future quarters will be judged on whether revenue quality, margins and cash generation support the higher targets without stretching the balance sheet.
What The Analyst Forecasts Assume For Quanta Services
Quanta Services' longer term storyline now leans heavily on a set of explicit analyst assumptions. The forecast calls for revenue to reach US$54.6b by 2029 and earnings to come in at US$2.7b, which analysts expect to support a consensus price target of US$769.04 using a 9.0% discount rate and a P/E of 56.0x on those projected profits.
In the earnings model behind that view, analysts plug in annual top line expansion of 18.4% over the next three years and an uplift in profit margins from 4.0% today to 5.0% by around 2029. The same framework assumes current earnings of about US$1.3b can climb to US$2.7b by the forecast horizon, while the share count is expected to rise by 0.82% a year.
The valuation overlay is straightforward. To align with the consensus, you would need to be comfortable that Quanta Services can translate its backlog and capital spend into that US$54.6b revenue figure, that earnings of US$2.7b are achievable and that investors are still willing to pay a P/E multiple well above the current US construction sector average of 29.1x by 2029.
Quanta Services' narrative projects US$54.6b revenue and US$2.7b earnings by 2029. This implies 18.4% yearly revenue growth and an earnings increase of roughly US$1.4b from about US$1.3b today.
Discover how Quanta Services' fair value suggests a 42% potential upside to its current price before other investors act.
Exploring Other Perspectives
Some of the most optimistic analysts frame Quanta Services around acquisition driven upside rather than valuation risk. Before this guidance hike, that group was already penciling in about US$74.2b of revenue and US$4.6b of earnings by 2029. You now have a raised outlook on the table that those forecasts have not even seen yet. That is why it helps to compare several viewpoints before deciding how this news fits your own expectations.
Explore 5 other Quanta Services fair value estimates, including one that suggests up to 50% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own independent research.
- A great starting point for your Quanta Services research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking For More Ideas Beyond Quanta Services?
If the Quanta Services story has you thinking about where else strong fundamentals or specific income profiles might show up, it can help to widen the lens and compare it with other businesses filtering through the Simply Wall St Screener.
- If capital protection and steadier profiles matter most to you, start with a basket of companies screened for resilience and lower risk scores through our 31 resilient stocks with low risk scores.
- If income is your priority, focus on potential cash generators by reviewing a curated set of higher yielding opportunities via the 7 dividend fortresses.
- If you want to hunt for underappreciated opportunities, cast a wider net across quality companies that may be flying under the radar using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com