


EN
3 US Conglomerate Stocks With Strong Cash Flow in Focus
Berkshire Hathaway just poured a record US$9.6b into its own shares in Q3, with more than US$16b repurchased this year, and that kind of confidence from one of the market’s biggest cash machines tends to grab attention. Investors are hunting for solid, cash rich conglomerates that can hold up when sentiment turns. This article walks through three large cap stocks that are exposed to the same news pulse and explains why each one may deserve closer attention at this time.
The three stocks highlighted below are just a sample from this theme, and the full screen surfaced 23 more large cap conglomerates with equally compelling stories that are not covered here. To go straight to the full US large cap conglomerates list and identify which ones best fit your own risk, income, and valuation filters, head into the US large-cap value and quality conglomerates screener.
Parker-Hannifin (PH)
Parker-Hannifin slots neatly into this value and quality conglomerate theme as a cash generative motion and control specialist that spans everything from aircraft systems to industrial equipment, giving investors broad industrial exposure in a single stock.
Parker-Hannifin manufactures motion and control systems across aerospace, industrial equipment, transportation, energy, and HVAC, fitting the screen’s focus on diversified, cash rich U.S. conglomerates. Revenue is anchored by Diversified Industrial North America at about US$8.8b, Diversified Industrial International at roughly US$6.4b, and Aerospace Systems at around US$7.3b. The business is a large cap with a market value near US$115.7b.
"The completion of the Filtration Group acquisition in August 2026, which is expected to create one of the largest global industrial filtration businesses with broader aftermarket exposure and identified synergies, opens scope for a richer mix of recurring service and replacement revenue that could support higher gross margins and steadier free cash flow."
The real test for Parker-Hannifin now is how one quiet shift in its revenue mix shapes margins and cash generation over the next few years.
If that shift in mix is what really matters for you, read the full narrative for Parker-Hannifin to see how Parker-Hannifin’s cash engine could be quietly accelerating.

Penske Automotive Group (PAG)
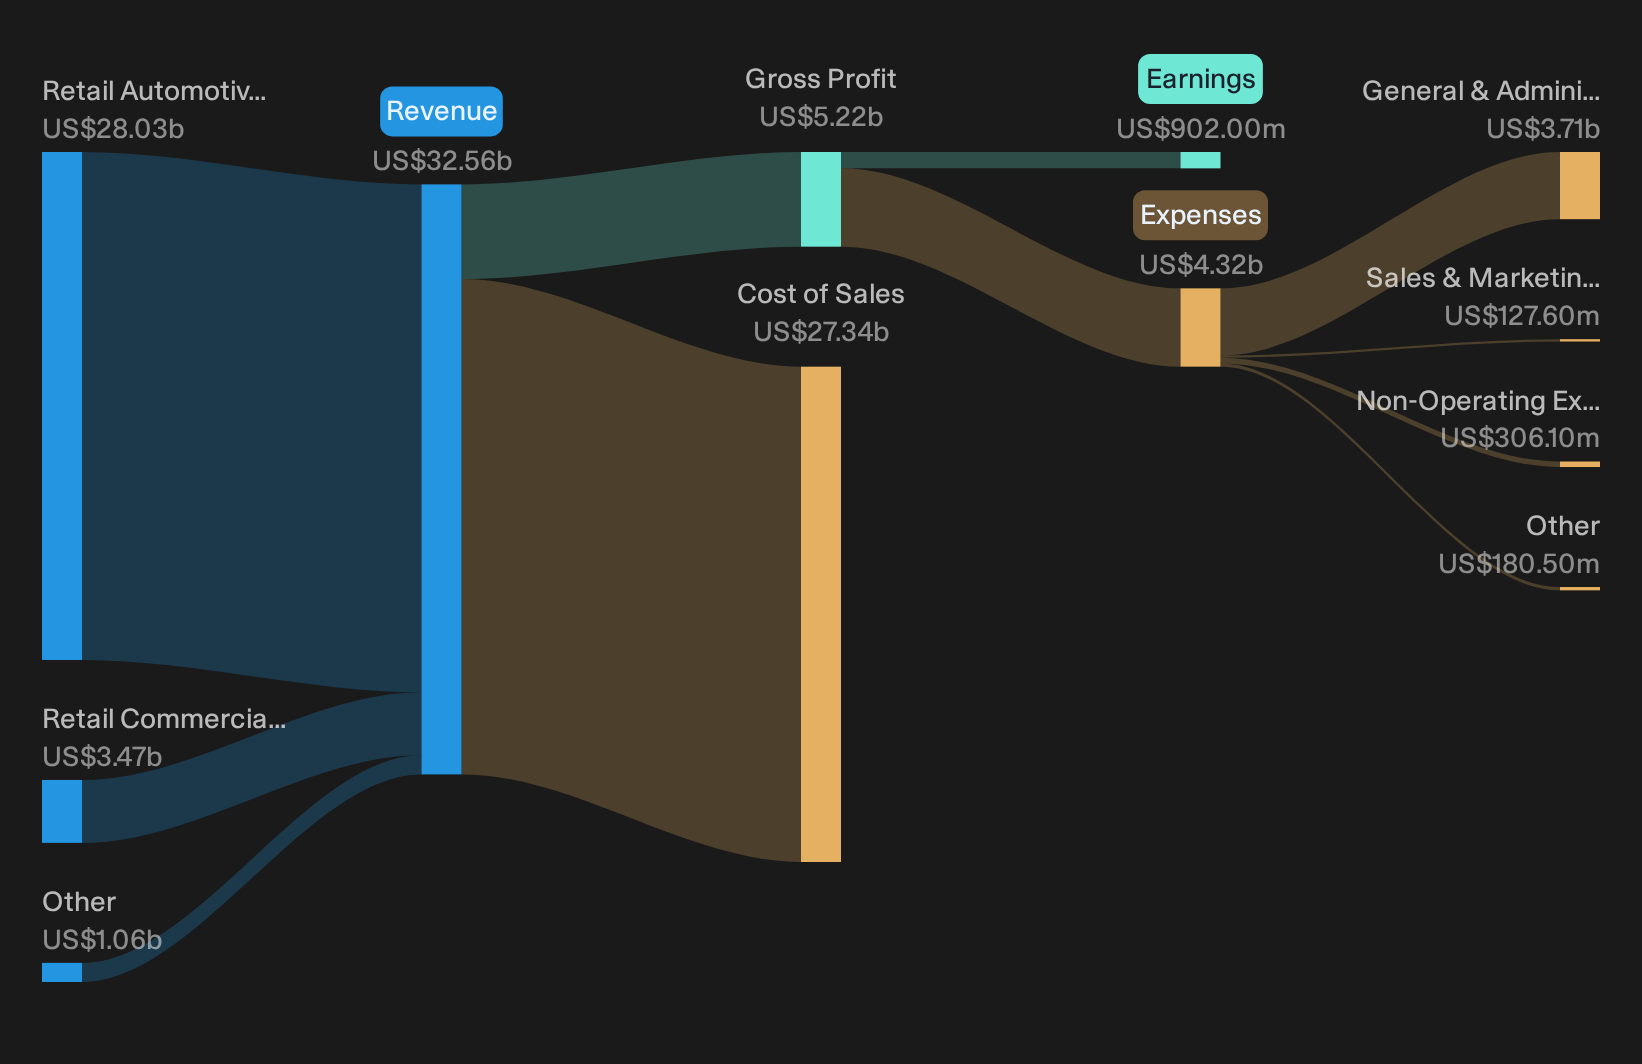
Penske Automotive Group fits this conglomerate screen as a diversified transportation services group, with most revenue tied to Retail Automotive at about US$28.0b, plus Retail Commercial Truck at roughly US$3.5b and Other operations near US$1.1b, and a market value around US$13.9b.
Penske Automotive Group gives you a different spin on the conglomerate theme, mixing car dealerships, commercial trucks, and related services into a single, cash focused platform that investors often watch as a bellwether for both consumer and business demand.
"Although Penske Automotive Group has reiterated an ambition to keep SG&A in the low 70s as a percentage of gross profit, the ratio has instead drifted higher year over year, with Q1 2026 at 74.3% and Q2 2026 at 71.8%."
What happens to the story from here hinges on how one unseen cost pressure ultimately feeds through to margins and long term cash returns.
That cost squeeze is only the starting point, and the full narrative for Penske Automotive Group shows where Penske Automotive Group’s cash cycle could be quietly decoupling from headline pressure.
3M (MMM)
3M fits this large cap conglomerate theme as a diversified industrial and technology group that mixes safety gear, electronics materials, and everyday consumer products. This gives you broad exposure to cash focused, globally spread earnings under one roof.
3M generates about US$12.1b from Safety and Industrial, US$8.4b from Transportation and Electronics, and US$4.9b from Consumer, with a market value near US$95.7b.
What matters for this screen is how 3M uses that mature, diversified footprint and long record of dividends and buybacks to echo the kind of cash rich, resilient profile investors are focusing on after Berkshire’s latest repurchase binge.
"The acceleration in new product launches, now at an expected 350 plus in 2026 with 176 launches in the first half and five-year new product sales expected to reach about US$4b, continues to build on 3M’s R&D factory model and rising New Product Vitality Index. This can support future revenue outgrowth versus end markets and help mix up gross margins and earnings."
What happens to 3M’s appeal inside this value and quality screen could depend on how one lingering risk interacts with that cash heavy playbook.
That tension between risk and reinvention is exactly what the full narrative for 3M examines, showing where 3M’s cash engine and product pipeline might be quietly accelerating.

Seeking Fresh Alternatives Before They Fly?
Markets move fast and the best breakout ideas often shift from under the radar to fully priced before most investors even notice. Scan these fresh lists now and review them while they are still emerging.
- Target resilient cash generators that can keep moving even when headlines turn, using a curated set of 31 resilient stocks with low risk scores built to prioritize staying power over drama.
- Consider real earnings momentum instead of hype by focusing on 40 profitable AI stocks that aren't just burning cash that already turn AI demand into cash rather than promises.
- Track the next potential infrastructure breakout story with a focused basket of 41 power grid technology and infrastructure stocks while the grid upgrade theme is still under many investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com