


EN
DXC Technology (DXC) Could Be 19% Overvalued On Weak Earnings And Lower Guidance
DXC Technology earnings and guidance set the tone
DXC Technology (DXC) has been in focus after reporting second quarter results that showed lower quarterly sales and profit than a year earlier, alongside new guidance that points to further organic revenue declines.
The firm posted second quarter revenue of US$3,034 million compared with US$3,161 million in the prior year period. Net income for the quarter was US$24 million, down from US$36 million, with basic and diluted earnings per share from continuing operations at US$0.15 versus US$0.20 previously.
Over the first six months to September 30, 2026, DXC Technology recorded sales of US$6,033 million compared with US$6,320 million a year earlier. Net income for this half year was US$146 million compared with US$52 million, while basic earnings per share from continuing operations reached US$0.91 versus US$0.29 and diluted earnings per share from continuing operations came in at US$0.89 versus US$0.29.
Despite the softer guidance, DXC Technology shares have climbed recently, with a 30 day share price return of 19.84% and a 90 day gain of 36.21%. However, the 5 year total shareholder return is still down 55.43%, which suggests short term momentum is building while longer term holders remain underwater.
Scan beyond DXC Technology and compare this earnings-driven move with other IT and software plays using our curated list of 19 high quality undiscovered gems.
A near 20% rise in 30 days, a price above the average analyst target, and a modeled intrinsic discount of 54%. Where might fair value for DXC Technology realistically sit in that spread?
Most Popular Narrative: 19% Overvalued
DXC Technology last closed at $14.86, while the most followed narrative frames fair value at $12.50, using a 12.54% discount rate and a detailed set of revenue, margin and P/E assumptions to reach that figure.
The main thing that has to go right is DXC Technology executing on its shift from labor intensive services to AI driven, product and SaaS led offerings while delivering the planned $1.0 to $1.5 billion cost reduction and margin uplift.
The current valuation and this narrative’s view that DXC Technology is fairly valued and bullish together imply that the share price already reflects both the execution risks around the AI transition and the potential benefits from higher margin, capital light growth.
See why 14 investors see DXC Technology as 19% overvalued.
Result: Fair Value of $12.50 (OVERVALUED)
Still, ongoing organic revenue declines and pressure in the Global Infrastructure Services segment could quickly challenge any fair value case built around DXC Technology’s AI transition.
Find out about the key risks to this DXC Technology narrative.
Another View: DXC Technology on Earnings-Based Value
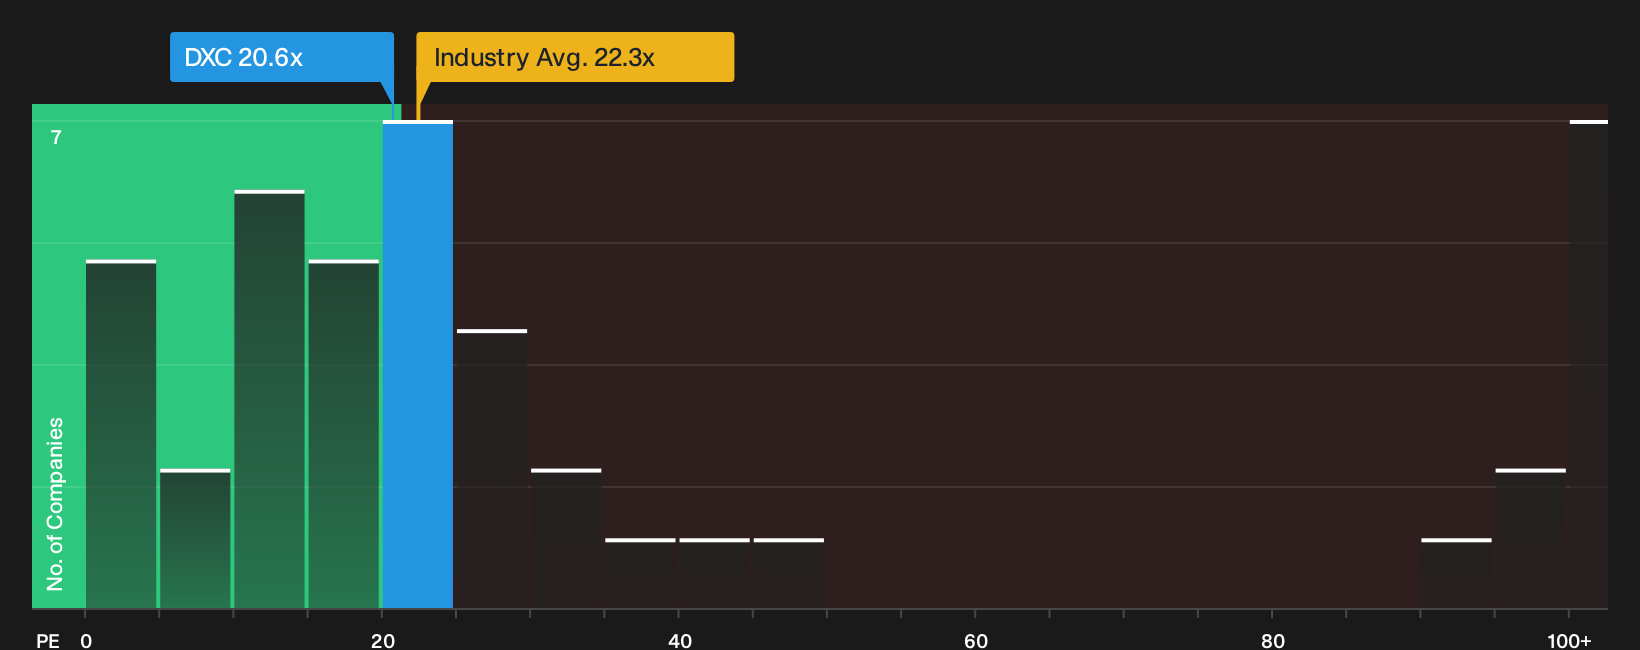
Analysts calling DXC Technology 19% overvalued on a $12.50 fair value are relying on one set of cash flow and growth assumptions. Through a simple earnings lens, the stock trades on a P/E of 20.6x versus a peer average of 23.3x and a fair ratio of 23x, which points to a tighter valuation debate. If the market moves toward that fair ratio, are you comfortable with the risk that both the multiple and the narrative could shift at the same time?
To see how that earnings based view compares with a fuller set of valuation checks, including the fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on DXC Technology so far. If you want to move past headlines and sentiment, consider the trade offs directly and review the 3 key rewards and 3 important warning signs.
Looking for more DXC Technology sized opportunities?
If DXC Technology has you rethinking your watchlist, do not stop here. Broader idea hunting is where many investors find their next edge.
Scan for quality at a discount and see which companies clear strict value and fundamentals checks using the 36 high quality undervalued stocks.
Strengthen your defensive side by finding businesses that pair resilient balance sheets with solid fundamentals through the list of solid balance sheet and fundamentals (25 results).
Target income-focused ideas and uncover companies offering robust yield profiles with the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com