


EN
Did Transnet Rail Deal Just Shift Wabtec Stock's Investment Narrative?
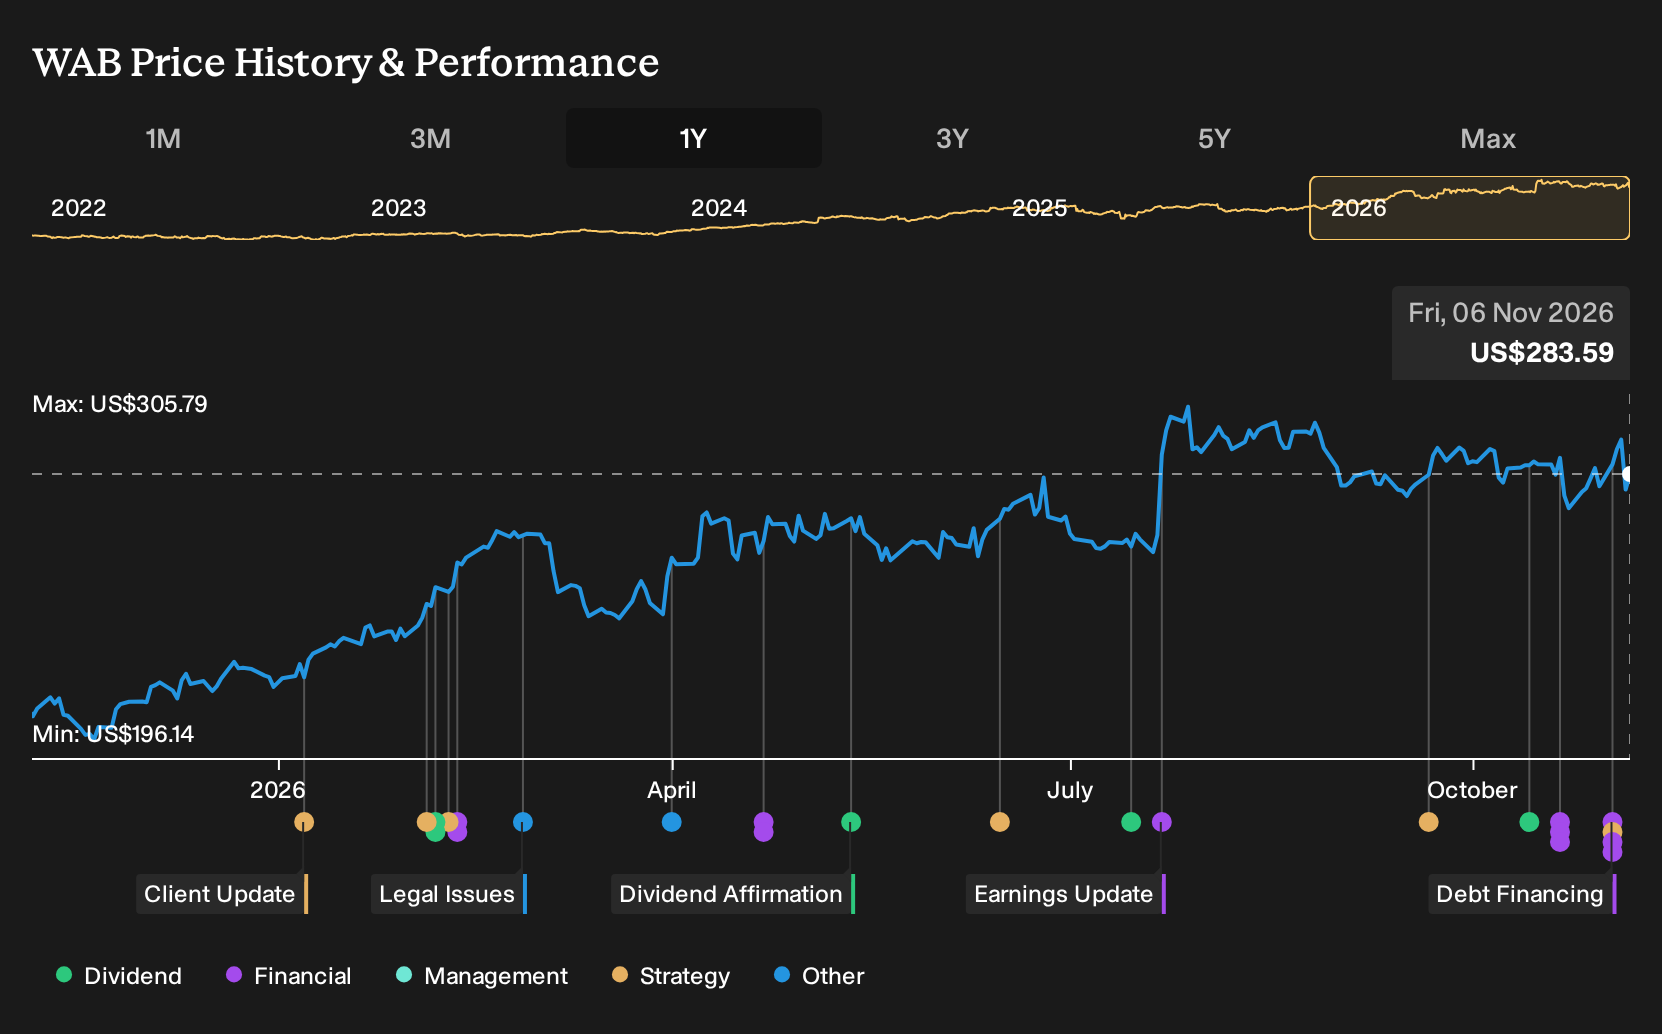
- Westinghouse Air Brake Technologies, through Wabtec Corporation, issued US$500 million of 5.9% Senior Notes due 2037 and plans to use the proceeds alongside other borrowing to repay its 3.45% Senior Notes maturing in November 2026.
- Wabtec Corporation also signed a long term Material and Technical Support Agreement with Transnet Engineering worth about US$390 million, tying Westinghouse Air Brake Technologies deeper into lifecycle maintenance, digital monitoring and skills development in South Africa’s rail sector.
- Attention now turns to how Westinghouse Air Brake Technologies’ investment narrative is shaped by this long term Transnet Engineering support agreement.
Compare Westinghouse Air Brake Technologies' latest financing and rail contract moves with other infrastructure focused opportunities by scanning the hand picked 41 power grid technology and infrastructure stocks shaping long term transport and energy networks.
Westinghouse Air Brake Technologies Investment Narrative Recap
To own Westinghouse Air Brake Technologies you need to believe its large installed base, multiyear rail backlog and growing digital offerings can offset a softer modernization cycle and tariff pressure. The recent US$500 million notes issue and Transnet agreement sit in the background here. They do not materially change that core thesis today.
The near term swing factor still looks like execution on services, modernization and Digital Intelligence growth, while keeping margins resilient against tariffs and input costs. The biggest risk remains a prolonged slowdown in modernization activity combined with any stumble on cost mitigation that keeps net margin expansion in check.
The long term Material and Technical Support Agreement with Transnet Engineering is the announcement that most clearly links back to Westinghouse Air Brake Technologies’ catalysts. It extends lifecycle maintenance, parts and digital monitoring around a defined locomotive fleet. This ties directly into the push to grow higher margin services and software centric offerings.
This MTSA also concentrates operational risk in execution. Performance on availability, turnaround times and predictive maintenance will shape how credibly Wabtec can pitch similar long horizon contracts in other freight and transit markets. For investors watching catalysts, contract delivery, tariff management and modernization volumes remain the key checkpoints over the next stretch.
Westinghouse Air Brake Technologies' current analyst narrative points to revenues of US$14.8b and earnings of US$2.4b by 2029, based on an assumed 7.3% yearly revenue growth rate and an earnings increase of about US$1.1b from US$1.3b today.
Uncover why Westinghouse Air Brake Technologies' fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
There are 2 fair value estimates from the Simply Wall St Community, clustering between about US$281 and US$330, so opinions already span a wide price band. When you set those pre news views against tariff pressure, softer modernization volumes and the new Transnet and debt deals, you can see why investor opinions can diverge sharply. Explore the different assumptions before deciding how Westinghouse Air Brake Technologies fits your own rail exposure.
Explore another Westinghouse Air Brake Technologies fair value estimate, including one that suggests up to 16% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Westinghouse Air Brake Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Westinghouse Air Brake Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westinghouse Air Brake Technologies' overall financial health at a glance.
Looking for more Westinghouse Air Brake Technologies sized ideas?
If you want to put what you have learned about Westinghouse Air Brake Technologies into context, compare it with other businesses that fit your own risk, income and quality preferences using the Simply Wall St Screener.
- For investors who want income that looks more resilient, review a collection of high yielding payout candidates through the 7 dividend fortresses.
- If capital preservation comes first for you, filter for companies with steadier profiles by starting with the 31 resilient stocks with low risk scores.
- If you prefer hunting for under followed opportunities with solid fundamentals, widen your research universe via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com