


EN
SI-BONE (SIBN) Just Put Itself Back In The Spotlight
SI-BONE (SIBN) has drawn fresh attention after reporting third quarter results that showed higher sales and a smaller net loss. Management also reaffirmed full year revenue guidance in the range of $231 million to $233 million.
Recent trading has picked up speed, with SI-BONE posting a 7-day share price return of 14.2% and a 30-day gain of 28.5%. The 1-year total shareholder return of 53.7% points to momentum that has been building rather than fading over a longer stretch.
Look beyond SI-BONE's recent momentum and compare it with other fast-moving healthcare names using our hand-picked list of 35 healthcare AI stocks.
After a 1 year total return above 50% and a recent sprint higher, SI-BONE now trades only modestly below analyst targets, yet at a steep discount to intrinsic estimates. Where does fair value really sit in that gap?
Most Popular Narrative: 5% Undervalued
At a last close of $24.24, the most followed narrative for SI-BONE points to a fair value of $25.44. This leaves a small valuation gap that depends on execution and reimbursement playing out as expected.
High gross margins around 79% in recent quarters, positive operating cash flow and an asset-light model with modest CapEx needs give SI-BONE room to keep investing in R&D and commercial capacity. This can support sustained revenue growth while allowing adjusted EBITDA and free cash flow to expand.
See why 5 investors see SI-BONE as 5% undervalued.
Result: Fair Value of $25.44 (UNDERVALUED)
Still, the SI-BONE story can break if U.S. focused reimbursement shifts unfavorably or if the ongoing iFuse TORQ recall continues to increase costs and reduce procedure volumes.
Find out about the key risks to this SI-BONE narrative.
Another View: What Multiples Say About SI-BONE
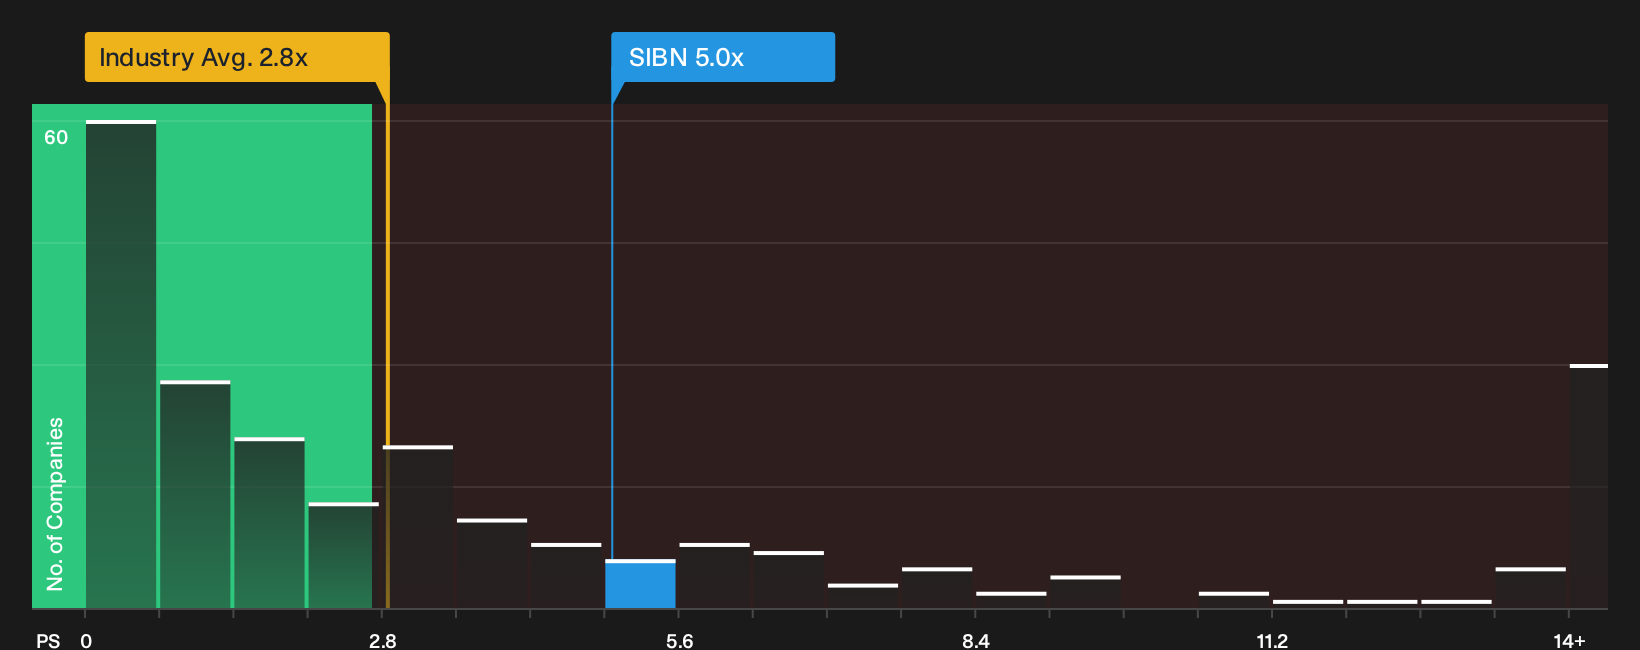
The story looks very different when you shift from fair value estimates to simple trading multiples. SI-BONE changes hands at about 5x P/S, compared with a peer average of 4.1x and a US Medical Equipment sector average of 2.8x. The fair ratio sits at 4.2x, which means the current tag already builds in a richer valuation than both the sector and the level the market could move toward. Is that premium a sensible price for the growth narrative, or a risk if sentiment cools?
For a closer look at what the numbers imply for this valuation gap, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around SI-BONE is split between optimism and caution. Move quickly, review the full picture, and decide where you stand on the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond SI-BONE?
If you only stop with SI-BONE, you miss a wider field of opportunities. Put a shortlist together now and keep your next move on the front foot.
- Target stronger value plays by scanning companies that pass strict quality and pricing filters with the 36 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with clean finances and robust fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for tomorrow's potential outliers by reviewing financially sound stocks that are still off most investors' radar through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com