


EN
How Investors May Respond To Hershey (HSY) Raised Earnings Guidance
- Hershey reported third quarter 2026 sales of US$3,275.51 million and net income of US$580.81 million, then lifted full year guidance to around 5% net sales growth and reported diluted EPS of US$8.00 to US$8.26.
- The guidance increase followed much higher earnings for both the quarter and year to date, with tariff refunds and cost actions supporting reported profit and sharpening focus on how durable Hershey's cash generation can be.
- Investors will now assess how Hershey's higher full year earnings guidance reshapes the investment narrative built around its defensive cash flows.
Hershey Investment Narrative Recap
To own Hershey, you need to be comfortable with a business built around pricing power in chocolate and expansion in salty snacks, while managing volume pressure and market share loss in U.S. confectionery. The short term swing factor is whether recent Halloween softness eases and holiday sell through holds up as higher prices meet stretched consumers.
The biggest near term risk remains pushback on pricing and constrained salty snack capacity, which could pressure revenue and margins as earlier price benefits fade. The latest earnings and guidance upgrade are important, but do not remove those execution questions around volume, share and supply chain improvements.
The 2026 holiday lineup is the announcement that speaks most clearly to Hershey’s current catalyst. Management is leaning into seasonal occasions with Hershey’s Kisses Cindy Lou Who Strawberry Sugar Cookie candies, Kit Kat Santa & Reindeer and Reese’s Reindeer Mix to support volume, mix and brand relevance during a critical quarter.
For you as an investor, the key question is whether this broader portfolio, including salty and better for you options like SkinnyPop Elf Maple Syrup Kettle Corn and LesserEvil Himalayan Sweetness Popcorn, can offset pressure in core chocolate volumes. Execution on this pipeline and on shelf performance through the holidays will feed directly into how credible the current growth and margin story looks.
Hershey's narrative projects US$13.1b revenue and US$2.1b earnings by 2029. This assumes 2.5% yearly revenue growth and an earnings increase of about US$600 million from current earnings of US$1.5b.
Uncover why Hershey's fair value indicates a potential 9% upside to its current price that could narrow quickly.
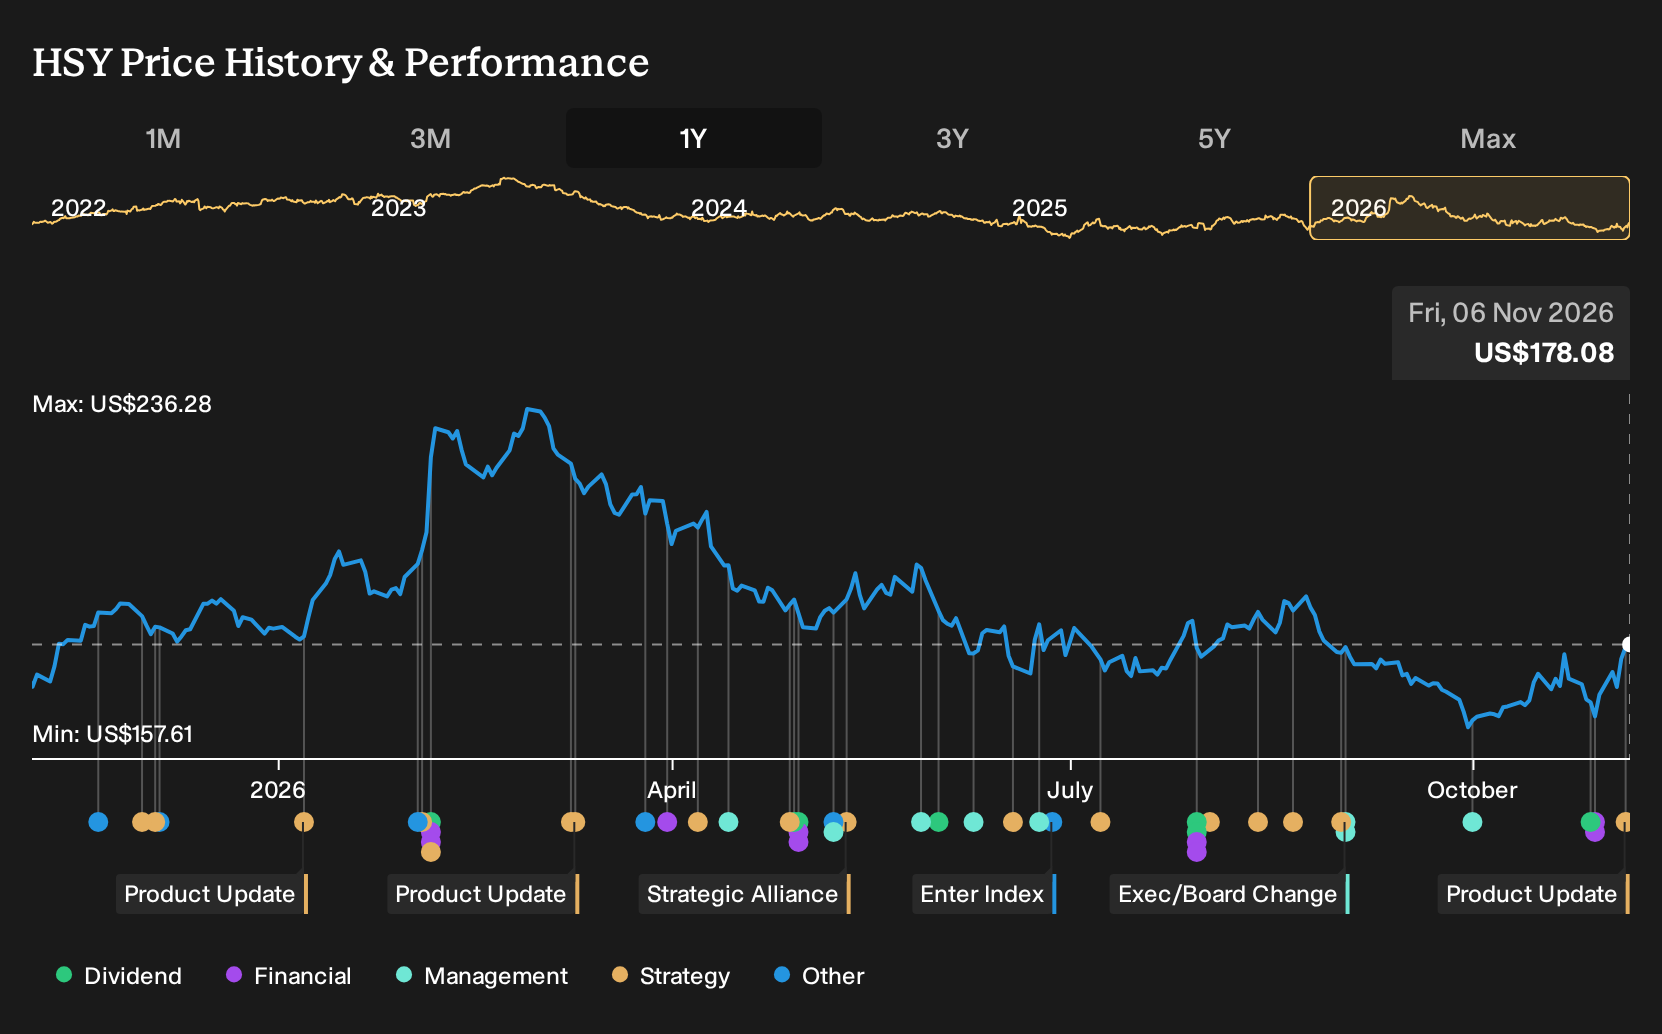
Exploring Other Perspectives
Some of the most optimistic analysts see Hershey’s salty snacks and protein bars as the real swing factor. Before this guidance and holiday launch, they were penciling in revenue of about US$13.4b and earnings of roughly US$2.5b by 2029. You can use those more bullish assumptions as a contrast point and explore how views may shift after the latest earnings and seasonal lineup.
Explore 4 other Hershey fair value estimates, including one that suggests as much as 18% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hershey research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hershey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hershey's overall financial health at a glance.
Looking for more investment ideas beyond Hershey?
Once you have a view on Hershey, it can help to widen the lens and compare it with other businesses that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener lets you move from a single stock story to a broader watchlist built around the traits that matter most to you.
- If you care most about quality at a reasonable entry point, start with companies flagged as 36 high quality undervalued stocks and see which ones fit your return and risk limits.
- For investors who want income on top of potential capital gains, lean into high yield opportunities by scanning a curated set of 7 dividend fortresses that may suit a cash flow focused portfolio.
- If resilience and balance sheet strength are your priority, focus on financially robust businesses by filtering for a list of solid balance sheet and fundamentals (25 results) that can anchor your holdings through different market conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com