


EN
IREN (IREN) Rallies After Q1 Results As AI Backlog Fuels Undervalued View
IREN (NasdaqGS:IREN) jumped nearly 20% after its fiscal Q1 2027 report, as AI cloud revenue nearly tripled, adjusted EBITDA margin improved, and a large contracted backlog with Microsoft and Nvidia drew fresh investor attention.
The post-earnings surge comes after a bruising stretch for IREN, with the 30 day share price return down 38.51% and the year-to-date move lower by 49.32%, despite a very large three-year total shareholder return of about seven times.
Scan how other AI infrastructure plays are reacting to the same demand story by checking the 53 AI infrastructure stocks that investors are watching now.
IREN just erased a chunk of its recent slide in a single session, which puts one issue front and center: Is this jump really catching up to the underlying AI cloud contracts and backlog, or is it mostly sentiment snapping back after a rough year?
Most Popular Narrative: 70% Undervalued
IREN closed at $21.64 while the most followed narrative pegs fair value near $71, which frames the post-earnings bounce as only a small catch-up move rather than a full rerating.
The core balance sheet math hasn't changed: IREN is still priced like a miner, contracted like a utility, and growing like a hyperscaler. I am holding my full position because the 5GW infrastructure thesis remains intact, but my patience for investor relations theater has worn thin.
See why 287 investors see IREN as 70% undervalued.
Result: Fair Value of $71.48 (UNDERVALUED)
Still, the IREN story can break if the huge FY27 CapEx plan strains funding, or if operational delays push contracted AI capacity further out.
Find out about the key risks to this IREN narrative.
Another Look At IREN’s Valuation
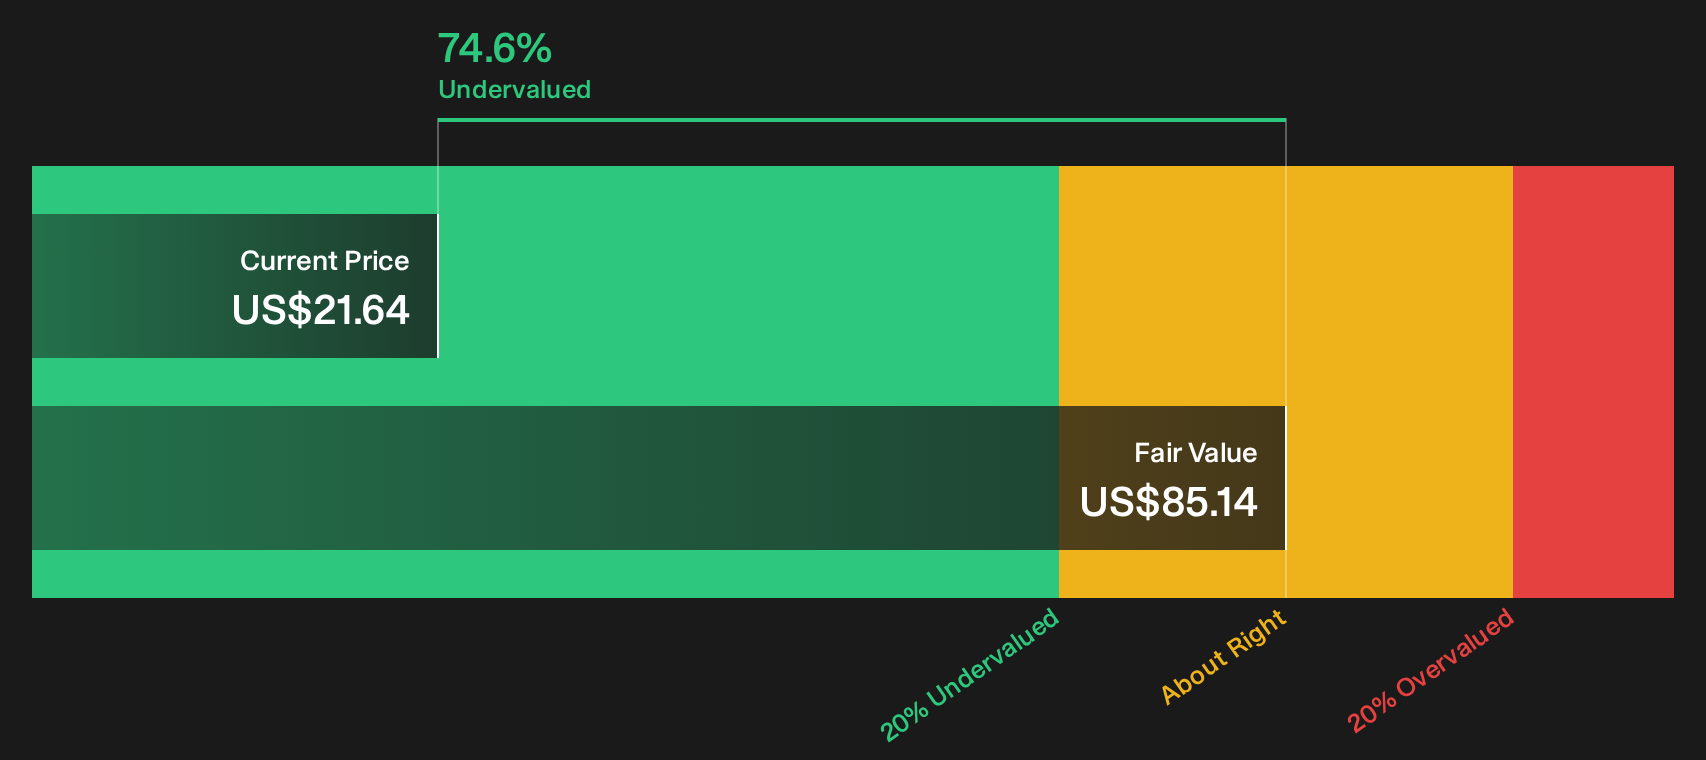
On one hand, IREN screens cheap against its own SWS DCF fair value, trading at $21.64 versus an estimated future cash flow value of $85.14, a discount of about 75%. On the other, the stock carries execution, funding, and AI cycle risks that a spreadsheet cannot fully capture. Which lens do you trust more when real money is on the line?
Before leaning too heavily on any single model, it helps to see exactly how those cash flows are built and stressed in different scenarios. That way, you can judge whether the inputs match your own expectations for IREN's AI and data center rollout. Look into how the SWS DCF model arrives at its fair value.
Next Steps
If you are unsure whether IREN’s recent surge aligns with the AI backlog and funding risks described above, and want to examine both the optimistic and cautious viewpoints more closely, review the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond IREN?
Do not let the IREN move be the only thing on your radar. Cast a wider net with a few focused stock ideas built from fundamentals.
- Target income resilience by reviewing a shortlist of companies designed to act like 7 dividend fortresses in a yield hungry market.
- Hunt for mispriced opportunities by scanning a curated pool of 19 high quality undiscovered gems before the crowd starts paying attention.
- Prioritize capital preservation by filtering for 31 resilient stocks with low risk scores that aim to balance return potential with lower downside risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com