


EN
Edgewise Therapeutics Stock Gains Attention After Phase 3 Trial Plan Submission
- Edgewise Therapeutics reported past third quarter 2026 net income of US$1.17b and filed a Phase 3 STRATUS HCM protocol for EDG-7500 after favorable FDA, EMA and PMDA feedback on an echo independent dose escalation design in obstructive and nonobstructive hypertrophic cardiomyopathy.
- The regulator aligned Phase 3 plan uses investigator assessed titration without routine echo based dosing, which may simplify future real world use and has implications for trial execution costs and speed.
- The next focus is on how Edgewise Therapeutics' investment narrative is affected by the regulator aligned Phase 3 design for EDG-7500.
Edgewise Therapeutics Investment Narrative Recap
To own Edgewise Therapeutics, you have to be comfortable with a focused bet on EDG-7500 and, to a lesser extent, EDG-15400 while the business still has no recurring product revenue. The big picture is simple. Long term value depends on turning promising hypertrophic cardiomyopathy and HFpEF programs into approved drugs that can support meaningful future sales.
The main near term swing factor remains EDG-7500 execution in Phase 3. The regulator aligned STRATUS HCM design and echo independent titration plan look operational, not thesis changing on their own. The biggest current risk is binary clinical and regulatory progress for EDG-7500, given its outsized role in the story.
The November 2026 earnings release is the announcement that ties most tightly to the current EDG-7500 news. Edgewise Therapeutics reported third quarter net income of US$1,166.15 million and nine month net income of US$1,059.81 million, moving from losses a year ago to reported profitability on a trailing basis.
Those figures are heavily influenced by one off items linked to the Servier transaction rather than ongoing product sales. As a result, they do not remove execution risk around STRATUS HCM. What they do change is financial footing. With a materially stronger balance sheet, management has more room to fund the Phase 3 program and the EDG-15400 pipeline without relying as heavily on fresh capital as a near term catalyst.
Edgewise Therapeutics' current analyst narrative points to forecast revenue of US$135.6 million and projected earnings of US$22.1 million by 2029, compared with earnings today of a US$197.2 million loss. This implies an earnings swing of roughly US$219 million from current levels.
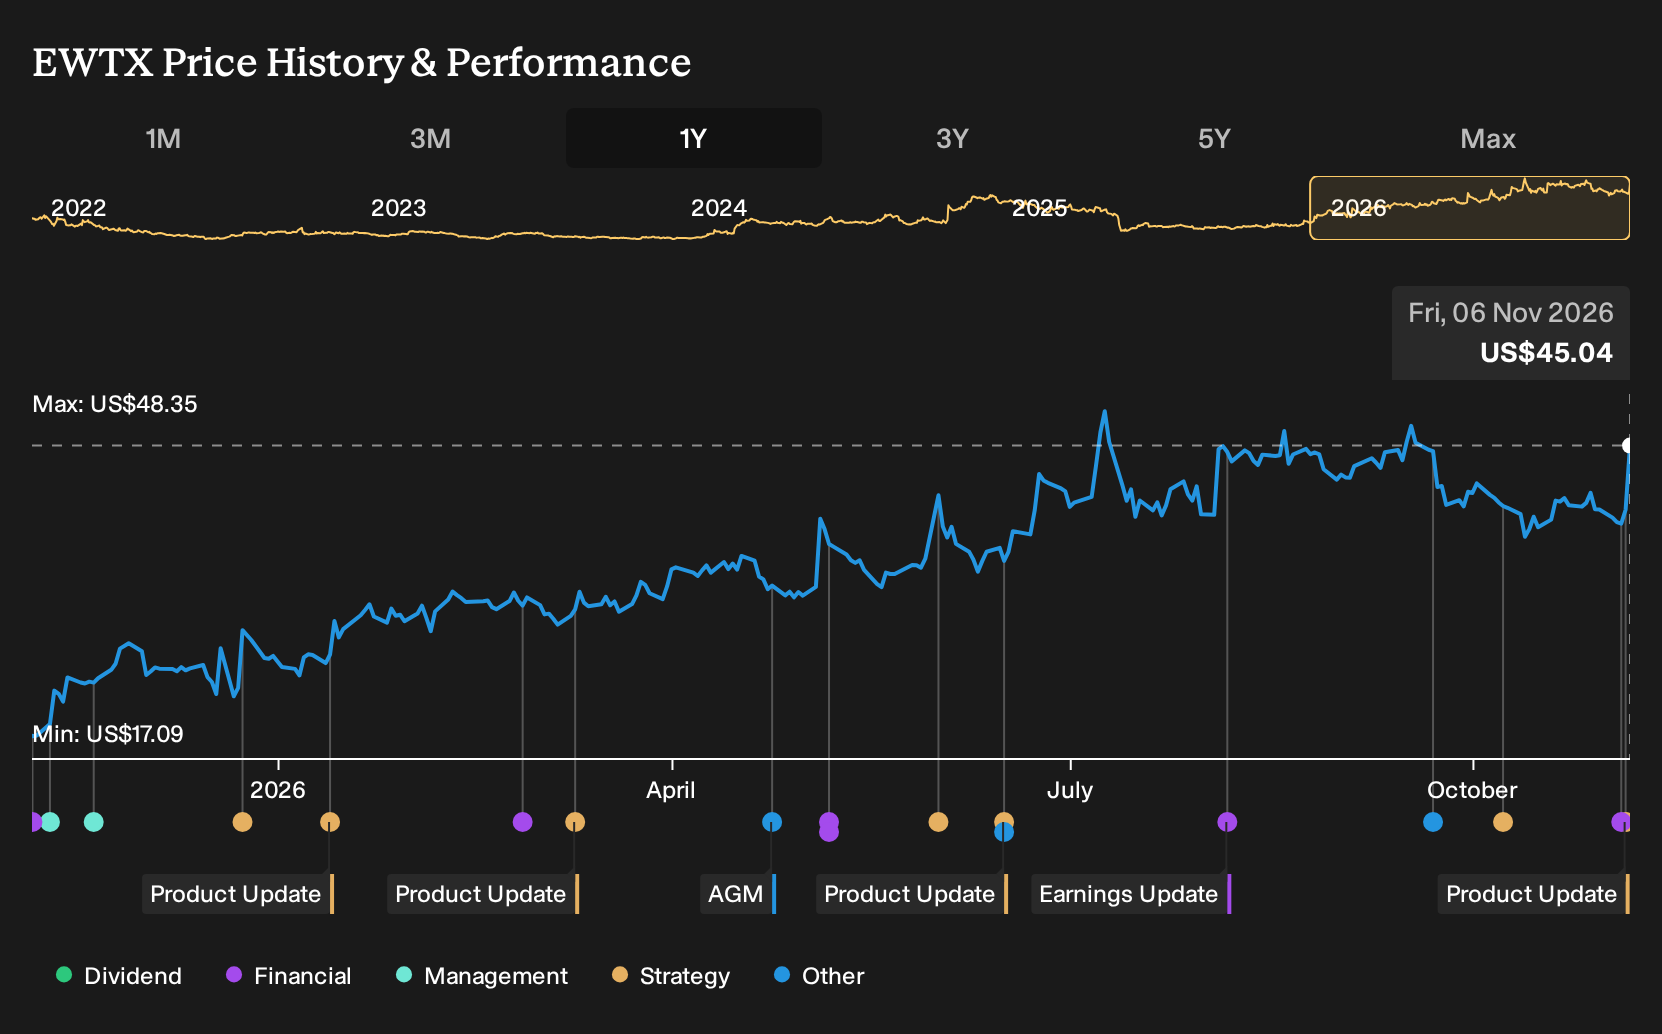
Discover why Edgewise Therapeutics' fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most bullish analysts see the echo independent Phase 3 plan for EDG-7500 as a potential accelerator, not just a cleaner trial. Before this FDA feedback, they were already modeling about US$378.5 million of revenue and US$63.3 million of earnings by 2029 for Edgewise Therapeutics. That is far above the consensus US$135.6 million and US$22.1 million view. Use this spread as your signal that opinions can differ sharply. Then explore both sets of assumptions and decide which story feels closer to how you see the news landing over time.
Explore another Edgewise Therapeutics fair value estimate, including one that suggests potential upside of up to 20% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Edgewise Therapeutics research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Edgewise Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edgewise Therapeutics' overall financial health at a glance.
Looking For More Edgewise Therapeutics Investment Ideas?
If the Edgewise Therapeutics story has sharpened your thinking about risk, timing and balance sheets, it can help to put that in context across a broader watchlist. Use the Simply Wall St Screener to stress test your approach against companies with different income profiles, capital structures and potential return drivers.
- Prefer financial resilience and lower volatility? Start with a 29 resilient stocks with low risk scores that can help you focus on businesses with sturdier profiles when conditions change.
- Hunting for quality at a sensible entry point? Filter for 39 high quality undervalued stocks and compare their fundamentals with what you see at Edgewise Therapeutics.
- Interested in tomorrow's potential leaders before they are widely followed? Scan a curated set of 19 high quality undiscovered gems and see which stories align with your thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com