


EN
Poundland Rescue Uncertainty Puts NEXT Stock And UK Retail Shares In Focus
A rescue deal for Poundland is hanging in the balance, and that uncertainty is rippling through UK high streets, landlords and listed retail stocks. When a chain with around 12,000 jobs and 600 stores is at risk, market perception can swing quickly. That disruption can punish some shares and open doors for others. This article unpacks three UK listed companies exposed to this news and explains why their stories now deserve a closer look.
The three stocks highlighted below are only a sample, with the full screen surfacing 14 more UK retail and commercial property companies with equally compelling narratives that are not covered here. To identify and analyze the highest conviction ideas from this broader list, head straight to the UK Retail & Commercial Real Estate Distress Opportunities screener.
NEXT (LSE:NXT)
Overview: NEXT plc is a UK headquartered retailer that sells clothing, homeware and beauty products through stores, online channels and franchise partners, while also providing branded credit and ecommerce services to third parties.
Operations: NEXT generates around £2.7b from UK online, £1.9b from retail stores, £1.4b from international online and about £1.6b from Total Platform, finance and other activities, after eliminations.
Market Cap: £17.7b
NEXT matters in this distress focused screen because a large, well financed multi channel retailer is often the one ready to pick up prime units, customers and partners that weaker competitors like Poundland might leave behind.
"NEXT is focusing on expanding their international business, particularly by leveraging aggregators and optimizing marketing strategies, and the recent 24% rise in international full-price online sales together with higher overseas marketing spend indicates further scope to lift online revenue and earnings."
What really moves the dial from here is how one unseen cost pressure interacts with that online momentum to shape future profitability.
If that hidden cost pressure is what really decides where returns go next, the full narrative for NEXT lays out how NEXT’s model could still keep earnings accelerating.

Card Factory (LSE:CARD)
Overview: Card Factory is a value-focused high-street retailer of greeting cards, gifts and celebration essentials, with growing online and wholesale channels supporting its position to benefit from distress among UK discount chains.
Operations: Card Factory generates around £512.8 million from Cardfactory stores, £49.4 million from wholesale partnerships and £33.4 million from digital, with most income earned in the United Kingdom.
Market Cap: £301.1 million
Card Factory matters in this distress themed screen because a value-led celebrations specialist with a dense UK store network is closely tied to high-street footfall, while also being well placed to take on customers and selected sites when weaker chains retreat.
"Expansion of Card Factory’s broader celebrations offer, with gifts and celebration essentials rising to over 55% of in-store sales in H1 FY27 and linked party-led baskets reaching around £25 per occasion in examples management gives, points to further scope for higher average basket values and a store revenue mix that is less dependent on greeting cards. U.K. like for like store sales for Card Factory fell 2.3% in H1 FY27 despite card market share holding steady, and if weaker high street footfall persists then store revenue could stay flat or decline, which would pressure group revenue and earnings even if basket values remain higher."
What really shapes how this plays out is whether one stubborn cost headwind quietly absorbs that extra basket value before it reaches profit.
If that cost is what really matters for Card Factory’s next chapter, the full narrative for Card Factory shows whether rising baskets are masking risk or accelerating upside.

Great Portland Estates (LSE:GPE)
Overview: Great Portland Estates is a FTSE 250 owner and developer of central London offices and retail-led mixed-use buildings.
Operations: Great Portland Estates earns about £75 million from the remainder of its portfolio and £44.5 million from fully managed offices, almost all in the UK.
Market Cap: £1.4b
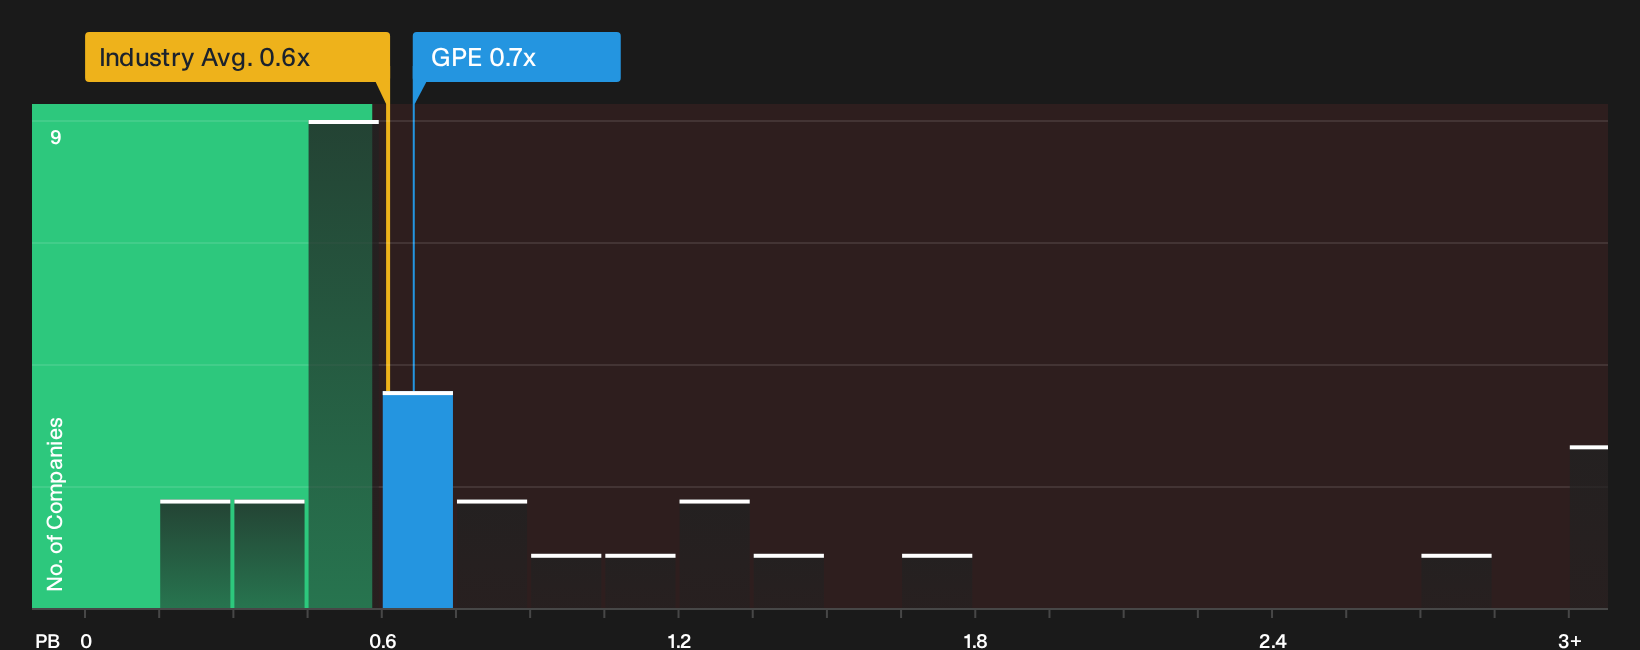
Great Portland Estates gives you direct exposure to central London commercial property, with potential implications if distressed retailers vacate prime space and different tenants occupy it. The stock trades on a P/E of 9.1x with revenue growth projected at 4.5% a year, so the real outcome depends on how funding-sensitive pressures influence future rent and yield dynamics.
Those funding sensitive pressures are already baked into valuations, so see the 4 key rewards and 2 important warning signs (1 is major!) to understand how income potential compares with that risk.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Prices can break out or drop before most investors even glance at the data. Use these curated shortlists while the information still really matters, and get in early.
- Chase resilient compounding potential by scanning the 4 resilient stocks with low risk scores that aim to keep downside contained while momentum builds quietly under the radar for now.
- Hunt for income that can keep working by checking the 4 dividend fortresses focused on higher yielding payouts while prices have not fully caught up.
- Target growth at the bleeding edge by reviewing the 52 AI infrastructure stocks supporting the computing backbone behind many of today’s fastest moving opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com