


EN
DorianG (LPG) Could Be 15% Undervalued After Earnings Surge And Irregular Dividend
DorianG earnings surge and irregular dividend
DorianG (LPG) has just posted a sharp jump in quarterly earnings, supported by favorable freight conditions and high time charter rates. The company also declared an irregular dividend that returns extra cash to shareholders.
DorianG’s share price has pulled back, with a 7 day share price return of about 14% and a 30 day return of about 17%, in spite of a 90 day gain of 1.7% and an 88.1% year to date rise. This indicates that short term momentum is fading while the longer term trend remains strong.
Scan how DorianG’s surge and irregular dividend compare to other shipping and energy plays by reviewing the hand picked 39 high quality undervalued stocks that currently screen as high quality with support from cash flows and balance sheets.
DorianG now trades at a clear discount to analyst targets after a sharp pullback and a strong earnings report. Is that a mispricing of cash generation, or simple market caution about how long these conditions last?
Most Popular Narrative: 14.7% Undervalued
Against a last close of $46.55, the most followed DorianG narrative anchors fair value at $54.60, which points to a material valuation gap built on detailed volume, fleet, and earnings assumptions.
Ongoing growth in global LPG liftings with U.S. exports near 20.8 million tons per quarter and supplying about 65% of seaborne LPG is shifting trade flows toward long haul routes that can support DorianG revenue and TCEs.
The closure of the Strait of Hormuz, which reduced Middle East LPG liftings to roughly 3.4 million tons, is forcing key importers to source more cargo from the U.S. Gulf, increasing ton mile demand that feeds into DorianG freight revenue and earnings.
See why 45 investors see DorianG as 15% undervalued.
Result: Fair Value of $54.60 (UNDERVALUED)
Still, the story around DorianG can unravel quickly if the 124 ship VLGC orderbook pushes freight rates lower or Panama Canal costs keep eroding TCEs.
Find out about the key risks to this DorianG narrative.
Another View: DorianG through a cash flow lens
The headline narrative frames DorianG as undervalued versus fair value of $54.60, yet the Simply Wall St DCF model paints a very different picture. On that cash flow view, the stock around $46.55 sits well above an estimated value of $26.78, which points to valuation risk if freight conditions cool or cash returns ease.
Anyone comparing these two signals needs to understand how the SWS DCF model treats shipping cycles, one off gains, and shrinking earnings forecasts before leaning on it as an anchor for DorianG. Look into how the SWS DCF model arrives at its fair value.
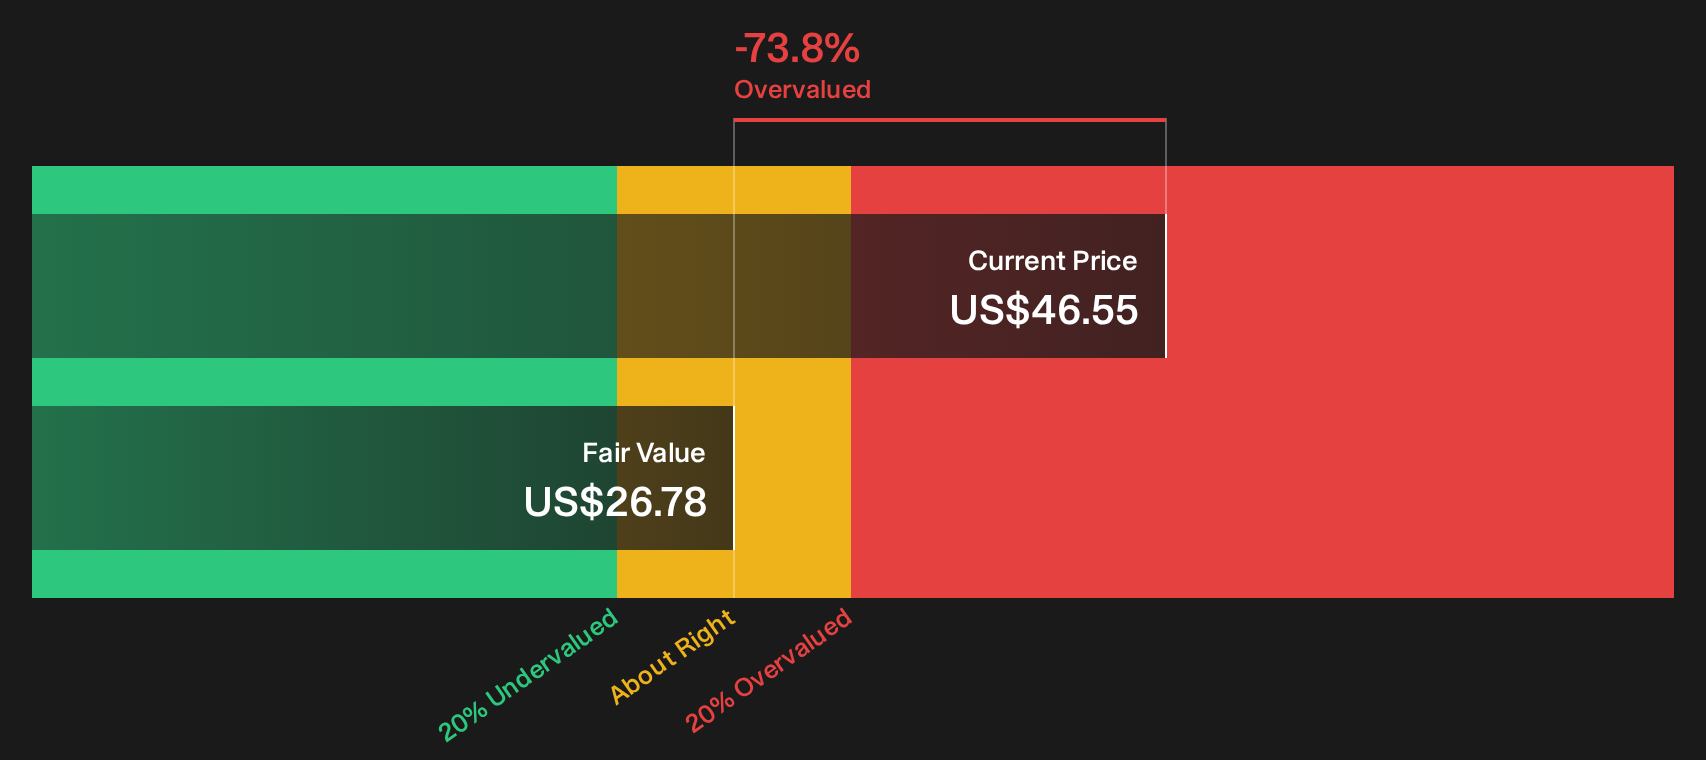
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DorianG for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around DorianG can be confusing, so consider acting promptly, reviewing the data in depth, and weighing both the upside and the downside using 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond DorianG?
If DorianG has your attention, do not stop here. Broaden your watchlist now so you are not chasing opportunities after they have already moved.
- Target resilient balance sheets first and let the list of solid balance sheet and fundamentals (24 results) guide you toward companies backed by stronger fundamentals and financial buffers.
- Hunt for potential mispricings by scanning the 19 high quality undiscovered gems. It combines quality metrics with limited market attention.
- Prioritise smoother ride potential and use the 29 resilient stocks with low risk scores to focus on businesses with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com