


EN
What Superior Plus Holders Got Wrong Before The Slide
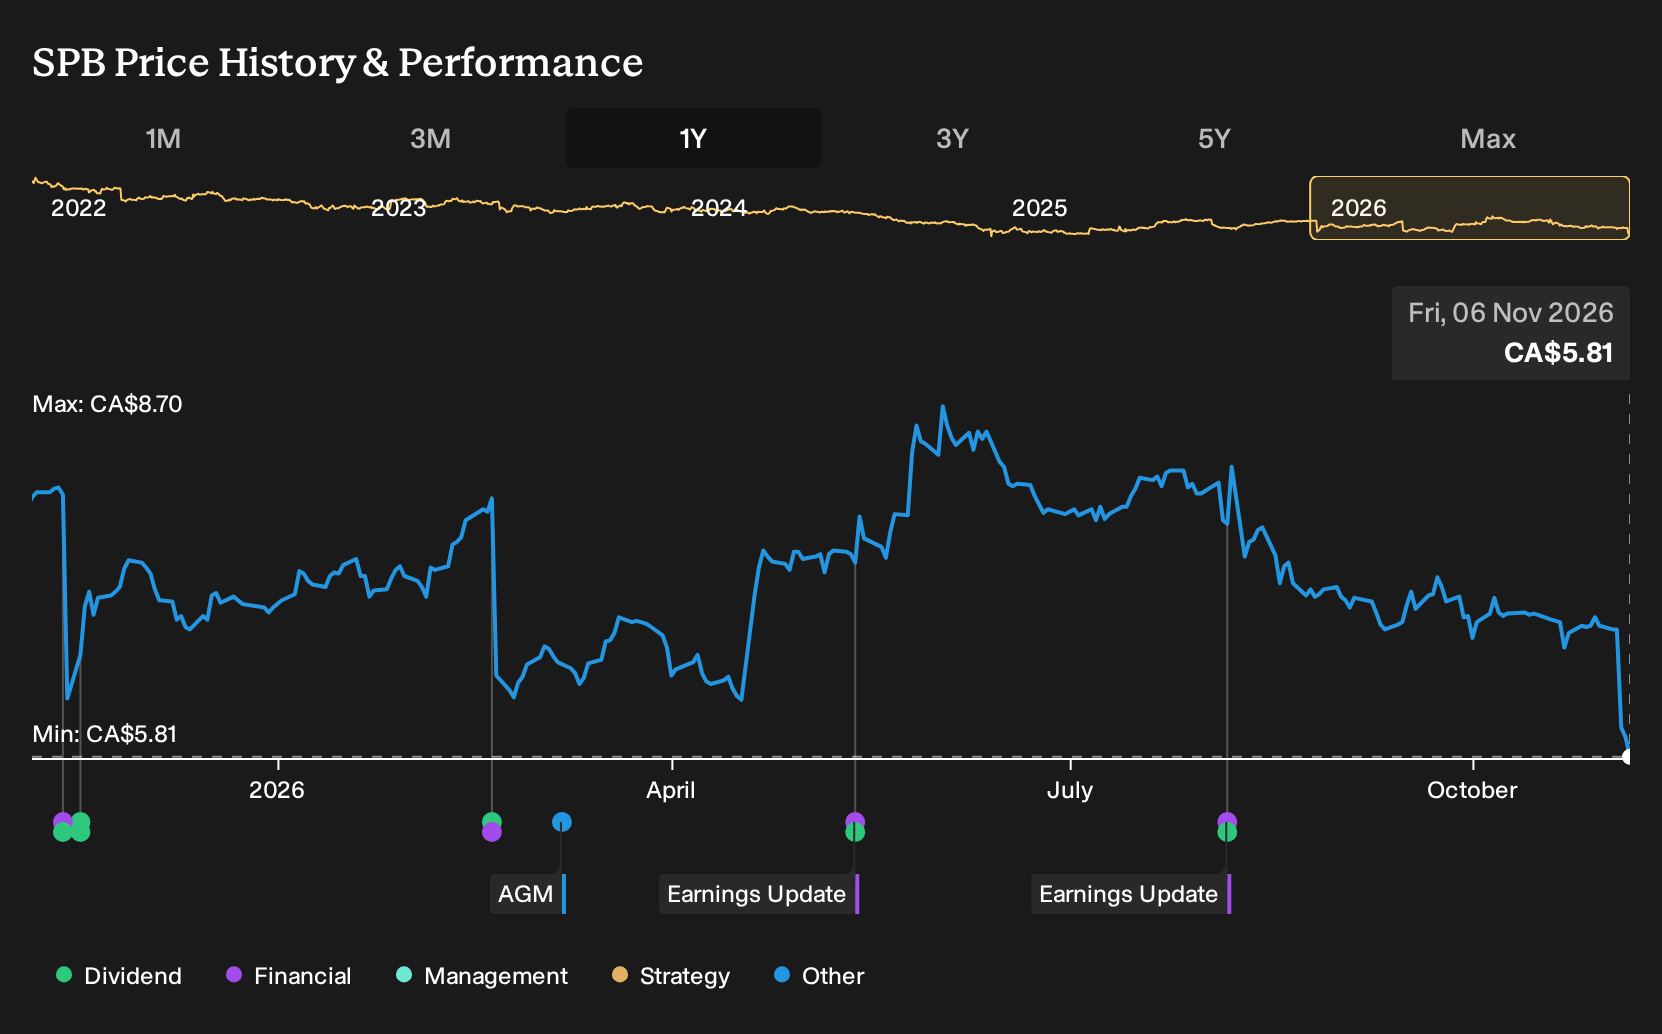
If you backed Superior Plus a year ago on the promise of operational transformation and clean energy growth, the payout has been rough. Investors who held Superior Plus over the past year are down 25.4%, including dividends. If you made that decision expecting 3.8% annual revenue growth, profit margins lifting to 5.3% and a future P/E of 14.4x within three years, which of those assumptions failed to account for what actually unfolded?
Superior Plus is not the only name tied to this theme. Zero in on 42 power grid technology and infrastructure stocks and compare how each one is priced.
The Argument You Would Have Been Weighing On Superior Plus
The shares cost CA$7.95 at the start of the period, and you were really choosing between two stories about where Superior Plus might go next.
The bullish script pointed to operational change and cleaner fuels, with a Fair Value of CA$9.62. This was effectively the price implied if 3.8% annual revenue growth, a 5.3% profit margin and a 14.4x future P/E all played out.
The more cautious view saw electrification and regulation steadily chipping away at propane demand, with a Fair Value of CA$7.5 and concern that long term erosion in the core fossil fuel market would pressure both volumes and margins.
What The Evidence Did To The Superior Plus Argument
The biggest development was Superior Plus leaning harder into Certarus, with multi year data center fuel contracts above US$300 million and a Q2 2026 CNG fleet fueling launch that targets new logistics demand. That supports the cleaner fuels and operational change narrative. The challenge, however, is profitability. Revenue in Q2 2026 reached US$435.4 million, while the business reported a larger loss and net margin moved deeper into negative territory.
The lesson is simple: when an investment thesis leans on margin expansion, it is important to track the reported net margin and profit in each set of results, not just the new growth projects that management highlights.
What The Fall In Superior Plus Is Asking You To Believe Now
Superior Plus trades at CA$5.81 today, well below where you started a year ago. The selected Narrative’s Fair Value sits above the current price and rests on contracted CNG and data center volumes, as well as the Superior Delivers program lifting earnings power over time.
For the recent fall to look like an opportunity rather than a warning, a buyer now would need to believe Certarus can convert those long duration contracts and higher growth capex into durable cash generation that comfortably supports a higher leverage profile.
"The shift in Certarus toward industrial and data center customers, supported by six signed data center contracts totaling more than $350 million in revenue and an expectation that these customers will reach about 60% of CNG volumes within 24 months, is set to increase contracted revenue visibility and could support more stable EBITDA and cash generation."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 41% below our estimate - uses lean inventory, rapid reorder and flexible open to buy to follow real-time demand.
- Company 2 - 36% below our estimate - adds AVL capacity, technicians and new facilities to capture larger power and equipment projects.
- Company 3 - 29% below our estimate - opens new boutiques and builds digital channels to deepen apparel reach with existing customers.
Those are three of them. See all 6 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com