


EN
Toast (TOST) Posts Strong Q3 Growth, Is A 25% Discount Still In Play?
Toast (TOST) just put fresh numbers on the board with third quarter revenue of US$1.98b and net income of US$169m, giving investors a clearer read on how the restaurant tech specialist is executing.
Toast shares have climbed over the past month, with a 30 day share price return of 13.56% and a 7 day gain of 9.44%. However, the 1 year total shareholder return has declined 6.3%, so near term momentum is building even as longer term holders still sit on mixed results.
Capitalize on Toast's momentum and benchmark it against a curated group of restaurant tech players and other high quality platforms in our 19 high quality undiscovered gems.Toast now trades near US$34.67 after that earnings spike, which leaves a simple decision in front of you. Does the current price still reflect a favourable risk reward or has the easy upside already been used up?
Most Popular Narrative: 25% Undervalued
Against the latest close at $34.67, the most followed narrative on Toast pegs fair value at $46.44, pointing to a clear valuation gap for investors to weigh.
A cloud-based vertical ecosystem built specifically for the restaurant and hospitality sector. Unifies POS hardware/software, supply chain management, integrated payments, marketing, and kitchen management. Has successfully pivoted from heavy growth investments toward accelerated net profitability.
See why 6 investors see Toast as 25% undervalued.
According to PDSOUSA, that view uses a discount rate of 7.28% and a profit margin assumption of 7.14%, then compares the implied $46.44 value to the current share price. The same narrative also highlights that this framework sees Toast trading at a 25.3% discount to its assessed worth.
Those inputs sit alongside a backdrop of annual revenue growth of 15.82% and net income growth of 22.31%, plus a reported return on equity of 24% and net profit margin of 7.7%. On this reading, the market price asks you to judge whether a business with high forecast earnings growth and an equity return above 20% should trade meaningfully below an internally consistent cash flow value.
Result: Fair Value of $46.44 (UNDERVALUED)
Still, the Toast narrative depends on restaurant clients sticking with its ecosystem, and on current P/E and P/B multiples not compressing if sector sentiment cools.
Find out about the key risks to this Toast narrative.
Another View On Toast Using Market Ratios
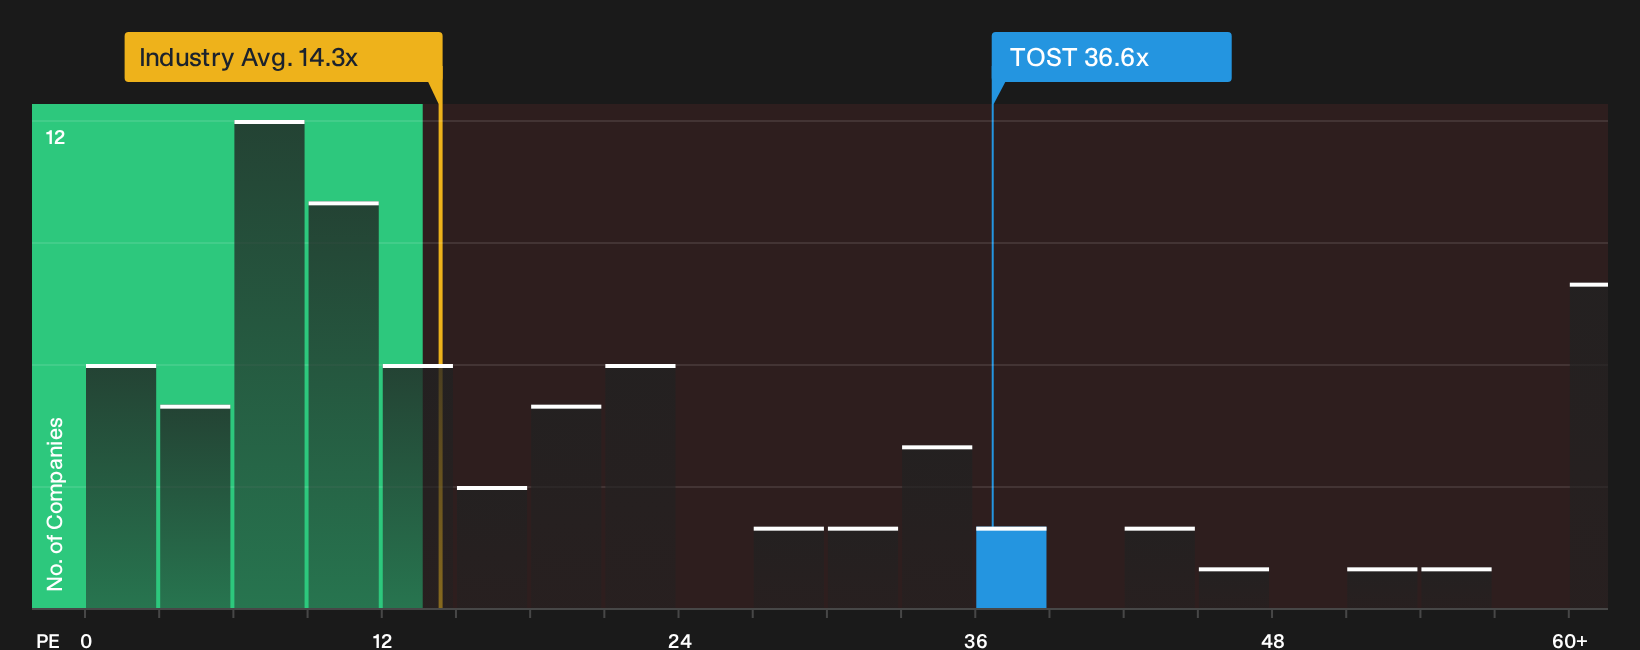
That cash flow based fair value of $46.44 paints Toast as undervalued, but the market ratio lens is less forgiving. The current P/E of 36.6x sits far above the US Diversified Financial industry at 14.3x and the peer group at 23.9x, while the fair ratio points to 18.6x as a level the multiple could drift toward. For anyone weighing an entry or adding to a position, the question is whether paying more than double the industry P/E leaves enough room for error.
See what the numbers say about this price in our valuation breakdown, and how that P/E gap shapes the risk reward around Toast today See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mix of enthusiasm and caution in Toast's story feels familiar, that is the point. Use the full data set, stress test the assumptions, and see what investors are most optimistic about in the 3 key rewards.
Looking For More Ideas Beyond Toast?
If Toast has sharpened your thinking, do not stop here. Broader opportunity lives in the wider market, and skipping it could mean missing your next strong performer.
- Target quality at a discount by zeroing in on companies screened for stronger fundamentals through the 39 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses filtered for healthier finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Pursue dependable income by reviewing candidates with higher yields and steadier payouts through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com