


EN
How Investors Are Reacting To Helmerich & Payne Stock As Earnings Beat Hopes Build
- Helmerich & Payne recently featured in analyst commentary with an Earnings ESP of +25.14% and a Zacks Rank #3, which points to expectations for an earnings outcome that could differ from current consensus.
- The key detail for investors is that this positive Earnings ESP interacts directly with Helmerich & Payne’s contract quality, automation tools and capital discipline, because any earnings surprise will be weighed against how efficiently those core operations are converting rig activity into margins and cash.
- Now the focus turns to how Helmerich & Payne’s existing investment narrative could shift if the strong Earnings ESP does translate into an earnings beat.
See how Helmerich & Payne’s earnings setup compares with other contract driven operators by checking our curated list of list of solid balance sheet and fundamentals (24 results)
Helmerich & Payne Investment Narrative Recap
To own Helmerich & Payne, you need to believe the rig fleet, automation tools and international contracts can turn into steadier margins and sustainable free cash flow over time. In the near term, the story hinges on how effectively management keeps high spec rigs contracted while drilling efficiency rises and rig counts remain under pressure in key basins.
The biggest swing factor right now is short term earnings delivery against that backdrop. The positive Earnings ESP hints at upside risk to the next print, although the signal alone does not change the core thesis. The key operational risk remains overcapacity and potential pricing pressure, especially if customers trim activity or push harder on dayrates.
With no fresh company specific announcements tied directly to this Earnings ESP, the most relevant reference point is still management’s stated push into digital drilling tools such as AutoSlide and FlexRobotics. These systems are central to the argument that Helmerich & Payne can justify differentiated pricing and better direct margins even if overall rig demand is choppy.
For you as a shareholder, the link between that technology rollout and upcoming earnings is important. Stronger adoption and documented well performance, including prior results in Vaca Muerta and other international programs, provide a tangible operational path to offset periods of softer utilization. Execution against that plan will matter more than any single earnings surprise signal.
Helmerich & Payne’s narrative projects US$4.3b revenue and US$410.2 million earnings by 2029. This implies 2.8% yearly revenue growth and an earnings increase of about US$548.9 million from a loss of US$138.7 million at present.
Uncover why Helmerich & Payne's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
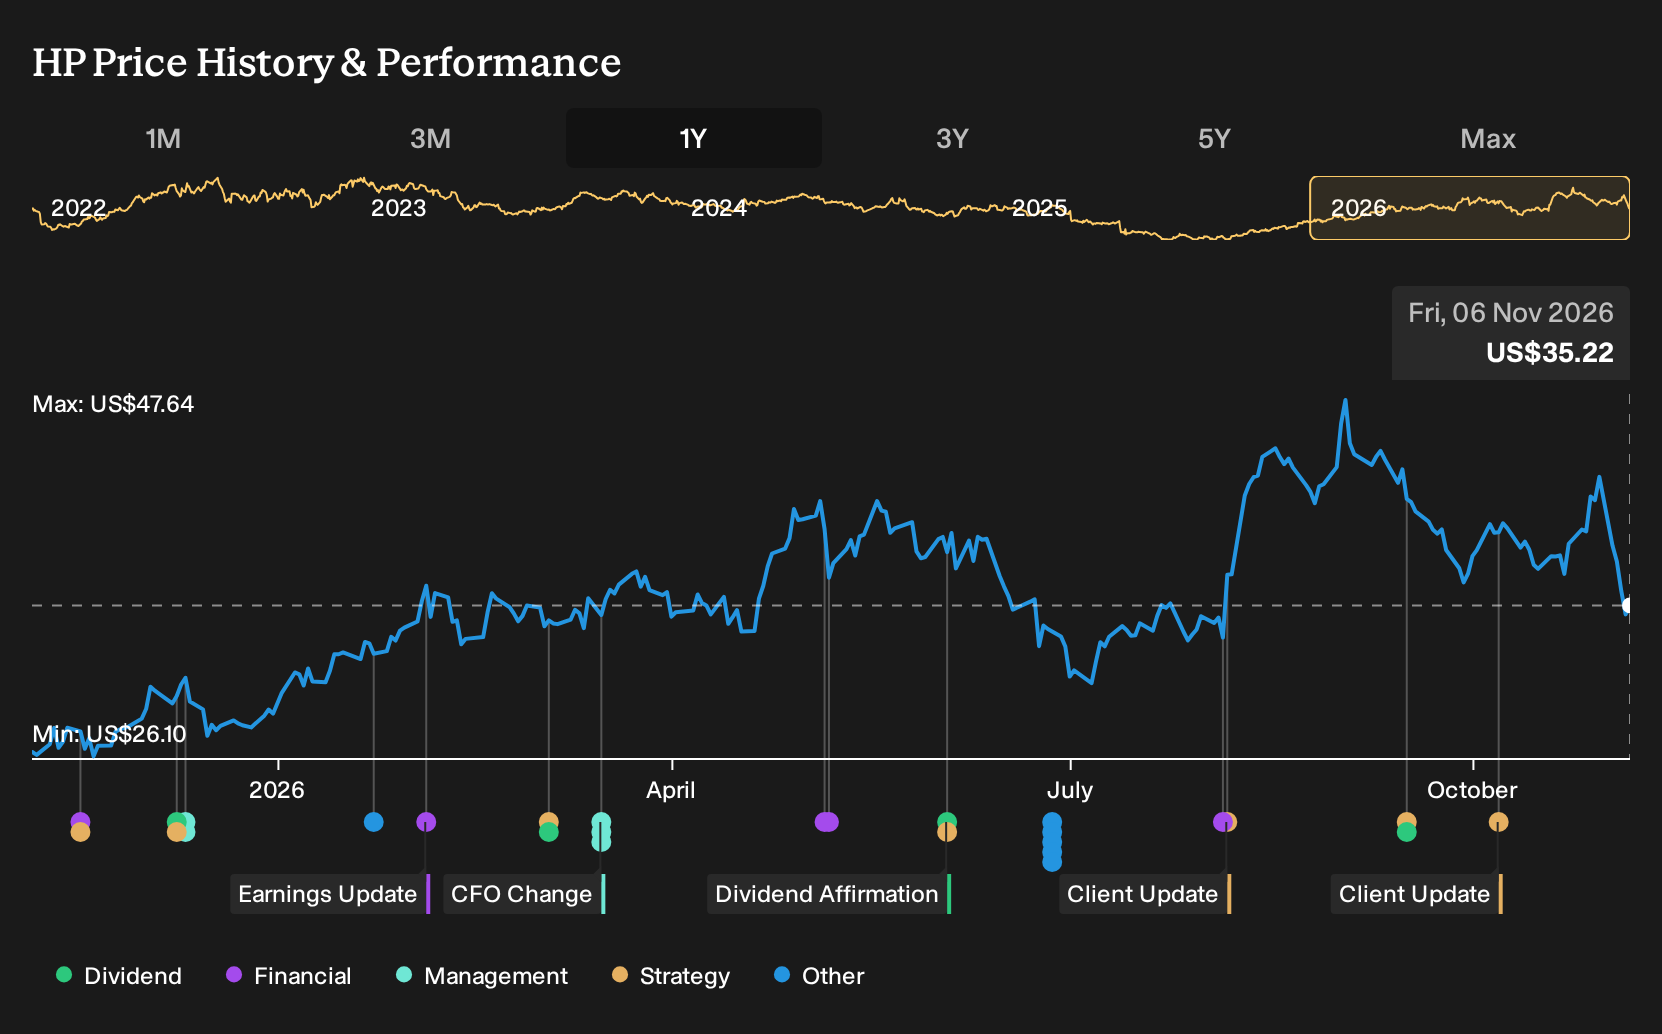
Exploring Other Perspectives
Some of the most bullish analysts frame Helmerich & Payne’s geothermal expansion as the real swing factor. You see forecasts that stretch to about US$4.3b of revenue and US$564.6 million in earnings by 2029, compared with the bearish end closer to US$351.7 million, and none of those views include the latest Earnings ESP yet.
Explore 3 other Helmerich & Payne fair value estimates, including one that suggests as much as 141% above the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Helmerich & Payne research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Helmerich & Payne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Helmerich & Payne's overall financial health at a glance.
Looking for more investment ideas beyond Helmerich & Payne?
Once you have a view on Helmerich & Payne, it can help to widen the lens and compare it with other businesses that match your risk tolerance and income goals. The Simply Wall St Screener is built for that kind of side by side work, so you can quickly spot companies that align with your own checklist rather than someone else’s hot tip.
- If you want potential upside with tighter downside risk, start with a group of companies that score well on stability and financial strength using the 29 resilient stocks with low risk scores.
- For investors who care about buying quality at a measured price, check out a hand picked pool of 39 high quality undervalued stocks that combine solid balance sheets with strong fundamentals.
- If you are hunting for ideas the crowd might be overlooking, scan through a curated set of 19 high quality undiscovered gems that could warrant a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com