


EN
Why Graco (GGG) Is Getting Fresh Attention
Why Graco’s New QUANTM Pump Matters For Investors
Graco (GGG) has put fresh attention on its industrial toolkit with the launch of the 3-inch QUANTM i230 electric double-diaphragm pump, a product aimed at higher throughput and lower energy use.
Graco’s new QUANTM launch and the recent positive analyst commentary arrive after a tougher stretch for the ticker, with the share price down 12.4% over the past month and 18.8% over 90 days, while the 1-year total shareholder return has declined 15.7%. This points to fading momentum despite product and sentiment tailwinds.
Scan beyond Graco and line up other industrial manufacturers pushing efficiency and automation gains with the hand picked 90 robotics and automation stocks.
Graco now trades at a clear discount to both analyst targets and one intrinsic estimate, despite new products and upbeat commentary. Is that a genuine mispricing, or is the market flagging real risks?
Most Popular Narrative: 19% Undervalued
Graco closed at $67.86 while the most followed narrative pegs fair value near $83.29, so the gap between price and that estimate is wide enough that the story behind it really matters.
The main factor that must go right is continued execution on disciplined M&A and integration, so acquired businesses such as COROB, Color Service, Radia and Valco Melton contribute meaningfully alongside organic semiconductor and infrastructure demand.
Efforts to mitigate tariff impacts by qualifying additional suppliers and using targeted price increases, which have already offset millions of dollars of tariff costs while 2Q26 gross margin rose 130 basis points, point to a continuing ability to protect net margins.
See why 12 investors see Graco as 19% undervalued.
Result: Fair Value of $83.29 (UNDERVALUED)
Still, Graco’s story can break if tariff costs outrun pricing power, or if housing exposed Contractor demand weakens further and drags on orders.
Find out about the key risks to this Graco narrative.
Another View: What Graco’s P/E Is Really Telling You
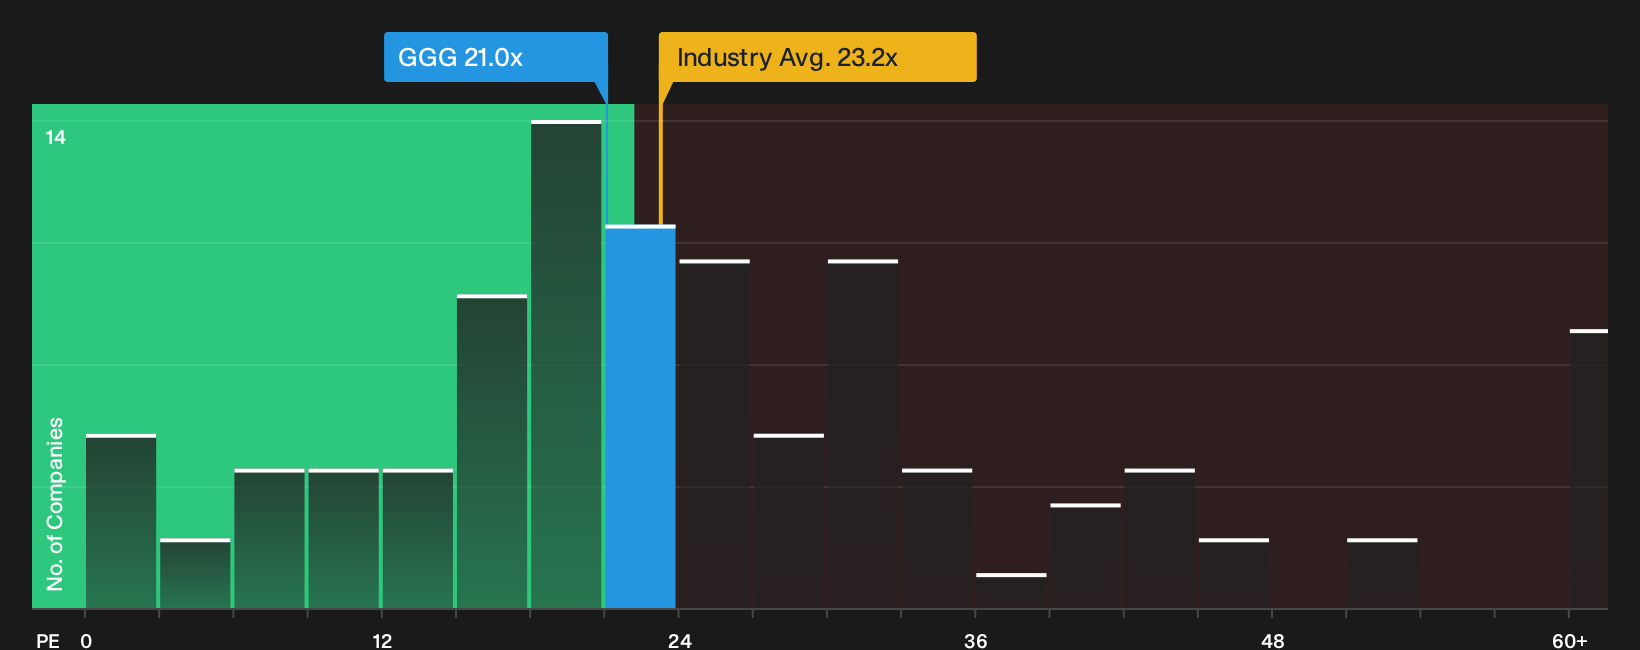
The discounted cash flow work points to undervaluation, but the simple P/E picture is less generous. Graco trades around 21x earnings, slightly above a fair ratio of 20.4x, yet below the US Machinery peer average of 23.1x and a wider group on 26.4x. That mix hints at some valuation cushion, but also real downside risk if growth underwhelms.
If you want to see how those earnings multiples stack up line by line, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed sentiment around Graco has you on the fence, move quickly to test the numbers and pressure check the upside yourself with the 5 key rewards.
Looking For More Investment Ideas Beyond Graco?
If Graco has sharpened your focus on quality, do not stop here. The best opportunities often sit just outside your current watchlist.
- Spot potential mispricing early by scanning a curated 39 high quality undervalued stocks before the crowd pays attention.
- Strengthen the defensive side of your portfolio by working through a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- Hunt for future leaders by reviewing a 19 high quality undiscovered gems that most investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com