


EN
Is Warrior Met Coal (HCC) Undervalued After Strong Q3 Results And A $2 Dividend?
Warrior Met Coal (HCC) just delivered third quarter results that featured higher revenue and net income, a new $2.00 special dividend, reaffirmed 2026 guidance, and a stronger contribution from the Blue Creek ramp-up.
The share price has climbed 4.15% over the past day to $84.15 after Warrior Met Coal confirmed stronger third quarter figures. However, the 30 day share price return is down 6.05% and the 90 day move is lower by 8.50%, even as total shareholder return over five years is up more than 3x, suggesting that recent weakness comes against a much stronger long term record.
Capitalize on Warrior Met Coal’s momentum shift and compare it with other materials players by scanning our hand-picked 29 resilient stocks with low risk scores that prioritize resilient balance sheets and durable fundamentals.For Warrior Met Coal, a 4% one day bounce after a softer few months raises a simple tension. Is the price now tracking the stronger recent results, or is it reflecting a mood swing in sentiment that leaves the valuation misaligned?
Most Popular Narrative: 23% Undervalued
Against the last close at $84.15, the most followed narrative pegs Warrior Met Coal’s fair value at $109.33 using an 8.9% discount rate, which frames the recent pullback as a possible gap between price and long range cash generation.
The ahead-of-schedule and on-budget launch of the Blue Creek longwall in early Q1 2026 accelerates Warrior Met Coal's transition from capital investment to higher-volume revenue generation. Q2 2026 record sales volumes of 3.7 million short tons and a 45% increase in production indicate further potential impact on revenue and net margins as low-cost volumes continue to ramp.
See why 36 investors see Warrior Met Coal as 23% undervalued.
Result: Fair Value of $109.33 (UNDERVALUED)
Still, the story can break if weakness in global steel demand keeps pressure on metallurgical coal pricing, or if rising freight costs further squeeze Warrior Met Coal’s margins.
Find out about the key risks to this Warrior Met Coal narrative.
Another View: Warrior Met Coal Through The P/E Lens
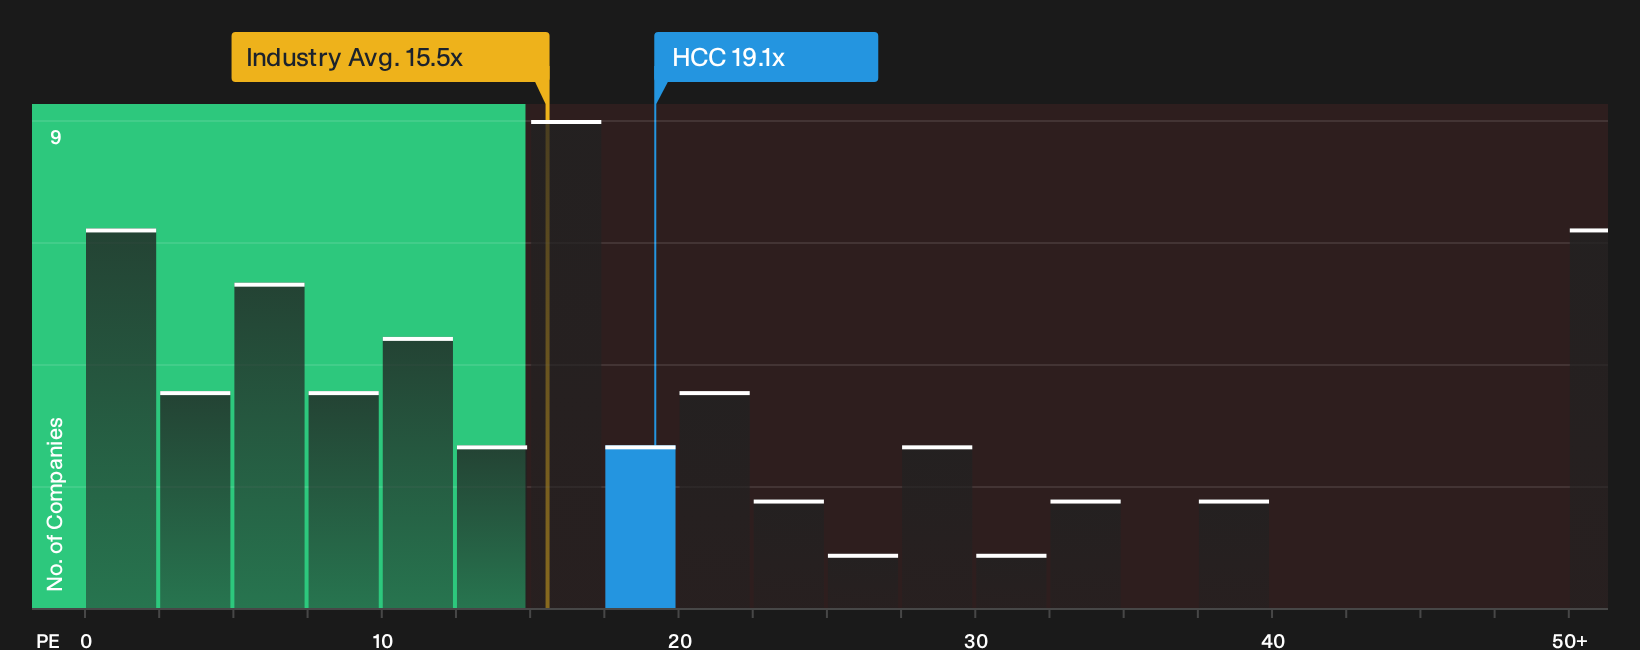
Zoom in on the plain P/E ratio and the story shifts. Warrior Met Coal trades at 19.1x earnings compared with 15.5x for the wider US Metals and Mining group. That is richer than the sector, even though the stock only roughly matches its own 19.2x fair ratio estimate.
This mix of slightly above sector pricing but roughly in line with the fair ratio points to limited margin for error rather than a clear bargain. If earnings or sentiment wobble, how comfortable are you owning Warrior Met Coal at a premium valuation?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Warrior Met Coal's valuation can make the story feel pulled in two directions, so pull up the data yourself, weigh the upside against the downside, and decide where you land after looking through the 3 key rewards and 1 important warning sign.
Looking for more Warrior Met Coal style investment ideas?
If Warrior Met Coal has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh, data driven opportunities before others move first.
- Target potential value opportunities by scanning our hand picked 39 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect them.
- Strengthen your income playbook by reviewing the 8 dividend fortresses that focus on higher yielding payouts with an eye on sustainability.
- Prioritise financial resilience by filtering for a list of solid balance sheet and fundamentals (24 results) so you concentrate on businesses with sturdier balance sheets backing their cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com