


EN
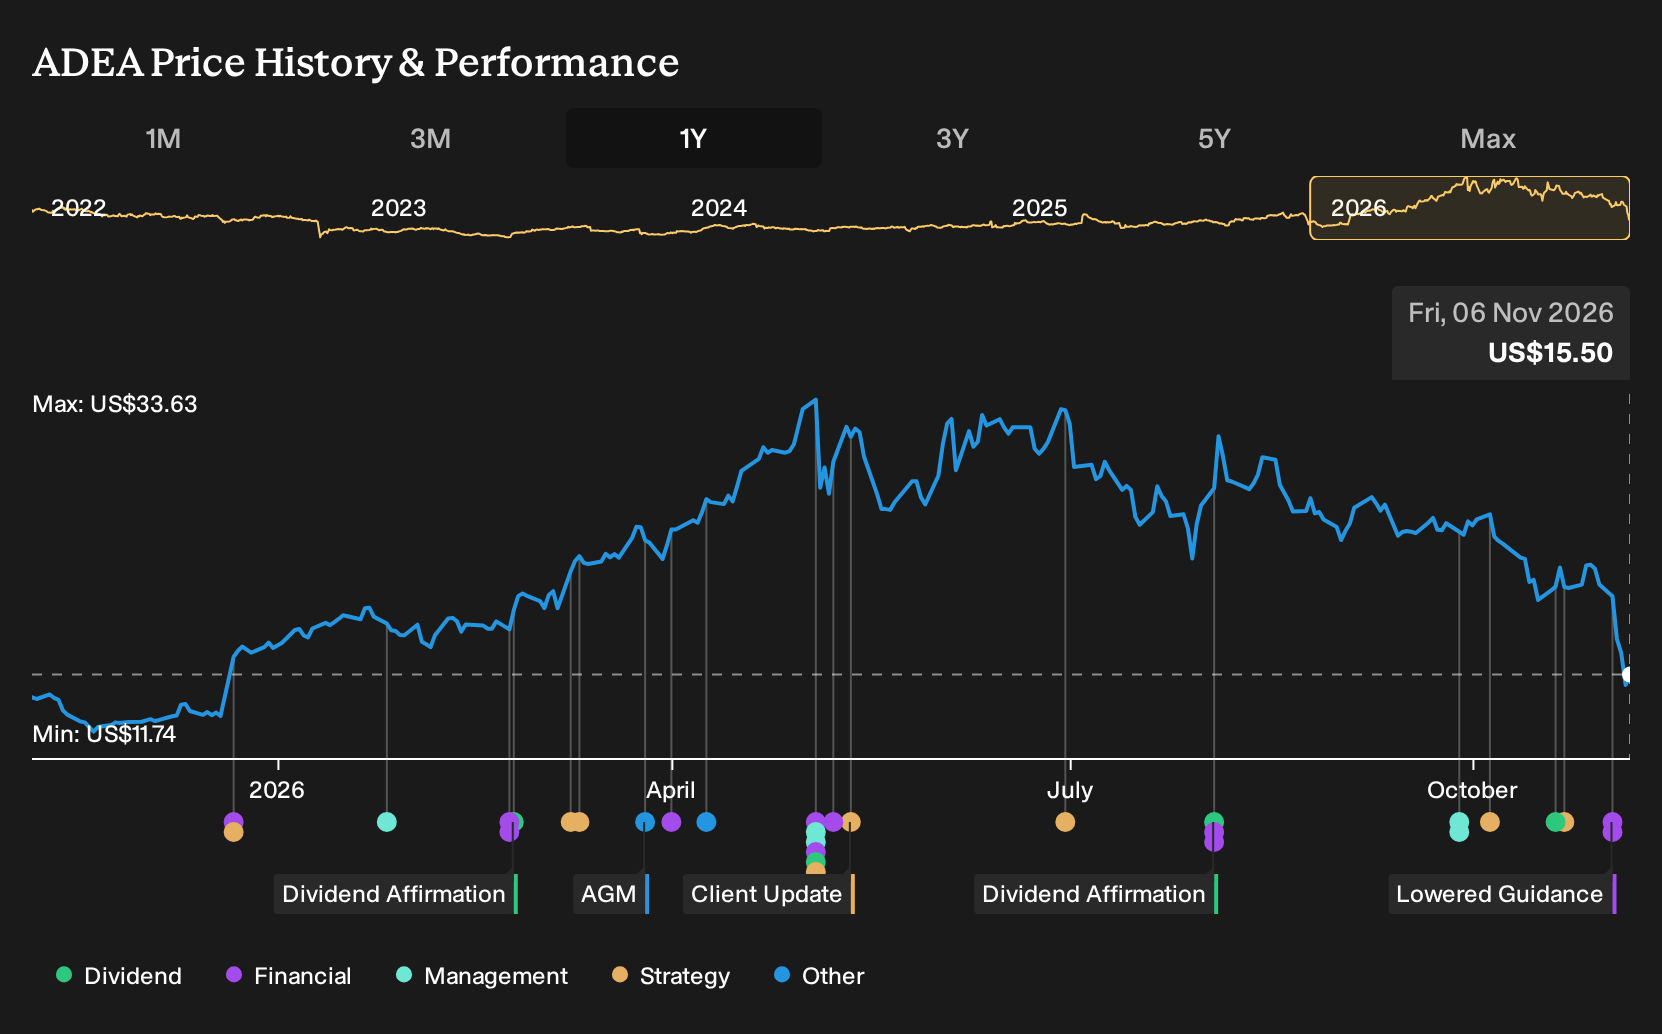
Is Lowered Guidance Altering The Investment Case For Adeia (ADEA)?
- Adeia cut its full year 2026 guidance after a weaker third quarter, now projecting GAAP revenue of US$375.0 million to US$415.0 million and net income of US$52.8 million to US$79.2 million, alongside quarterly sales of US$80.19 million and net income of US$2.27 million.
- Despite the softer quarter, Adeia's nine month figures show sales of US$281.08 million and net income of US$42.41 million, which highlights that the licensing model can still generate earnings even when a single period comes under pressure.
- We will now examine how Adeia's reduced full year guidance could reshape the broader investment narrative built around its licensing engine.
Scan beyond Adeia and stress test your thesis against 39 high quality undervalued stocks, which combine resilient balance sheets with earnings power investors may be overlooking after guidance cuts or softer quarters like this one.
Adeia Investment Narrative Recap
Adeia is still an intellectual property story at its core. To hold the stock, you need to believe management can keep turning a large patent portfolio into recurring licences across media and semiconductors while absorbing higher legal spend and customer concentration. The lowered 2026 outlook points to lumpier near term deal timing rather than a structural break in the licensing model.
The key near term swing factor now is execution on upcoming renewals and semiconductor agreements that can refill earnings after a soft third quarter. The biggest risk remains prolonged disputes or slower signings with a handful of large counterparties, which could keep revenue and litigation costs out of sync for longer.
The most relevant update is the third quarter and nine month earnings release on 2 November 2026. Sales in the period were US$80.19 million with net income of US$2.27 million, while year to date figures reached US$281.08 million of sales and US$42.41 million of profit. Those numbers frame how much room Adeia has to absorb higher legal expense and still produce cash.
That earnings print, combined with the guidance cut, now ties directly into the main catalysts. Progress in OTT and semiconductor licensing, plus the ability to convert litigation into settlements on acceptable terms, will influence how quickly earnings per share recover from the weaker quarter. Analyst commentary around valuation can move sentiment, but the operational test is still licence renewals, deal timing and cost discipline.
Adeia's narrative projects US$454.7 million of revenue and US$78.6 million of earnings by 2029. This implies fairly flat top line performance and an earnings decrease of about US$37.5 million from US$116.1 million today.
Uncover why Adeia's fair value indicates a 147% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Adeia, the most optimistic analysts were focused on a catalyst that now looks very contested. They were assuming revenue of US$477.0 million and earnings of US$111.5 million by 2029, with a P/E of 65.4x. Those forecasts came before the guidance cut, so treat them as one side of a wide debate, not a settled path.
Explore 4 other Adeia fair value estimates, including one that suggests up to 223% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Adeia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adeia's overall financial health at a glance.
Looking for more investment ideas beyond Adeia?
Adeia may be central to your thesis today, but your portfolio benefits when you line it up against other opportunities with different balance sheets, cash flow profiles, and risk levels. Use the Simply Wall St Screener to pressure test your thinking across a wider field of stocks.
- For investors who prize income resilience, scan for companies that look like potential 8 dividend fortresses and see how their payouts compare to Adeia's total return profile.
- If capital preservation ranks high on your list, stress test your risk tolerance against a 29 resilient stocks with low risk scores and weigh those businesses against Adeia's licensing and litigation exposure.
- When you want to spot less crowded opportunities, broaden your watchlist with a 19 high quality undiscovered gems and see which fundamentals appeal more than Adeia's narrative.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com