


EN
How Strong Quarterly Earnings At JLL Have Changed Its Investment Story
- Jones Lang LaSalle reported third quarter 2026 sales of US$7,281.2 million and net income of US$319.8 million, with nine month net income of US$694.4 million, alongside the election of Nabeel Al Amudi and Toni Townes Whitley as independent non executive directors effective December 1, 2026.
- The combination of higher reported earnings per share and fresh board expertise in technology, infrastructure and regulated industries gives Jones Lang LaSalle added capacity to address real estate, data center and public sector mandates across cycles.
- Attention now turns to how Jones Lang LaSalle's investment narrative could be influenced by this quarterly earnings performance and expanded board expertise.
Scan how Jones Lang LaSalle's latest earnings strength and board refresh compare with other potential opportunities by reviewing the hand picked 19 high quality undiscovered gems in similar and adjacent sectors.
Jones Lang LaSalle Investment Narrative Recap
To own Jones Lang LaSalle, you need to be comfortable with a real estate services group that still leans on capital markets and leasing while working to deepen recurring workplace, project management and data center income. The latest quarter shows higher sales, earnings and EPS, which supports that mix shift but does not remove the cyclicality in transactions.
The key near term swing factor remains deal activity in capital markets and office leasing, which can quickly change if macro conditions or sentiment soften. The biggest risk is still prolonged weakness in office demand and contract churn in property management, and this board and earnings news does not fundamentally change that exposure.
The most relevant update here is the third quarter 2026 earnings report, with sales of US$7,281.2 million and net income of US$319.8 million, and nine month net income of US$694.4 million. Higher reported basic and diluted EPS from continuing operations provide fresher data on how effectively Jones Lang LaSalle is converting its platform and AI investment into profits.
For potential catalysts, that earnings print sits beside the ongoing build out of workplace, project management and data center mandates that analysts already flag as important. The risk side of the ledger still hinges on capital markets volume and office exposure, so this result mainly helps investors judge execution quality relative to those existing upsides and pressure points.
Jones Lang LaSalle's current analyst framework points to forecast revenues of US$34.4b and earnings of US$1.4b by 2029. This is built on an assumed 7.8% yearly revenue growth rate and an earnings increase of about US$401m from US$999.1m today.
Uncover why Jones Lang LaSalle's fair value indicates a 12% potential upside to its current price that may not last much longer.
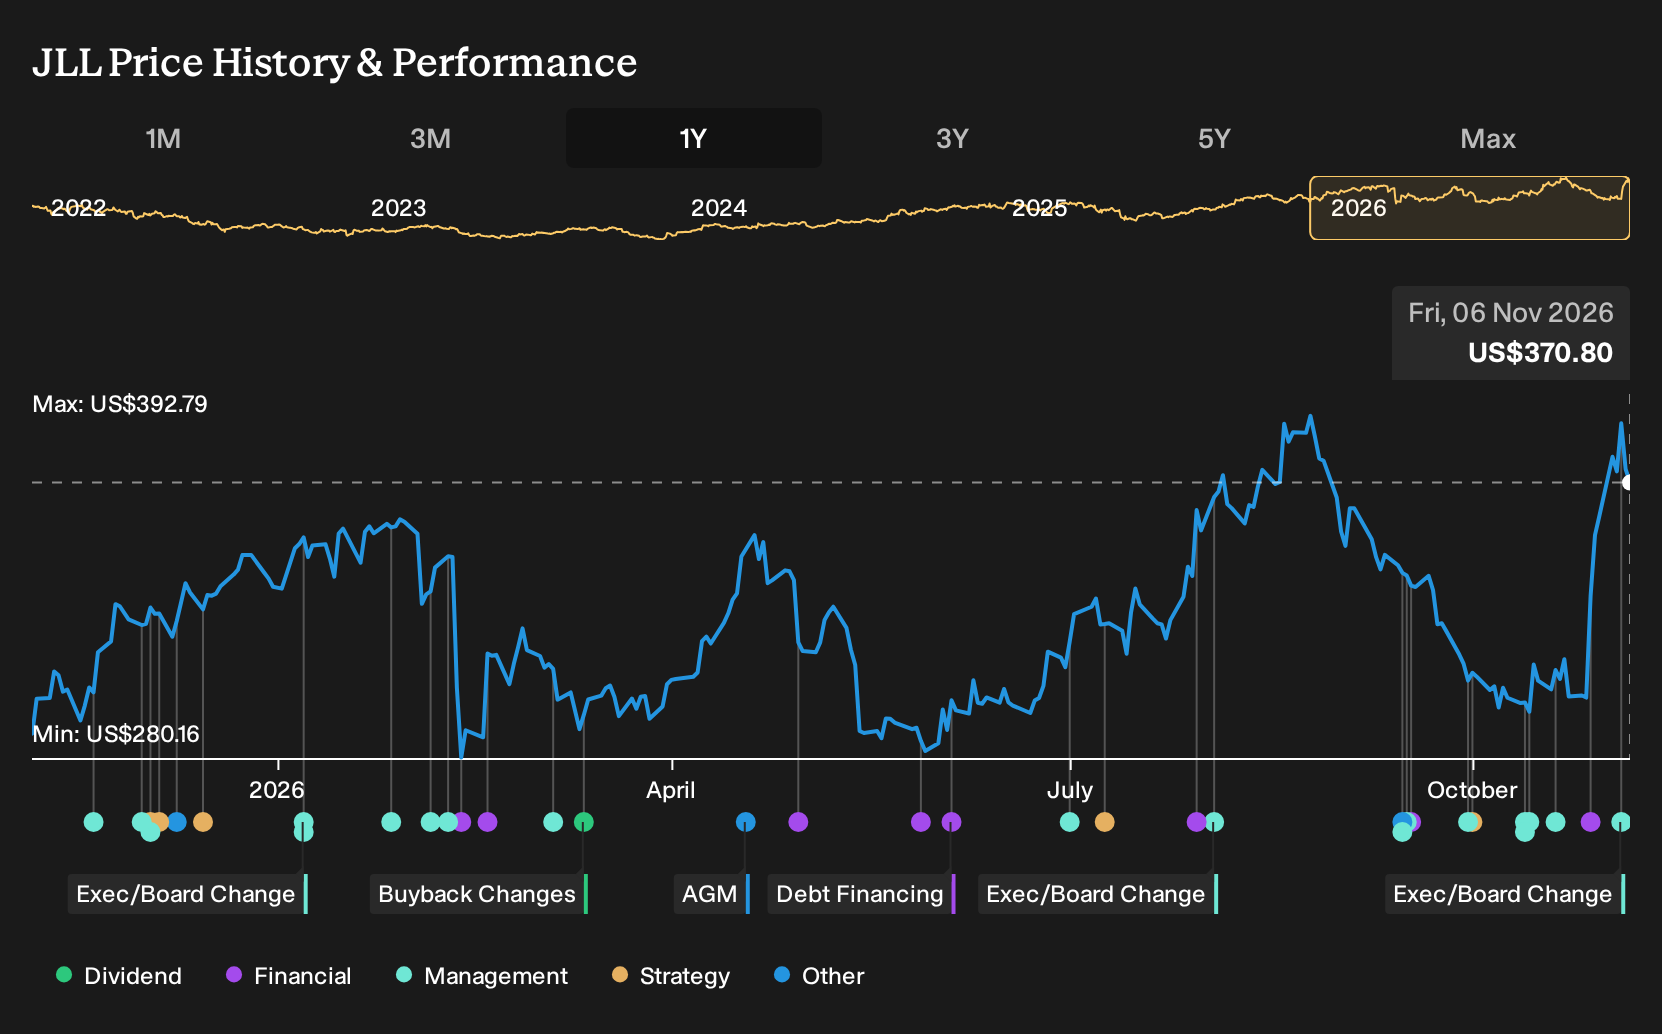
Exploring Other Perspectives
One alternate angle focuses less on office risk and more on whether Jones Lang LaSalle can keep its Real Estate Management Services and AI tools from being priced away through lower fees. The most cautious analysts were only penciling in roughly 7.5% annual revenue growth to about US$34.1b and earnings of US$1.4b by 2029 before this board and earnings news, so their narrative looks materially more pessimistic than consensus. That gap shows how far opinions can spread and why it can help to compare several viewpoints before deciding how this fresh director expertise and recent results might reshape expectations.
Explore 2 other Jones Lang LaSalle fair value estimates, including one that suggests up to 10% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Jones Lang LaSalle research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Jones Lang LaSalle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jones Lang LaSalle's overall financial health at a glance.
Looking for more Jones Lang LaSalle style investment ideas?
If the Jones Lang LaSalle story has you thinking about what else might fit your watchlist, it can help to scan a few different angles side by side using the Simply Wall St Screener.
- If you want to focus on potential mispricings, compare Jones Lang LaSalle with a curated set of businesses flagged as having quality fundamentals at attractive valuations through the 39 high quality undervalued stocks.
- If capital preservation matters most to you, start with the 29 resilient stocks with low risk scores to see companies that score well on resilience and risk metrics.
- If balance sheet strength is your non negotiable, filter for companies with robust financial footing via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com