


EN
Learn Why The Bull Case For Avantor Stock Could Change Following Raised 2026 Outlook
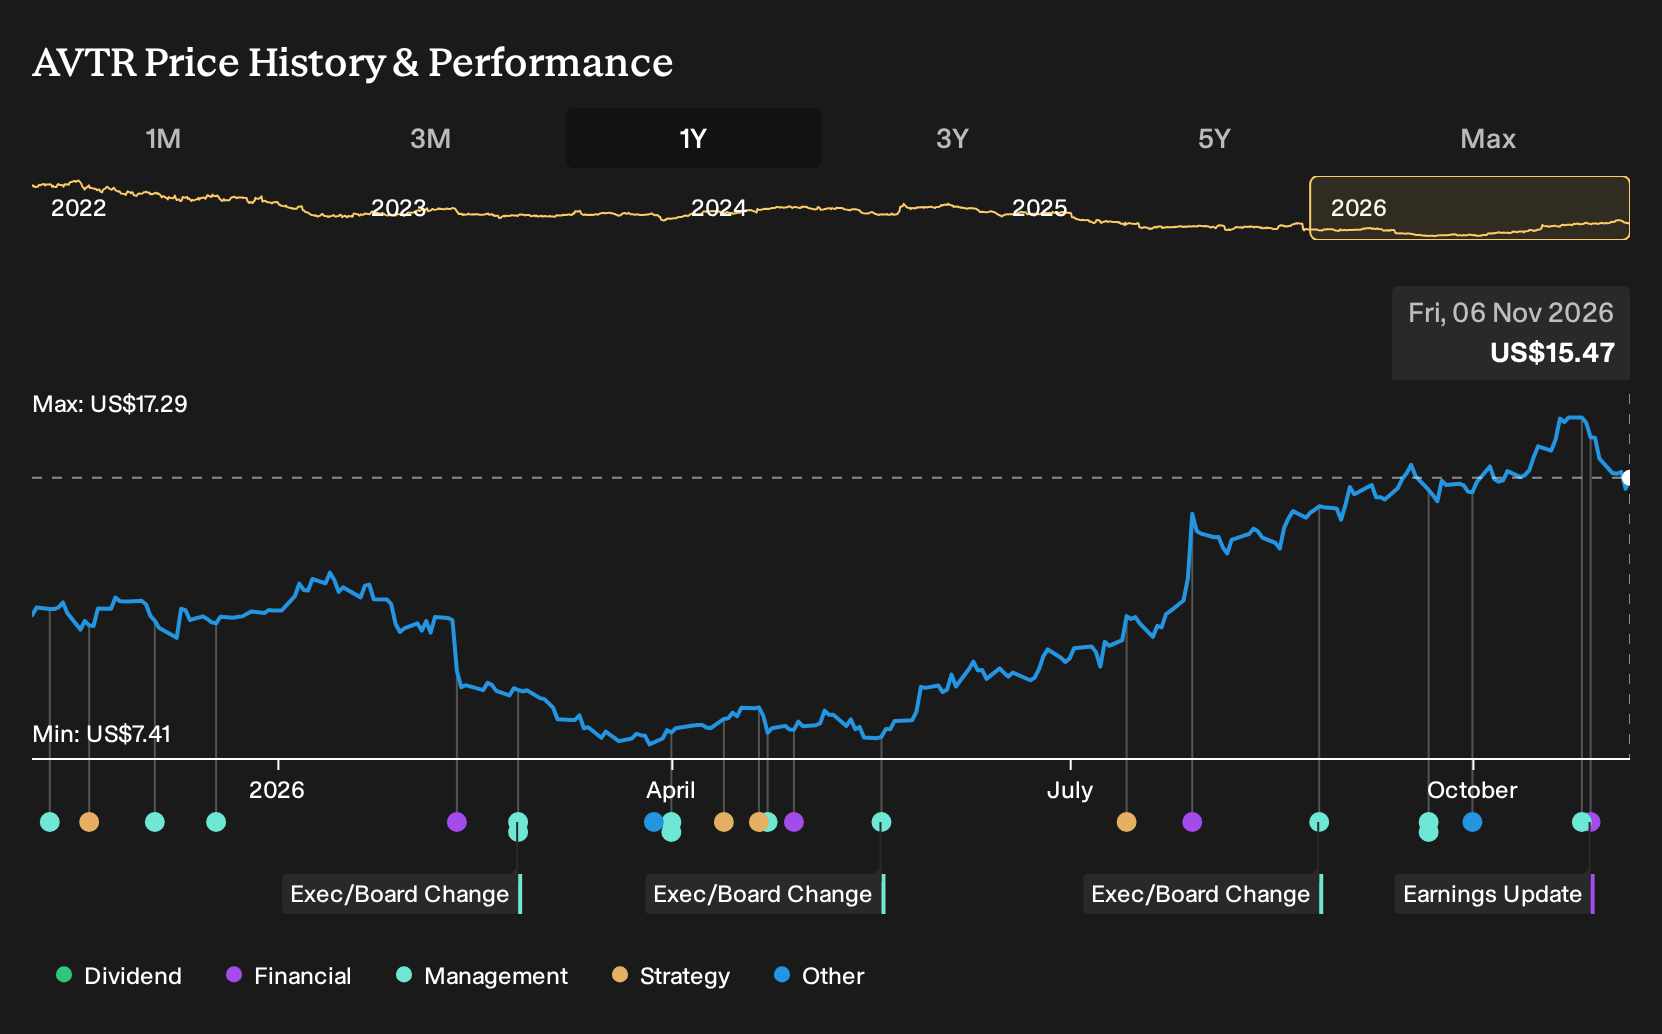
- Avantor reported third quarter 2026 sales of US$1,698.3 million and net income of US$203.4 million, a shift from a net loss a year earlier, and raised full year 2026 guidance for organic revenue growth, adjusted earnings and free cash flow after stronger than expected results.
- The company is pairing improved profitability with leadership change, bringing in a new Chief Information Officer to drive digital transformation and to support its execution on higher earnings and cash flow targets.
- This article now examines how Avantor’s raised 2026 outlook, particularly the higher adjusted earnings guidance, could reshape the existing investment narrative.
See how Avantor's raised earnings outlook compares with other potential breakouts by checking the curated 39 high quality undervalued stocks, which highlights companies that combine strong cash generation with balance sheet resilience.
Avantor Investment Narrative Recap
To own Avantor, you need to believe the Revival program and digital push can translate a complex catalog of lab products into steadier orders, better mix and reliable free cash flow. The latest quarter, with sales of US$1,698.3 million and net income of US$203.4 million, supports that execution story without fundamentally changing it.
The raised 2026 guidance makes the near term catalyst quite clear. Investors are watching whether organic growth and margins can hold up as end markets like biotech and academia remain fragile. The main risk stays the same. Competitive pressure and any stumble on cost savings could limit the benefit of this guidance upgrade.
The third quarter 2026 earnings release is the key event here. Avantor showed sales of US$1,698.3 million compared with US$1,623.8 million a year earlier and moved from a net loss of US$711.8 million to net income of US$203.4 million. Management also lifted outlook for organic revenue, adjusted earnings and free cash flow for 2026.
That combination directly links to the existing catalysts around Revival, digital investments and debt reduction. More confident guidance only matters if order intake, vwr.com traction and Bioscience & Medtech backlog conversion keep supporting cash generation. The earnings step up helps, although it does not remove the risk from competitive pricing and weaker funding across key customer groups.
Avantor Consensus Outlook in Context
Avantor's raised 2026 outlook sits alongside a longer range analyst framework that already sketches out what a successful Revival program could look like by the end of the decade. That framework matters because it shows how much of the potential turnaround is already baked into current expectations, rather than sitting as blue sky upside.
Analysts in the Simply Wall St report expect Avantor's revenue to grow by 3.3% each year over the next three years, paired with profit margins that move from 5.1% today to 5.6%. The same group sees earnings today at US$337.2 million and consensus earnings of US$407.3 million by 2029, which implies a value increase of about US$70 million that would need to show up on the income statement to match their projections.
On those numbers, the forward looking narrative is very specific. By 2029, analysts are anchoring on US$7.3b of revenue and US$407.3 million of earnings, with Avantor trading on a P/E of 36.5x compared with 33.5x today. That multiple is lower than the current 46.3x P/E quoted for the US life sciences peer group in the same report, which suggests the current consensus does not require the stock to trade at the top of sector ranges to justify the price target.
There is also an equity story baked into the share count. Forecasts assume the number of shares outstanding declines by 0.62% per year over the next three years. If that buyback path holds, a larger part of any future earnings pool would accrue to each share, which matters for investors who track earnings per share and not just absolute profit dollars.
Avantor's narrative projects US$7.3b revenue and US$407.3 million earnings by 2029. This requires 3.3% yearly revenue growth and an increase of about US$70 million in earnings from US$337.2 million today.
To connect this back to the latest 2026 guidance raise, the new earnings outlook effectively tightens the near term checkpoint on this 2029 script. Investors can now compare the upgraded adjusted EPS range of US$0.80 to US$0.83 in 2026 with the longer term US$0.70 consensus EPS mark for 2029 in the report and decide whether that path feels conservative, aggressive or simply a different earnings lens shaped by non GAAP adjustments and capital structure assumptions.
The current analyst fair value framework is built using a discount rate of roughly 8.8% and results in a consensus price target of US$17.35, only 3.8% above the recent US$16.68 share price quoted in the same analysis. That narrow gap signals that, on average, analysts see Avantor as roughly fairly priced against their 2029 revenue, earnings and P/E assumptions rather than obviously misvalued.
For readers, the takeaway is straightforward. The raised 2026 targets strengthen the near term earnings story, but the longer term analyst view already assumes steady top line growth, modest margin improvement and a healthy profit step up by 2029. Any investment case around Avantor now turns on whether those moving parts feel realistic in light of competitive pressure, end market funding trends and management's ability to keep executing on Revival and digital upgrades without slipping on costs.
Uncover why Avantor's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Avantor focuses on slower demand rather than Revival upside. The most cautious analysts were only pencilling in about US$7.2b of revenue and US$395.9 million of earnings by 2029 before this earnings beat and guidance hike. That outlook presents a more muted earnings path, so consider it as a useful point of comparison alongside several viewpoints before evaluating how this new quarter might affect the overall narrative.
Explore another Avantor fair value estimate, including one that suggests it could be worth just $17.35.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avantor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Avantor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avantor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avantor?
If Avantor's story has sharpened your view on earnings power and balance sheet strength, it can help to compare it with other potential opportunities side by side. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is resilience, income, or underappreciated quality.
- For investors who prize stability and risk control, review a 29 resilient stocks with low risk scores that score well on resilience so you can focus on businesses with steadier profiles.
- If you want to cast a wider net for quality that the market might be overlooking, scan a curated 19 high quality undiscovered gems with strong fundamentals that are less crowded by attention.
- Income focused readers who care about cash returns today can check a hand picked 8 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com