


EN
Earnings Outlook Could Be A Big Deal For NXP Stock (NXPI)
- NXP Semiconductors reported third quarter 2026 basic EPS from continuing operations of US$3.51 and issued fourth quarter guidance for US$3,750 million to US$3,950 million of revenue, US$1,167 million to US$1,304 million of operating income, and diluted EPS of US$3.36 to US$3.79.
- The newly announced Volkswagen Group partnership around S32K5 microcontrollers for future software defined vehicle platforms underscores how NXP Semiconductors is tying its earnings profile directly to long term automotive electronics demand.
- We will examine how NXP Semiconductors' investment narrative is influenced by strong fourth quarter guidance and the Volkswagen software defined vehicle partnership.
Scan 52 AI infrastructure stocks to see which other chipmakers are being positioned for the same kind of long term automotive and data infrastructure demand that NXP Semiconductors is tied into.
NXP Semiconductors Investment Narrative Recap
NXP Semiconductors appeals to shareholders who buy into a long haul build out in automotive, industrial and data infrastructure chips, supported by higher value mixed signal products and strong earnings quality. The latest fourth quarter guidance points to continued profitability and a still healthy operating profile, so the core thesis around content per car and industrial processing remains intact.
The key near term catalyst is whether auto and industrial customers keep ordering steadily as inventories normalize, especially in China where an eventual correction would hurt. The biggest current risk looks more sentiment driven, with investors potentially refocusing on wide guidance ranges, high debt levels and any renewed talk of large acquisitions.
The Volkswagen Group agreement around S32K5 microcontrollers is the clearest link between NXP Semiconductors and the software defined vehicle catalyst that many investors are watching. It ties the chip portfolio directly to zonal architectures that aim to consolidate many separate control units into fewer, more capable controllers in future Volkswagen and Rivian related platforms.
This arrangement matters because it speaks to design win depth, not just near term revenue. Execution risk does not go away, since delays in SDV rollouts, auto inventory swings in China or preference for peers with more AI data center exposure could still weigh on sentiment, but the Volkswagen deal gives a concrete anchor for the SDV part of the story.
NXP Semiconductors' current earnings of US$3.0b are projected by analysts to reach US$4.7b in 2029, implying an earnings increase of about US$1.7b. The same forecasts call for revenue growth of 10.2% per year and point to 2029 revenues of US$17.6b.
Uncover why NXP Semiconductors' fair value indicates a 21% potential upside to its current price that could narrow quickly.
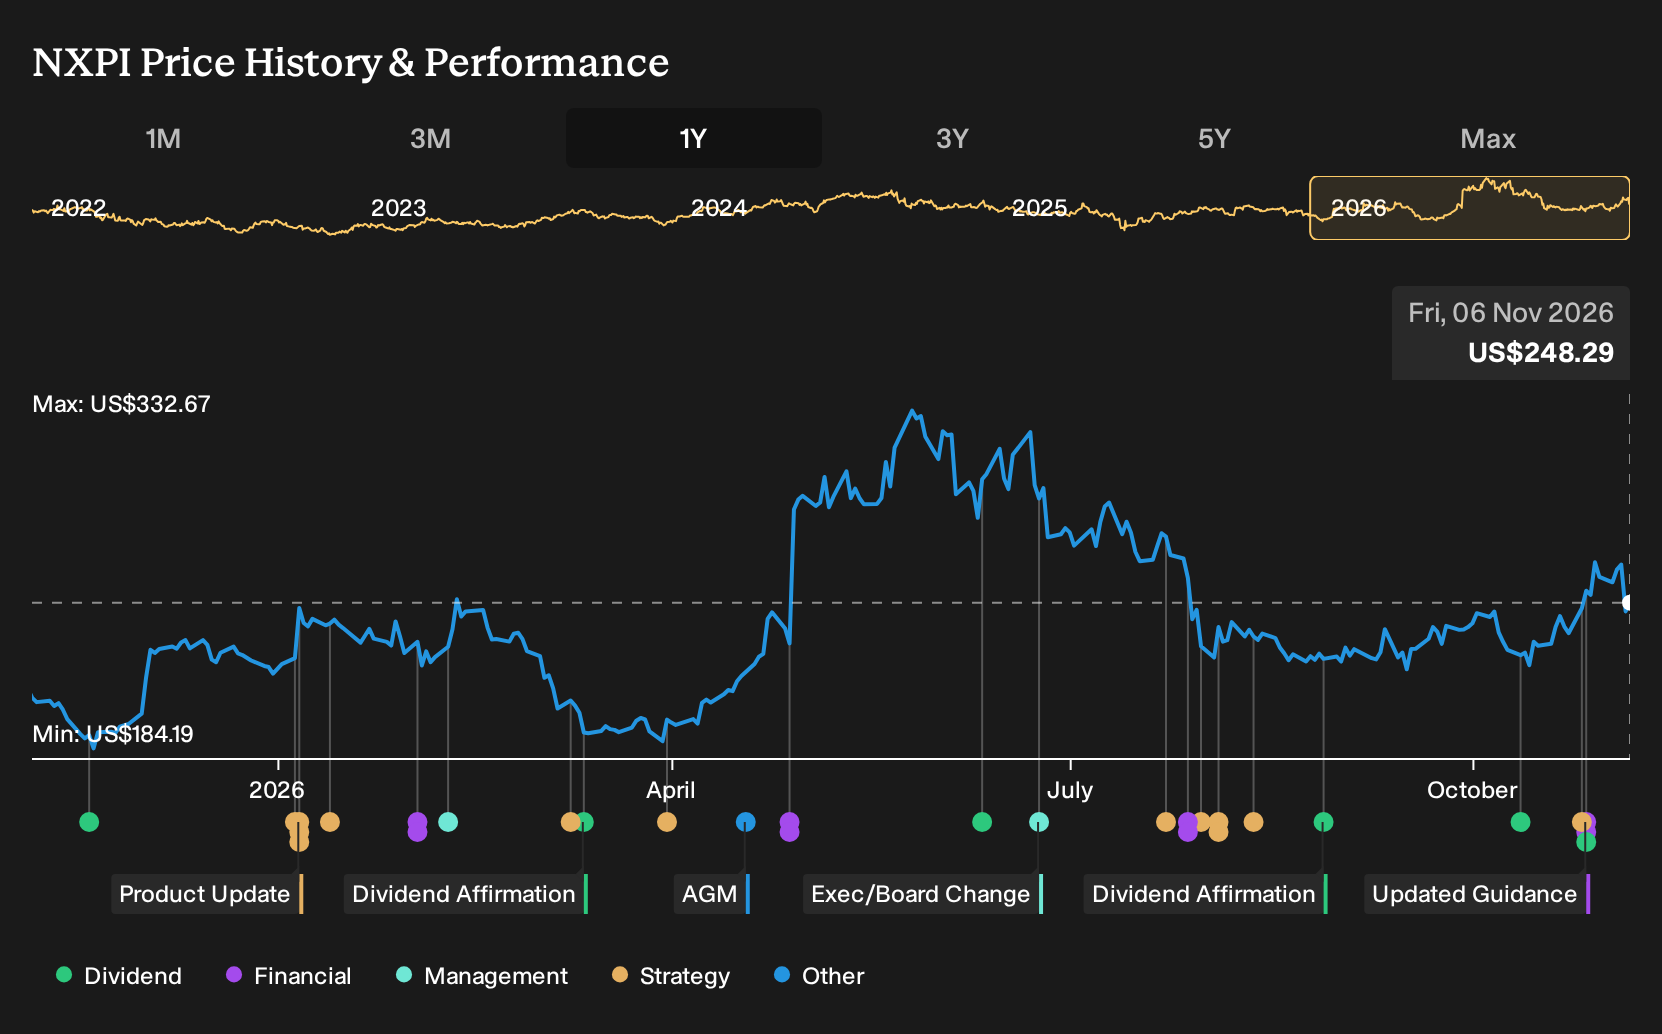
Exploring Other Perspectives
One alternate view on NXP Semiconductors places much greater emphasis on the risk of a weak China auto cycle. Before this news, the most cautious analysts were only estimating about 8.4% annual revenue growth with earnings of roughly US$4.3b by 2029. That is a much more subdued outlook. Use it as a prompt to compare several viewpoints before deciding what this new guidance and the Volkswagen deal might change.
Explore 5 other NXP Semiconductors fair value estimates, including one that indicates as much as 15% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NXP Semiconductors research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NXP Semiconductors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NXP Semiconductors' overall financial health at a glance.
Looking For More NXP Semiconductors Investment Ideas?
If the NXP Semiconductors story has sharpened your thinking, use that momentum to widen your watchlist. The Simply Wall St Screener can help you spot other opportunities that fit your preferred mix of quality, risk and income.
- If capital preservation is a priority, start with companies that score well on resilience and financial risk by scanning 29 resilient stocks with low risk scores.
- For investors hunting for value, look across businesses that combine solid cash generation with attractive pricing using the 39 high quality undervalued stocks.
- If a sturdier balance sheet matters most to you, filter for companies with stronger fundamentals and less leverage through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com