


EN
British Penny Stocks To Watch In November 2026
The Bank of England has already lifted interest rates for the first time in more than three years, and borrowing costs in the UK feel heavier with every mortgage bill. Higher rates tend to punish weaker balance sheets. They can also spotlight smaller, lower priced British shares that still look financially resilient. This article walks through three such penny stocks filtered for stronger finances, so you can judge which, if any, deserve a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses backed by stronger balance sheets. However, if you want the names that matter most, these 17 elite penny stocks are the strongest companies we've found.
Ashmore Group (LSE:ASHM)
Overview: Ashmore Group is a London-based asset manager that runs emerging-market equity and debt funds, including strategies focused on smaller, earlier-stage issuers.
Operations: The group generates £139.3 million from investment management services, with about £88.4 million from the United Kingdom and Ireland and the rest from the Americas plus Asia and the Middle East.
Market Cap: £1.34 billion
Ashme Group provides exposure to emerging-market penny-style opportunities through its fund range, while still sitting inside an established, listed asset manager focused on financial health.
"The renewed net inflow phase into emerging markets, with Ashmore Group reporting FY26 net inflows of $2.7b alongside rising subscriptions and lower redemptions, creates scope for a longer period of higher fee earning AuM than consensus typically models."
What happens if a single pressure on how that fee pool converts into long run profits shifts more than investors currently expect?
That pressure point is exactly where the full narrative for Ashmore Group shows how fee margins, AuM mix and capital returns could be decoupling from what the market currently prices in.

IntegraFin Holdings (LSE:IHP)
Overview: IntegraFin Holdings runs the Transact wrap platform that helps UK advisers manage client portfolios and tax wrappers, including smaller, lower-priced equity positions.
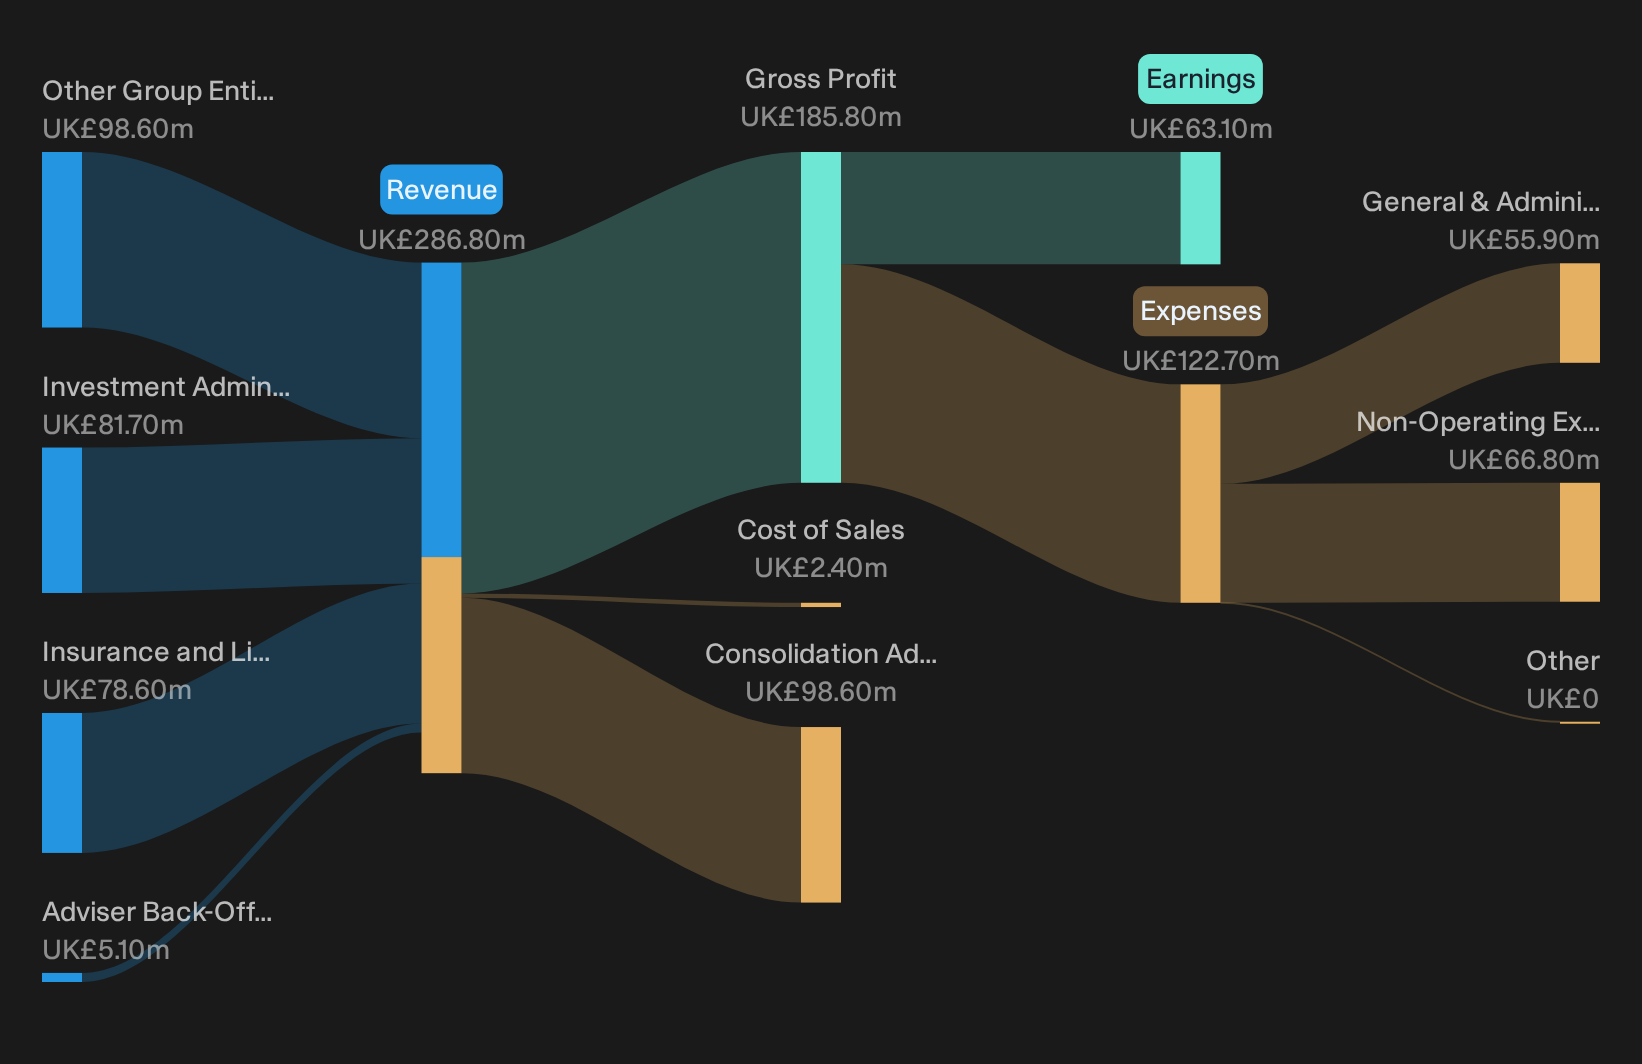
Operations: The group earns £81.7 million from Investment Administration Services, £78.6 million from Insurance and Life Assurance, and £5.1 million from Adviser Back-Office Technology, largely across £157.5 million in UK revenue.
Market Cap: £1.25 billion
IntegraFin Holdings matters for this Financially Fit Penny Stocks screen because Transact connects directly to advisers who manage smaller, often early-stage holdings while relying on a financially disciplined platform operator.
"Strong Transact net inflows and client growth remain a live driver, with recent periods showing record gross inflows and funds under direction above £80b. This expands IntegraFin Holdings’ recurring fee base and supports revenue."
There is a risk if a single planned shift in cost discipline and automation delivers less margin support than current expectations quietly build in.
If that margin story matters to you, read the full narrative for IntegraFin Holdings to see how cost discipline, automation and inflows could reshape IntegraFin Holdings’ earnings path.
Currys (LSE:CURY)
Overview: Currys runs an omnichannel retail and services business focused on budget-friendly consumer electronics, refurbished devices and support across the UK and Nordics.
Operations: Currys generates about £5.5b from the UK & Ireland and £3.8b from the Nordics, with smaller eliminations between segments.
Market Cap: £1.47b
Currys leans into the Financially Fit Penny Stocks theme through low-cost tech, refurbished products and services that help budget-conscious customers stretch each upgrade further.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can keep lifting Currys group revenue quality and EBIT margins as more customers shift into these offers."
What happens if a single unseen pressure on how those higher margin services convert into lasting cash generation shifts more than expected?
That hidden pressure point is exactly where the full narrative for Currys shows whether Currys’ higher margin services are quietly accelerating value or masking new risks.

Seeking Alternatives Before Others Catch On
Fresh opportunities can move quickly. Strong balance sheets, new momentum and under the radar stories can be noticed rapidly once more investors pay attention. Look for what others might miss and consider acting before broader interest develops.
- Target sturdier portfolios by focusing on companies screened for resilience and quality through the list of solid balance sheet and fundamentals (9 results) before that strength is fully reflected in prices.
- Look for early breakout potential by scanning curated 5 high quality undiscovered gems that remain under the radar for now and may attract more attention over time.
- Track income ideas by reviewing 4 dividend fortresses that can provide yield supported by robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com