


EN
Ameren (AEE) Beat Expectations And Raised Guidance, Has The Upside Already Been Priced In?
Ameren (AEE) just delivered third quarter 2026 earnings that came in ahead of expectations, along with higher guidance for both 2026 and 2027, putting its grid investment story firmly in focus for investors.
Ameren’s share price has picked up momentum ahead of this earnings release, with an 11.4% 30 day share price return and an 11.9% year to date share price return. The 3 year total shareholder return of 62.2% points to a much stronger longer term payoff from dividends plus reinvested gains.
Scan for other grid and power-infrastructure plays that may be benefiting from rising electricity demand by running the hand-picked 42 power grid technology and infrastructure stocks alongside Ameren on your watchlist.
After Ameren’s sharp move and fresh guidance, the current price sits only slightly below analyst targets while implying a much steeper discount to some intrinsic value models. Which reference point deserves more weight in your valuation work next?
Most Popular Narrative: 3% Undervalued
Ameren’s most followed valuation story points to a fair value of about $116.81, a touch above the latest $112.85 close. This keeps the debate squarely on how durable its grid and load growth plans really are.
Rapid growth in large data center and hyperscaler demand in Ameren Missouri's territory, reflected in 2.8 gigawatts of signed electric service agreements, 3.4 gigawatts of construction agreements and a further 4 gigawatts of projects with completed interconnection studies, is expected to translate into higher electricity sales and a larger regulated revenue base as contracted load ramps through 2029 and beyond, supporting earnings.
See why 5 investors see Ameren as 3% undervalued.
Result: Fair Value of $116.81 (UNDERVALUED)
Still, this narrative leans heavily on timely hyperscaler build outs and continued regulatory support in Missouri and Illinois, both of which could disappoint if approvals or capital plans shift.
Find out about the key risks to this Ameren narrative.
Another View: Ameren Through The DCF Lens
There is a different read on Ameren when using the SWS DCF model. On this view, the stock at $112.85 sits above an estimated future cash flow value of $94.56, which frames Ameren as overvalued rather than 3% undervalued. Which signal do you treat as the anchor?
Look into how the SWS DCF model arrives at its fair value.
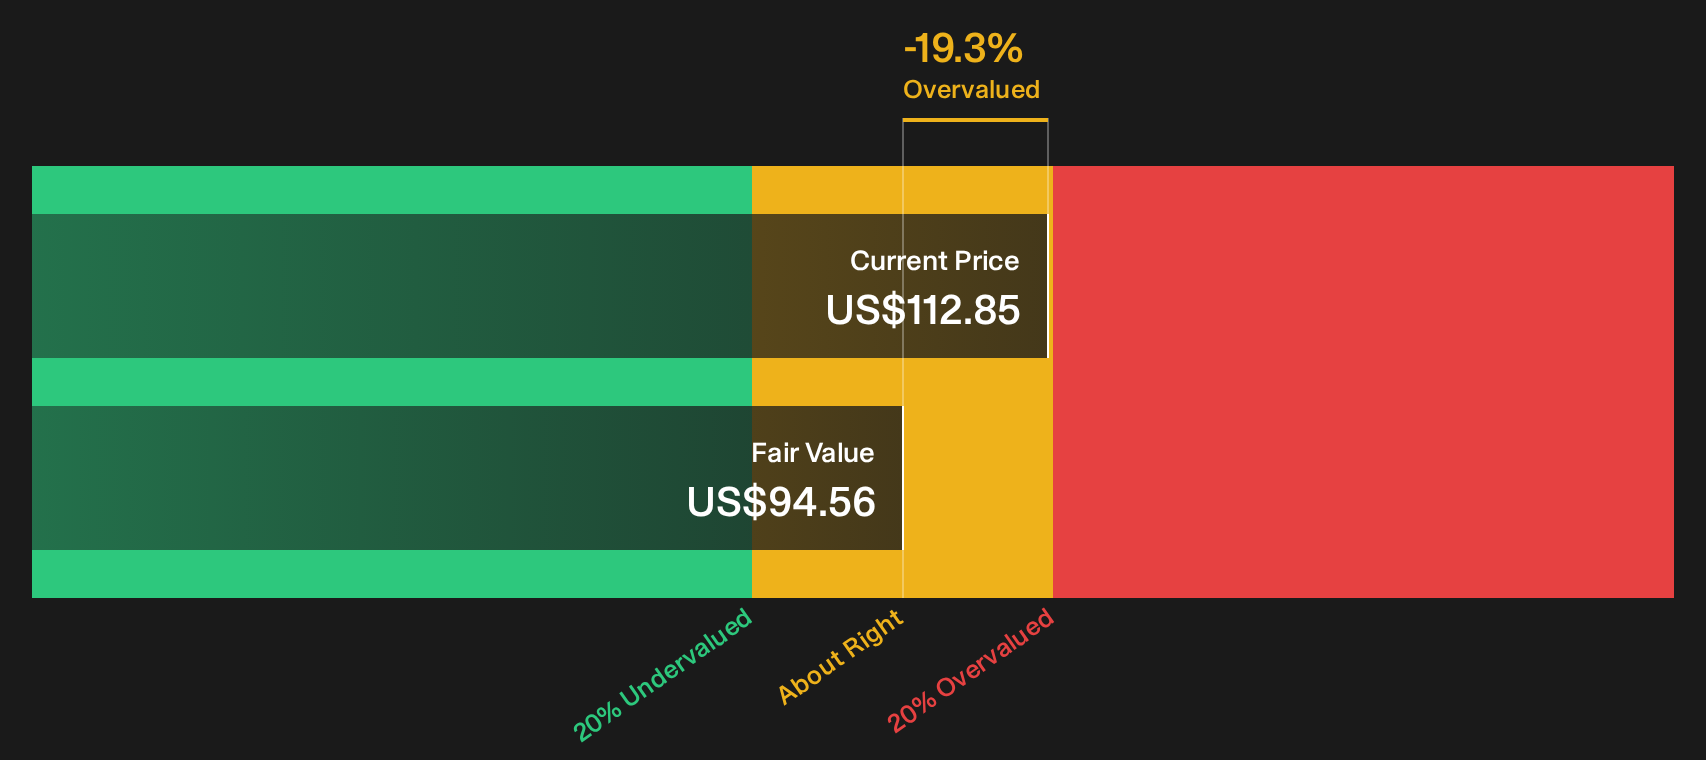
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ameren for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or emerging opportunity: either way, the only view that matters is yours. Stress test Ameren’s story, pressure check the assumptions, and then weigh up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ameren?
If Ameren has sharpened your thinking, do not stop here. Fresh opportunities often show up where few investors are looking, so widen your search now.
- Target sturdier portfolios by focusing on resilience and balance sheet strength through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value candidates that pair quality fundamentals with attractive pricing inside the 39 high quality undervalued stocks.
- Zero in on companies that combine income potential with staying power using the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com