


EN
How Investors May Respond To PROG Holdings (PRG) Expanded Buyback Plan
- PROG Holdings reported third quarter 2026 results with sales of US$552.27 million and net income of US$37.24 million, alongside updated full year guidance and an expanded share repurchase authorization.
- The business paired higher earnings per share from continuing operations with a larger buyback plan and an affirmed quarterly dividend, highlighting its current mix of cash returns and reinvestment priorities.
- Next, the focus turns to how PROG Holdings' reported earnings per share and larger buyback pool may influence its broader investment narrative.
Scan how PROG Holdings' mix of earnings, buybacks and dividends compares with other companies returning cash to shareholders by reviewing the hand picked 8 dividend fortresses list.
PROG Holdings Investment Narrative Recap
To own PROG Holdings, you need to believe its multi product ecosystem can turn steady leasing and BNPL demand into healthier earnings over time while keeping credit losses in check. The latest quarter showed sales of US$552.27 million with net income of US$37.24 million, plus slightly trimmed full year guidance. That shift in outlook matters more than the headline beat on earnings per share.
In the short term, the key catalyst is how Progressive Leasing, Four and Purchasing Power perform against the updated ranges for revenue, net earnings and EPS. The biggest risk remains credit quality and broader profitability pressure. If loss rates or funding costs bite into margins again, the improved EPS from continuing operations may not translate into a more durable profit profile.
The expanded share repurchase authorization, with US$237 million added and the program extended through October 2029, is the announcement that ties closest to the current story. It sits alongside the quarterly dividend of US$0.14 per share and third quarter earnings per share from continuing operations of US$0.92 on a diluted basis.
For you as an investor, the enlarged buyback pool increases the importance of execution on the updated 2026 guidance ranges for revenue, net earnings and diluted EPS. If operations track those targets, repurchases can have a clearer path to lifting per share metrics. If profitability or credit costs disappoint, using that authorization aggressively could limit flexibility just when the business might need it most.
PROG Holdings' current analyst narrative points to US$3.5b revenue and US$222.5 million earnings by 2029, based on forecast annual revenue growth of 10.3%. That outlook compares with earnings today of US$125.8 million, which implies an earnings increase of about US$96.7 million to reach the 2029 consensus level.
Uncover why PROG Holdings' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
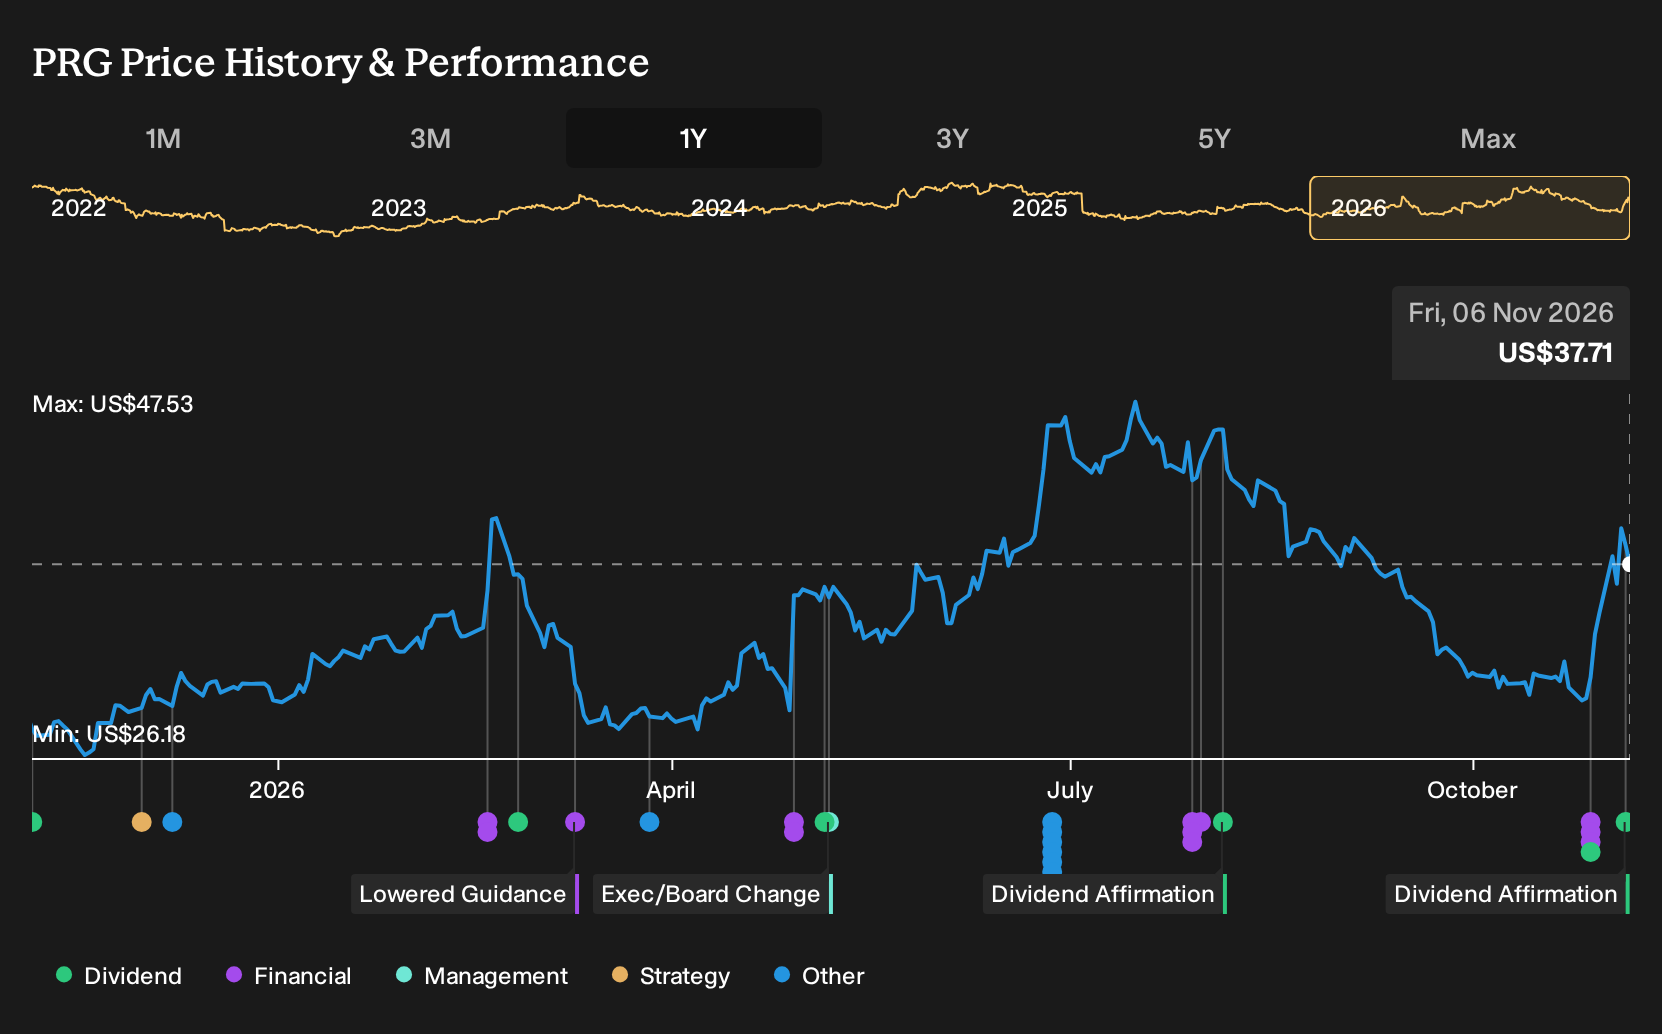
Exploring Other Perspectives
One alternate take on PROG Holdings puts credit costs front and center. The most cautious analysts, who were penciling in about US$3.6b of revenue and US$224.6 million of earnings by 2029 before this quarter, worry that persistently high lease write offs could blunt the benefit of the affirmed dividend and refreshed guidance. Those forecasts outline a more restrained payoff from the multi product ecosystem. Use that gap between consensus and the bearish view as a prompt to explore several scenarios yourself and decide which assumptions feel closest to how you see the business evolving after these updates.
Explore another PROG Holdings fair value estimate, including one that suggests it could be worth just $49.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your PROG Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for PROG Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PROG Holdings' overall financial health at a glance.
Looking for more investment ideas beyond PROG Holdings?
If PROG Holdings has you thinking more broadly about where to put fresh capital to work, it can help to line it up against a wider field of potential opportunities using the Simply Wall St Screener.
- Prefer businesses with robust finances and fewer balance sheet red flags? Start with a curated list of solid balance sheet and fundamentals (24 results) that may fit that profile.
- Hunting for companies that combine quality fundamentals with room for price improvement? Scan the 39 high quality undervalued stocks that match those traits.
- Interested in stocks that many investors overlook but still show strong underlying metrics? Take a look at the 19 high quality undiscovered gems that fit that description.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com