


EN
Why Aya Gold & Silver (TSX:AYA) Shares Moved And What Investors Are Watching
Record production and earnings put Aya Gold & Silver in focus
Aya Gold & Silver (TSX:AYA) moved back onto many watchlists after reporting record third quarter silver equivalent production and a very large jump in net income tied to its Zgounder and Boumadine operations.
The share price reaction has been quick. Aya Gold & Silver rallied 3.95% on the day of the latest update and logged an 11.36% 7 day share price return, even though the 30 day and 90 day share price returns are down 4.13% and 5.54%. This suggests near term momentum is rebuilding after a pullback within a much stronger backdrop that includes an 84.15% year to date share price return and a 1 year total shareholder return of 150.56%, with multi year total shareholder returns above 3x over three years and just under 3x over five years.
Scan Aya Gold & Silver’s latest surge in production alongside other precious metals opportunities by reviewing the hand picked 33 elite gold producer stocks now in focus with similar momentum stories.
Recent gains in Aya Gold & Silver look tied to record production and earnings, not just changing sentiment. The next step is to see how that recent performance lines up against the current valuation.
Most Popular Narrative: 29% Undervalued
Aya Gold & Silver’s most followed narrative tags fair value at about CA$50.66 per share, compared with the recent CA$35.78 closing price. This frames the latest production headlines inside a much larger multi asset story.
The transition of Aya Gold & Silver from a single mine producer toward a multi asset operator through the build out of Boumadine, supported by a 2026 study that outlines a 14 year mine life and multi billion dollar project value, could lift future revenue and earnings from a higher production base.
The large scale drilling program at Boumadine through 2026 and 2027, combined with the roughly 35% increase in Moroccan land holdings including new permits and licenses, gives Aya Gold & Silver multiple chances to add resources and future mineable ounces that can extend production and cash flow visibility.
See why 44 investors see Aya Gold & Silver as 29% undervalued.
Result: Fair Value of CA$50.66 (UNDERVALUED)
Still, any prolonged 40% Moroccan tax burden or a sharper than expected margin squeeze toward the forecast 19.4% profit level could easily weaken the Aya Gold & Silver narrative.
Find out about the key risks to this Aya Gold & Silver narrative.
Another View: Aya Gold & Silver Through Its P/E
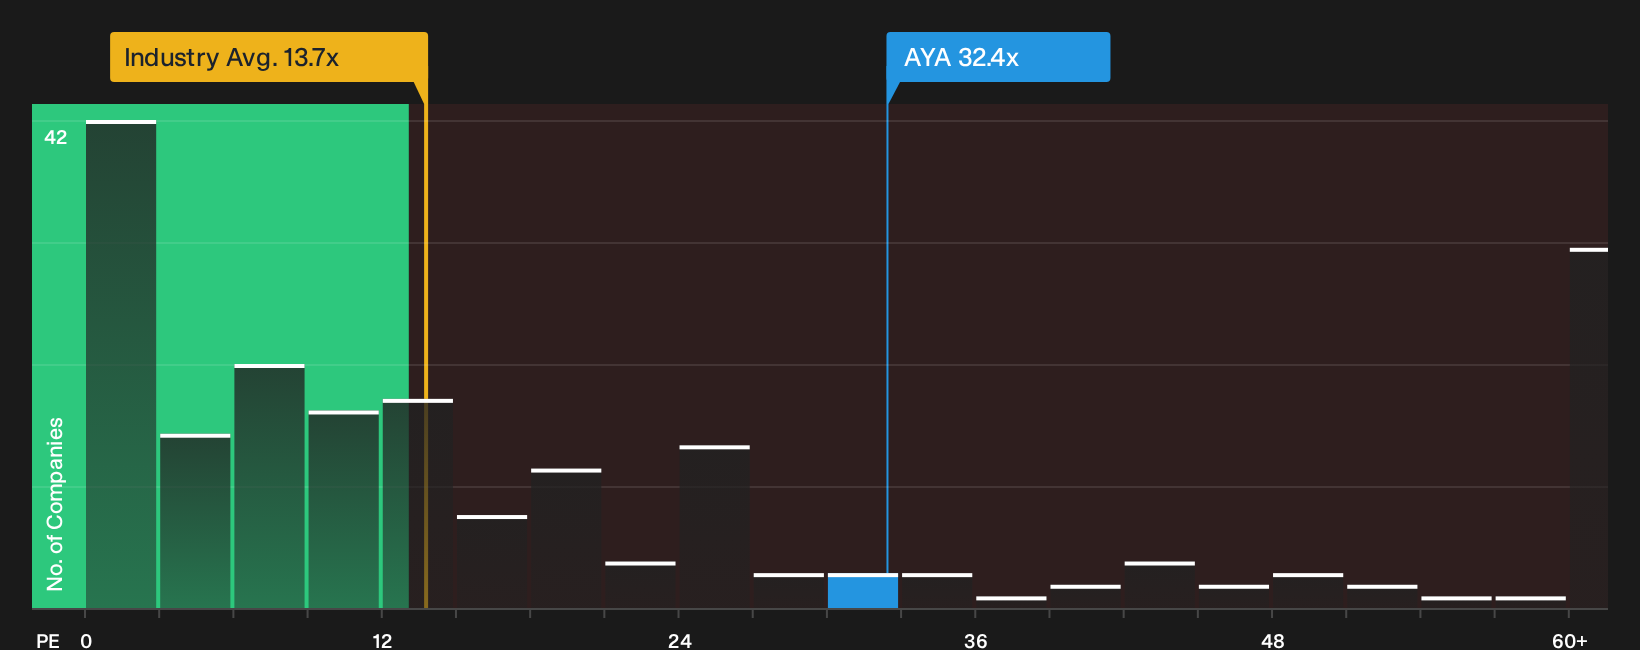
The fair value narrative pegs Aya Gold & Silver at CA$50.66 per share, yet the current P/E of 32.4x is higher than both peers at 30.4x and the Canadian metals and mining average at 13.7x, and well above a fair ratio of 8.9x. That kind of gap can signal valuation risk if sentiment cools or an opportunity if earnings hold up longer than forecast. Which side do you think the market is leaning toward?
For a closer look at how these earnings multiples stack up against fundamentals and whether the current price reflects more hope than cash flow, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism runs through this Aya Gold & Silver story, but the mixed signals on risks and rewards mean the real call sits with you. If you want to balance the upside drivers against the pressure points that investors are watching, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aya Gold & Silver?
Aya Gold & Silver gives you one compelling story, but your portfolio could benefit from multiple perspectives. Use the screener to spot what others might miss.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (5 results) to help keep financial risk in check when conditions change.
- Explore potential mispricings by reviewing the 6 high quality undervalued stocks, which combines quality metrics with discounted valuations.
- Look for possible future standouts by tracking the 7 high quality undiscovered gems that are quietly building strong fundamentals before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com