


EN
How Investors Are Reacting To Ventas (VTR) Raised Earnings Guidance
- Ventas reported third quarter 2026 net income of US$65.38 million on revenue of US$1,831.79 million and at the same time raised full year net income guidance to a range of US$324 million to US$339 million, or US$0.64 to US$0.67 per share.
- The company attributed the higher outlook primarily to accretive senior housing investment activity, highlighting how its capital deployment into this segment is flowing through to expectations for stronger full year profitability.
- The next area of focus will be how Ventas' higher full year earnings guidance tied to senior housing investments could reshape the broader investment narrative.
Ventas Investment Narrative Recap
To own Ventas, you need to be comfortable with a senior housing story that leans heavily on operational execution. The thesis is that its large senior housing operating portfolio can keep converting demographic demand into occupancy and pricing, even as quarterly net income and earnings per share move only modestly. The latest quarter, with revenue of US$1,831.79 million and net income of US$65.38 million, does not materially alter that bigger picture.
The short term catalyst is whether recently acquired or converted communities sustain near 90% occupancy and solid rate growth as they season. The main risk remains that operator performance or local markets soften, which would pressure same store NOI and magnify the impact of interest costs, especially when interest payments are not well covered by earnings and Ventas relies on external funding.
The raised 2026 net income guidance to US$324 million to US$339 million, or US$0.64 to US$0.67 per share, is the announcement that most clearly links to this quarter. Management tied the uplift mainly to accretive senior housing investment activity, with interest rates and foreign exchange partly offsetting that benefit. That indicates where the business is leaning for near term earnings support.
For you as a shareholder, the practical question is whether Ventas can keep sourcing senior housing deals at acceptable yields without eroding returns through higher funding costs or equity dilution. Competition for properties, the use of equity funded growth and the need to keep occupancy and RevPOR healthy at the property level all feed directly into whether this guidance range proves achievable and how repeatable that earnings profile looks beyond 2026.
Ventas' current analyst narrative points to revenue of US$8.9b and earnings of US$677.2 million by 2029, based on assumed yearly top line expansion of 11.6% and an earnings increase of about US$414.5 million from US$262.7 million today.
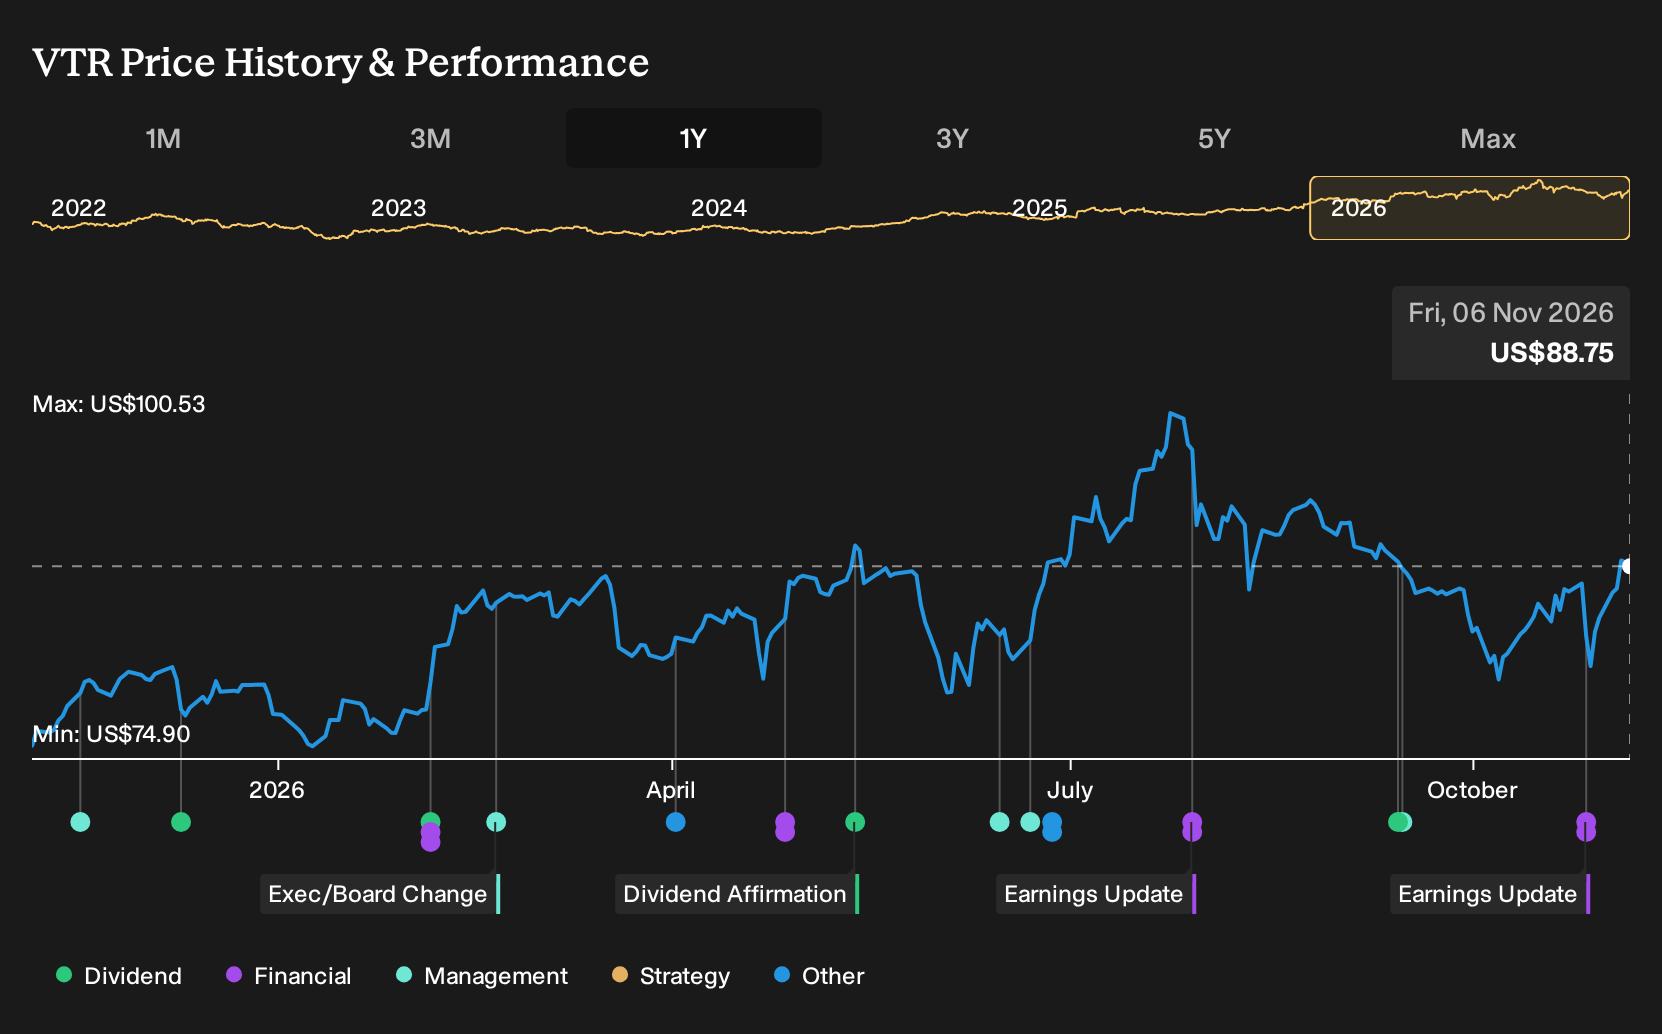
Discover why Ventas' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community currently cluster between about 100 and 113, so some retail investors see Ventas stock trading at a double digit discount to their projections. Those views sit alongside fresh 2026 guidance tied to senior housing investments, which raises the stakes on occupancy resilience and funding costs. Opinions can differ sharply, so it is worth reviewing several community viewpoints before setting expectations.
Explore another Ventas fair value estimate, including one that suggests as much as 27% upside from the current price.
Form Your Own Verdict
Do you disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own instincts.
- A great starting point for your Ventas research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ventas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ventas' overall financial health at a glance.
Looking for more investment ideas beyond Ventas?
If you want to pressure test your view on Ventas and broaden your opportunity set, the Simply Wall St Screener can help you quickly line up other businesses with financial profiles that match your risk and income goals.
- For investors who want potentially underappreciated opportunities, scan through 39 high quality undervalued stocks that may offer more attractive entry points based on current fundamentals.
- If preserving capital is a priority, focus on steadier profiles by reviewing 29 resilient stocks with low risk scores that aim to keep volatility and financial fragility in check.
- For those hunting for overlooked stories with solid numbers behind them, filter the market with 19 high quality undiscovered gems that pair quality metrics with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com