


EN
Is Updated Guidance Altering The Investment Case For Pentair Stock (PNR)?
- Pentair reported third quarter 2026 basic and diluted EPS from continuing operations of US$0.91, with nine-month EPS from continuing operations around US$2.70 on both a basic and diluted basis.
- The full year 2026 outlook pairs expected GAAP EPS from continuing operations of about US$3.76 with management guidance for lower reported sales and operating income. This underlines the trade-off between earnings quality and top line pressure.
- We will look at how Pentair's investment narrative is affected by lower full year sales guidance alongside higher fourth quarter earnings expectations.
Compare Pentair's updated outlook with a curated 39 high quality undervalued stocks that may be priced for compression in sales yet still producing solid earnings power.
Pentair Investment Narrative Recap
Pentair appeals to shareholders who want a water-focused portfolio built around operational efficiency, higher margin products and a gradual mix shift away from more volatile Pool activity. The latest quarter showed lower EPS from continuing operations versus last year, so the near-term story still centers on managing through softer conditions rather than broad-based expansion.
The updated 2026 outlook points to roughly US$3.76 in GAAP EPS from continuing operations, along with lower full year sales and operating income. That combination keeps the main short-term catalyst focused on execution in Flow and Water Solutions, while the key risk remains Pool exposure and any further reset in demand or dealer ordering patterns.
The most relevant development for this catalyst and risk mix is the new guidance for the fourth quarter of 2026. Management is flagging GAAP EPS from continuing operations of about US$1.07, with sales expected to rise 7% to 9% and operating income to increase 16% versus the same quarter in 2025. This frames Q4 as an important proof point on operational delivery.
If Pentair hits those Q4 targets, it would help support the idea that cost programs, portfolio reshaping and a tilt toward commercial and infrastructure projects can offset some of the earnings drag from Pool. If the quarter falls short, it would reinforce the sensitivity of results to segment swings and keep litigation, guidance volatility and execution risk firmly in focus for investors.
Pentair's narrative projects US$5.4b revenue and US$1.0b earnings by 2029, which implies forecast revenue growth of 11.0% per year and an earnings increase of about US$404m from current earnings of US$596.3m.
Uncover why Pentair's fair value indicates a 4% potential upside to its current price that could narrow quickly.
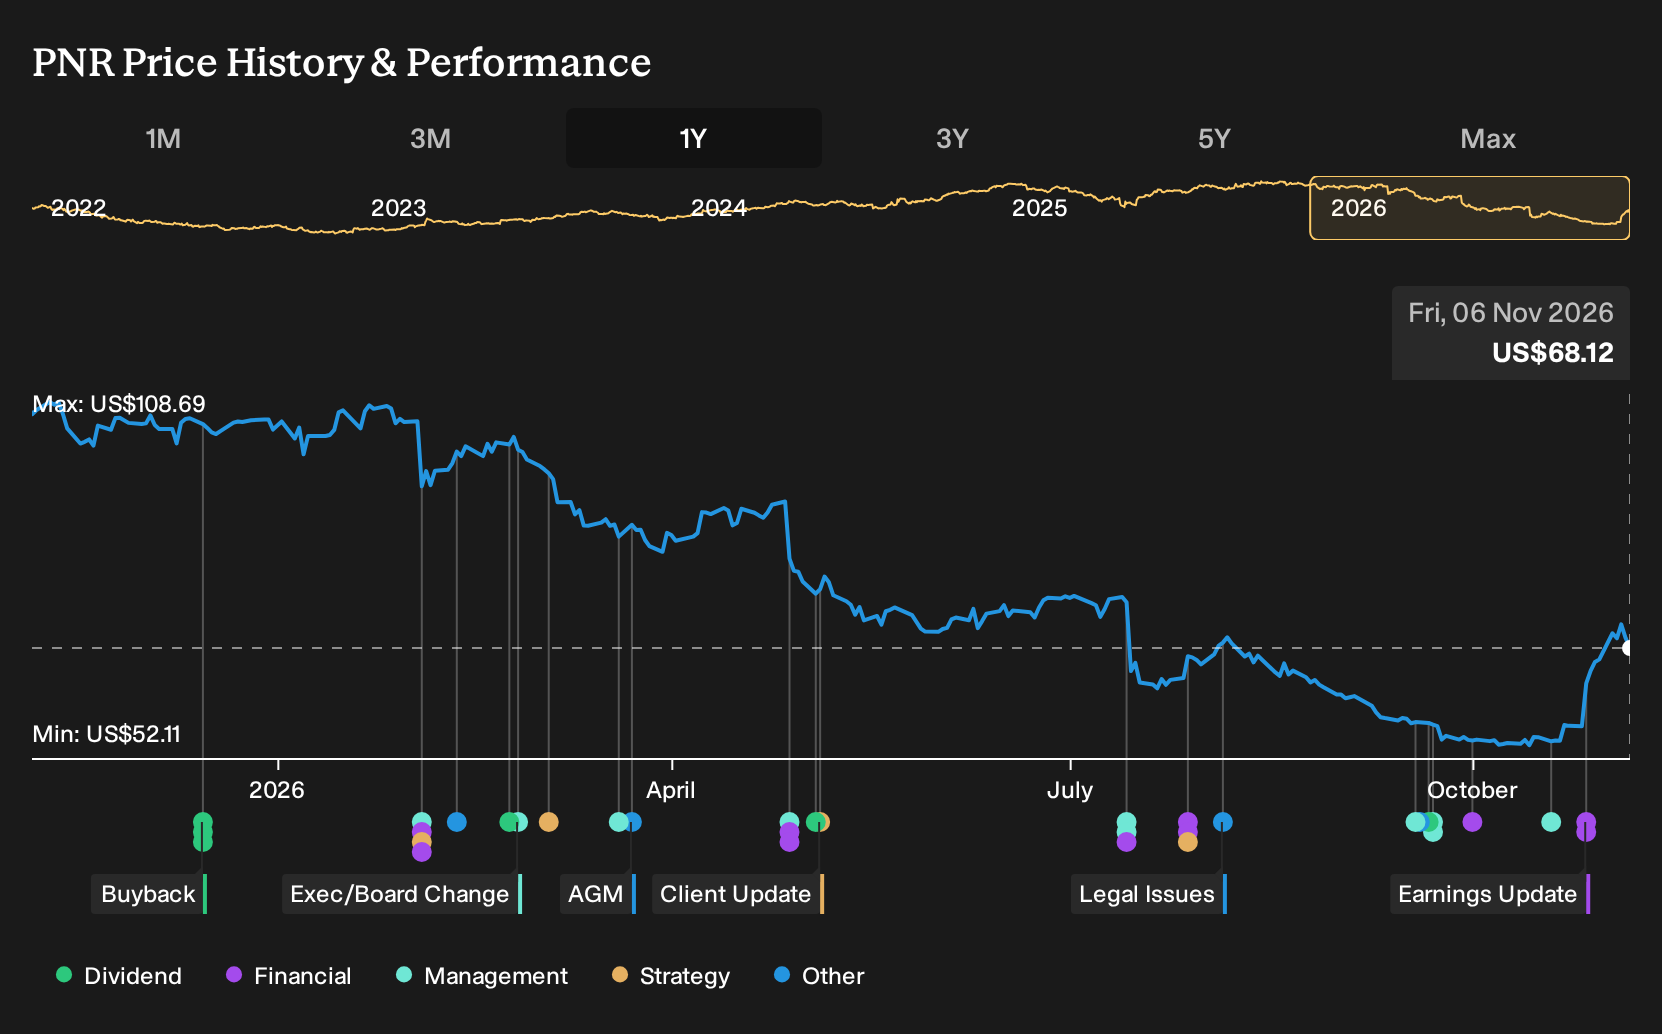
Exploring Other Perspectives
Some of the most optimistic analysts focus on Pentair’s recurring revenue potential instead of Pool volatility. Before this earnings update, the bullish camp was modelling roughly US$5.6b of revenue and about US$1.1b of earnings by 2029. That is a much richer earnings path, and this new guidance may prompt you to reassess which story feels more realistic.
Explore 4 other Pentair fair value estimates, including one that suggests as much as 59% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Pentair research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pentair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pentair's overall financial health at a glance.
Looking For More Ideas Beyond Pentair?
Once you have a view on Pentair, it can help to set it alongside other opportunities and see how it stacks up on income, quality and risk.
- For investors who want income working harder, shortlist companies with robust payouts by scanning a curated 8 dividend fortresses that filters for higher yield and resilience.
- If capital preservation sits higher on your list, compare Pentair with a 29 resilient stocks with low risk scores that filters for sturdier balance sheets and lower volatility profiles.
- When you want quality businesses that are not yet crowded trades, search through a 19 high quality undiscovered gems that spotlights strong fundamentals with less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com