


EN
Raised 2026 Guidance Could Be A Game Changer For Public Storage Stock (PSA)
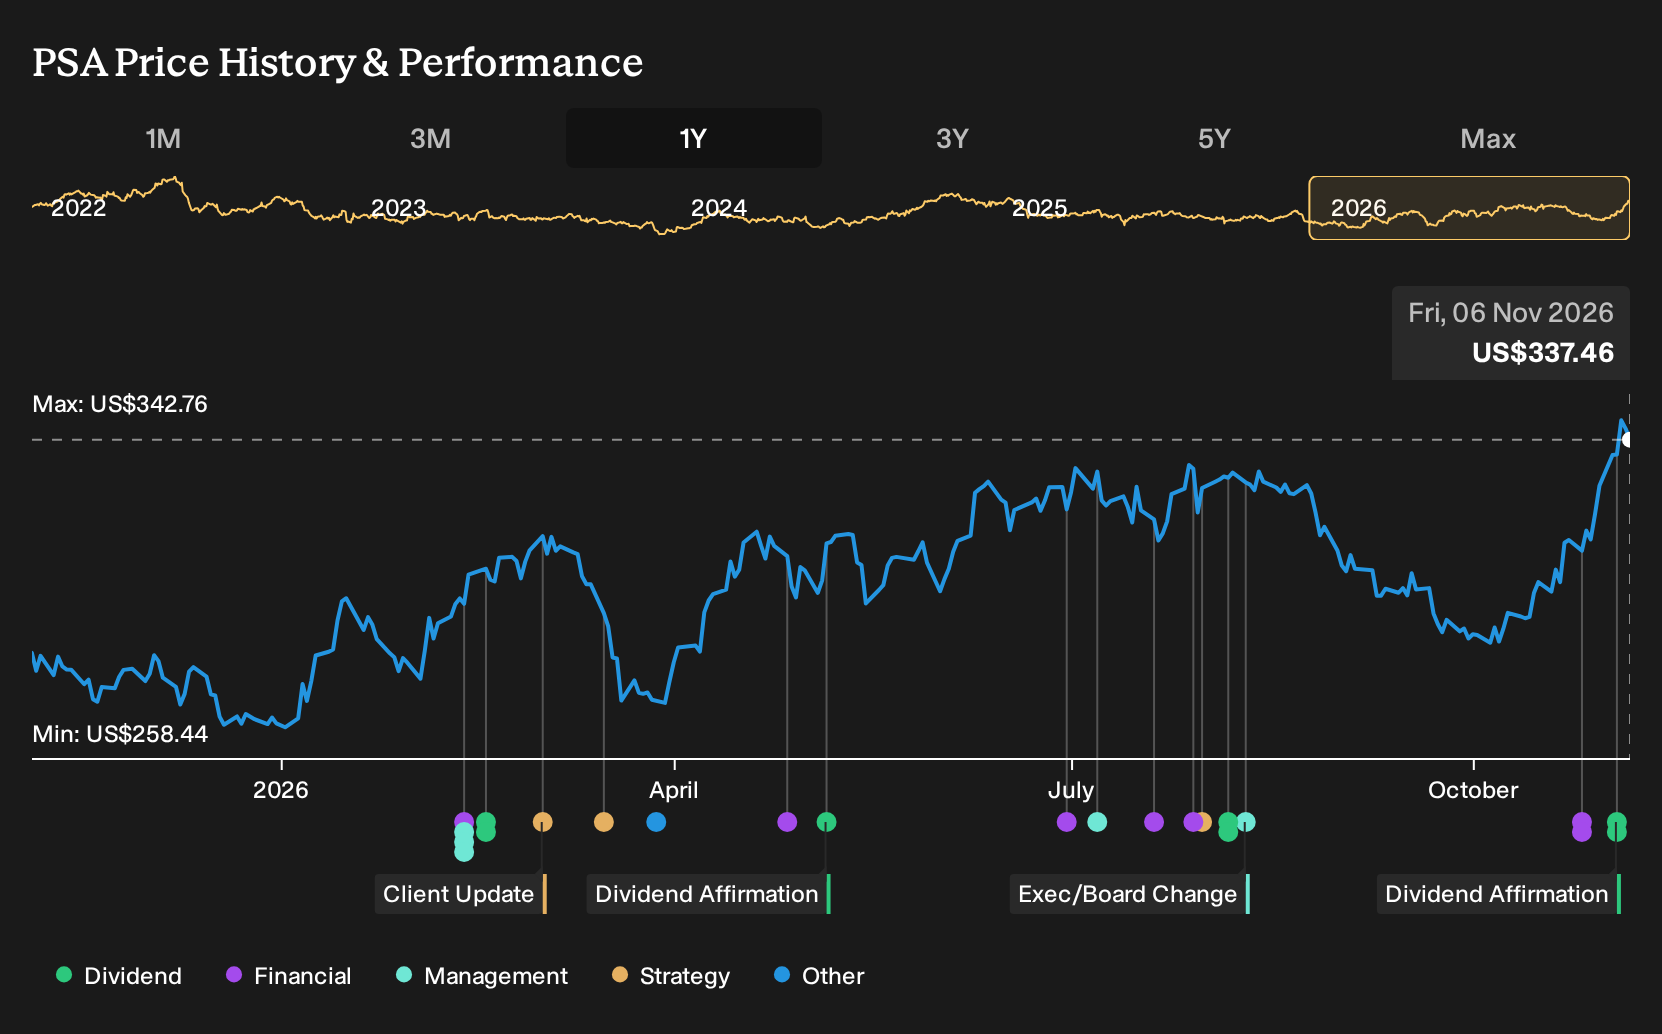
- Public Storage reported third quarter 2026 results showing higher sales and revenue than a year earlier, while quarterly net income and earnings per share declined, and the board affirmed a regular US$3.00 quarterly dividend alongside preferred dividends declared for late 2026 payments.
- The combination of softer quarterly profitability with raised full year 2026 guidance for net operating income and revenue highlights management’s confidence in the underlying storage platform and in its ability to keep cash flows supporting ongoing common and preferred dividends.
- We will now look at how Public Storage's raised 2026 guidance could influence the existing investment narrative around scale and execution.
Scan beyond Public Storage and see how other real estate players with steady payouts and measured guidance updates stack up using our curated screener of 8 dividend fortresses.
Public Storage Investment Narrative Recap
To own Public Storage, you need to believe its scale, portfolio additions and operating platform can keep cash flows relatively steady through mixed regional trends. The raised 2026 guidance for net operating income and revenue points to some easing pressure on the core portfolio, although Sunbelt softness and lower quarterly earnings keep execution under close scrutiny.
The key near term swing factor is whether integration of recent acquisitions and PS Next efficiency efforts visibly support margins as supply normalizes in weaker markets. The biggest risk is that Sunbelt and other challenged metros remain soft for a longer period, which could limit pricing power and make dividend coverage and deleveraging harder to balance.
The November 3 decision to affirm a US$3.00 quarterly common dividend sits at the intersection of those catalysts and risks. Public Storage is relying on its operating platform and cash generation to continue regular distributions, even after a quarter where net income and earnings per share were lower than a year ago.
For you as a shareholder, that commitment keeps the dividend central to the thesis. The payout adds pressure on management to deliver the raised 2026 net operating income and revenue guidance, integrate the National Storage Affiliates and Public Storage Canada portfolios cleanly and manage leverage so distributions feel supported rather than stretched.
Public Storage's current analyst narrative points to revenues of US$6.0b and earnings of US$2.1b by 2029, based on assumed yearly revenue growth of 6.7% and an earnings increase of about US$300m from US$1.8b today.
Discover how Public Storage's fair value indicates a 3% potential downside to its current price. This suggests a premium that may not be sustainable.
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, Public Storage sits in a wide band from US$329 to about US$412 per share. That spread underlines how far private investors can differ, especially with raised 2026 guidance, alongside ongoing Sunbelt and integration risks. Use it as a prompt to explore many viewpoints.
Explore another Public Storage fair value estimate, including one that suggests it could be worth just $329.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Public Storage research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Public Storage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Public Storage's overall financial health at a glance.
Looking for more investment ideas beyond Public Storage?
Once you have a view on Public Storage, it can help to compare it with other opportunities that match your income, quality, or risk preferences using the Simply Wall St Screener.
- For investors who want income paired with size and resilience, start with a curated group of higher yielding payers through 8 dividend fortresses.
- If capital preservation matters to you as much as upside, narrow the universe to sturdier balance sheets by checking the list of solid balance sheet and fundamentals (24 results).
- When you are hunting for overlooked opportunities with stronger fundamentals, widen your research funnel using a focused set of potential outliers via 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com