


EN
IonQ (IONQ) Stock Looks Above Fair Value On Current Earnings
IonQ has been on a wild multi year ride in quantum computing, and the question now is whether the current share price lines up with what its earnings can reasonably support. Recent gains around record revenue headlines and high profile partnerships put that earnings test front and center for anyone looking at the stock today.
- The share price has returned about 206% over three years, which puts a lot of weight on whether the underlying earnings story can keep carrying that kind of move.
- Record recent revenue, a larger contracted backlog and new deals around its Superion 256 systems can feed higher expectations for future profitability, which matters directly for how investors judge the earnings multiple today.
- There is a second opinion on IonQ worth weighing. See what analysts think IonQ's shares could be worth.
The issue now is whether IonQ's current valuation can be justified by its earnings power once you look past the headlines and focus on what the business is actually producing.
If you want to pressure test this earnings story against a wider set of quantum-focused plays, line IonQ up next to 25 quantum computing stocks.
Does IonQ Look Pricey on Earnings?
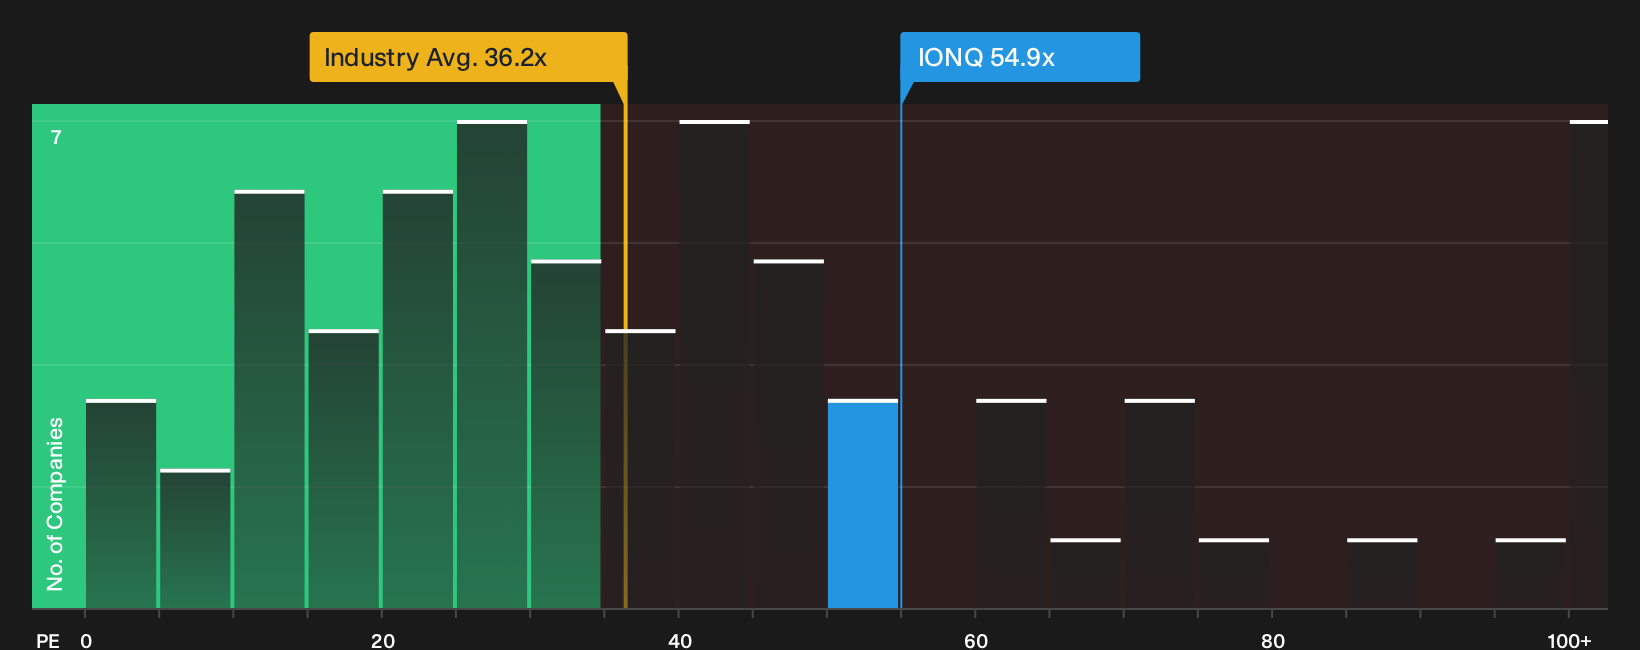
P/E is the cleanest lens here because IonQ has reported earnings that can be compared directly with its share price. On that basis, the stock trades on about 54.9x earnings, which is not only above the broader semiconductor sector at roughly 36.2x but also ahead of a peer set closer to 48.1x. That kind of premium means you are paying more per dollar of current profit than is typical even for this industry.
On record Q3 revenue headlines and big ticket Superion 256 contracts, the valuation screen still flags the shares as overvalued relative to a tailored fair multiple that reflects IonQ's size, margins and risk profile. The current P/E sits above what that model suggests as a more grounded level, so the recent enthusiasm is already baked into the tag investors are asked to pay today. To see how wide that gap runs in hard numbers, you can benchmark the live multiple against the fair value range in more detail. Explore the numbers behind IonQ's P/E valuation.
The IonQ Narrative: What Would Justify Today's Price?
IonQ Narratives pick up where the valuation puzzle leaves off and explain which paths for future growth, margins and earnings would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today on Simply Wall St's Community page. Each scenario links a fair value to a particular mix of potential catalysts and key risks so you can track over time which story, if any, is actually unfolding.
IonQ splits opinion sharply, with one group treating it as a future inflection story and the other focused on how far sentiment runs ahead of the current accounts.
Bull case: 62% undervalued
"IonQ has systematically de-risked its thesis, and is now fully funded to execute a 'winner-take-all' land grab, positioning it as the potential 'Nvidia of Quantum'..."
Discover why this Narrative puts IonQ at 62% undervalued.
Bear case: 545% overvalued
"At current prices, IonQ trades at well over 100 times revenue, a level rarely sustained even among the fastest growing technology companies..."
Explore why this Narrative puts IonQ at 545% overvalued.
IonQ's valuation still leaves one crucial angle unanswered
Price multiples only show where IonQ is today, while the published models on where analysts see its revenue, margins and earnings a few years out offer a very different lens on what could lie ahead. Explore where analysts expect IonQ to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com