


EN
Why Cloudflare Stock Is In Focus After An Earnings Beat
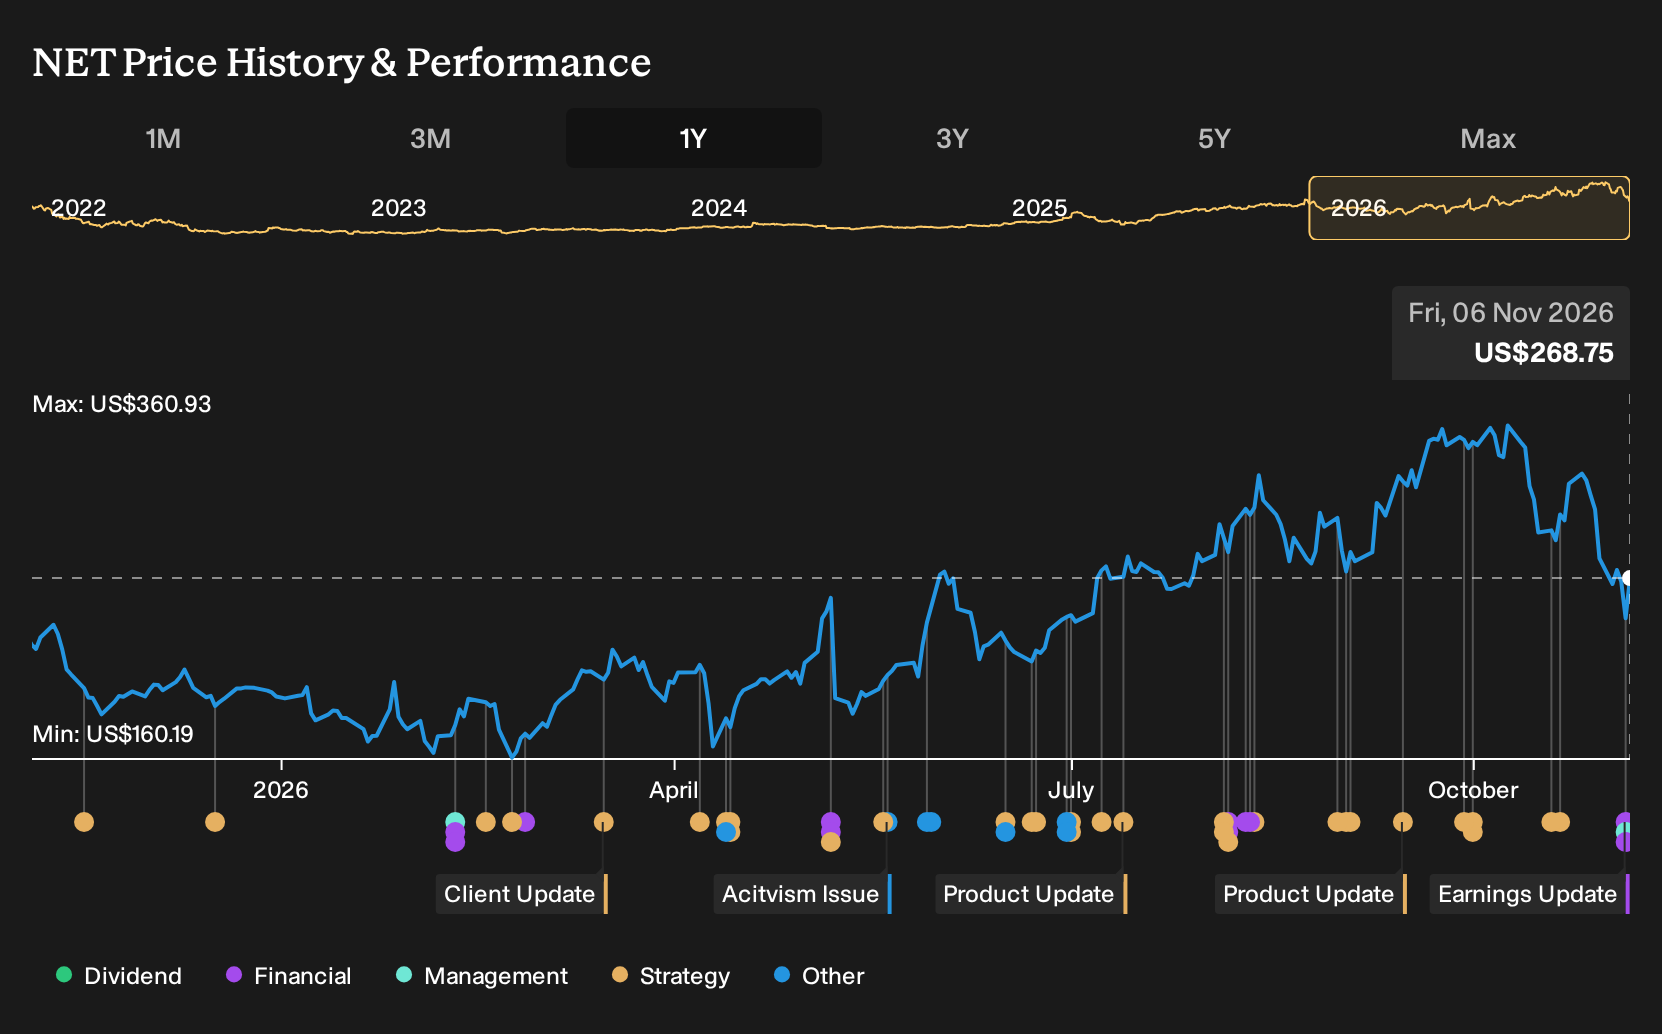
- Cloudflare reported third quarter 2026 revenue of US$782.51 million and a net loss of US$34.07 million, and raised guidance for the fourth quarter and full year on the back of strong enterprise demand and AI driven workloads.
- The appointment of Christian Smith as President of Revenue signals a push to scale Cloudflare’s go to market engine, with his background in transforming software businesses toward recurring, cloud based revenue models.
- We will now look at how Cloudflare’s raised 2026 guidance might reshape the existing investment narrative around growth and profitability.
Cloudflare Investment Narrative Recap
For Cloudflare, the big picture thesis is about a large, global platform for security, networking, and developer services that can keep attracting more enterprise workloads, including AI heavy use cases. The recent quarter supports that demand story, with Q3 2026 revenue of US$782.51 million, raised full year guidance, and a strong contribution from large customers.
The trade off sits in the income statement. Losses widened, with a Q3 net loss of US$34.07 million and US$226.97 million across the first nine months of 2026, while gross margin pressure and higher cost of revenue remain real. In the near term, the key catalyst is execution on AI and developer platform adoption, and the biggest risk is profitability stalling as investments in network capacity and AI workloads keep costs elevated.
The appointment of Christian Smith as President of Revenue is the clearest operational announcement tied to this earnings update. He inherits a business that just raised revenue guidance for Q4 2026 to US$845 million to US$846 million and for the full year to just under US$3 billion, largely on enterprise and AI related demand. That puts the go to market engine right at the center of what happens next.
Smith’s background at Splunk and Cisco, where he worked on scaling recurring cloud revenue and complex enterprise sales, directly links to Cloudflare’s current catalysts around zero trust, SASE, and developer products like Workers AI. The transition risk is that any disruption in large deal execution or sales productivity would hurt a company already carrying ongoing net losses and customer concentration exposure, at a time when the stock trades on a rich price to sales multiple and investor expectations leave limited room for missteps.
Cloudflare's narrative projects US$5.4b revenue and US$582.7 million earnings by 2029. This implies 28.7% yearly revenue growth and an earnings increase of about US$789 million from earnings today of a US$206.3 million loss.
Uncover why Cloudflare's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bearish angle focuses on valuation risk. Before this Cloudflare update, the lowest analysts were working off roughly US$5.1b of 2029 revenue and about US$388.6 million of earnings, and some even modeled losses. Those forecasts paint a much tougher path, so use this earnings news to test several different narratives for yourself.
Explore 7 other Cloudflare fair value estimates, including one that suggests as much as 38% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own judgment.
- A great starting point for your Cloudflare research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cloudflare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cloudflare's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cloudflare?
Cloudflare may be front of mind after this update, but your portfolio outcomes often hinge on what you do with the next few decisions. The Simply Wall St screener can help you quickly sort through hundreds of alternatives so you are not relying on a single story or sector to carry all the weight.
- If resilience matters most to you, start by reviewing 29 resilient stocks with low risk scores that score well on both balance sheet strength and volatility.
- If cash generation and financial footing are your priority, focus on the list of solid balance sheet and fundamentals (24 results) to find businesses with room to fund growth and withstand shocks.
- If you are hunting for opportunities the market may have skipped over, filter through the 19 high quality undiscovered gems that combine quality fundamentals with relatively low attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com