


EN
How Strong Earnings And A Dividend Increase At NBT Bancorp (NBTB) Has Changed Its Investment Story
- NBT Bancorp reported third quarter 2026 results with higher net interest income of US$142.08 million and net income of US$58.03 million, and its board approved a fourth quarter cash dividend of US$0.40 per share to be paid on December 15, 2026.
- The 8.1% uplift in the quarterly dividend, marking a fourteenth consecutive year of annual increases, reflects management confidence in NBT Bancorp's earnings profile and cash generation from its core lending and fee businesses.
- We will now explore how NBT Bancorp's higher earnings per share and larger dividend may influence the longer term investment narrative.
See how NBT Bancorp's latest dividend move compares with other income-focused opportunities by reviewing the hand picked 8 dividend fortresses across the market.
NBT Bancorp Investment Narrative Recap
NBT Bancorp appeals to shareholders who believe its regional focus, fee income mix and conservative balance sheet can keep earnings relatively steady through cycles. The immediate swing factor is whether loan demand in its Northeast footprint and contributions from newer markets like Western New York stay firm enough to support net interest income and fee lines without stretching credit.
The big risk is cost creep and tech execution. If digital investments and branch integration work out slower than expected, expenses could outrun revenue and erode efficiency. The latest quarter does not radically change that equation, since credit costs and net charge offs are broadly stable and the business mix remains similar.
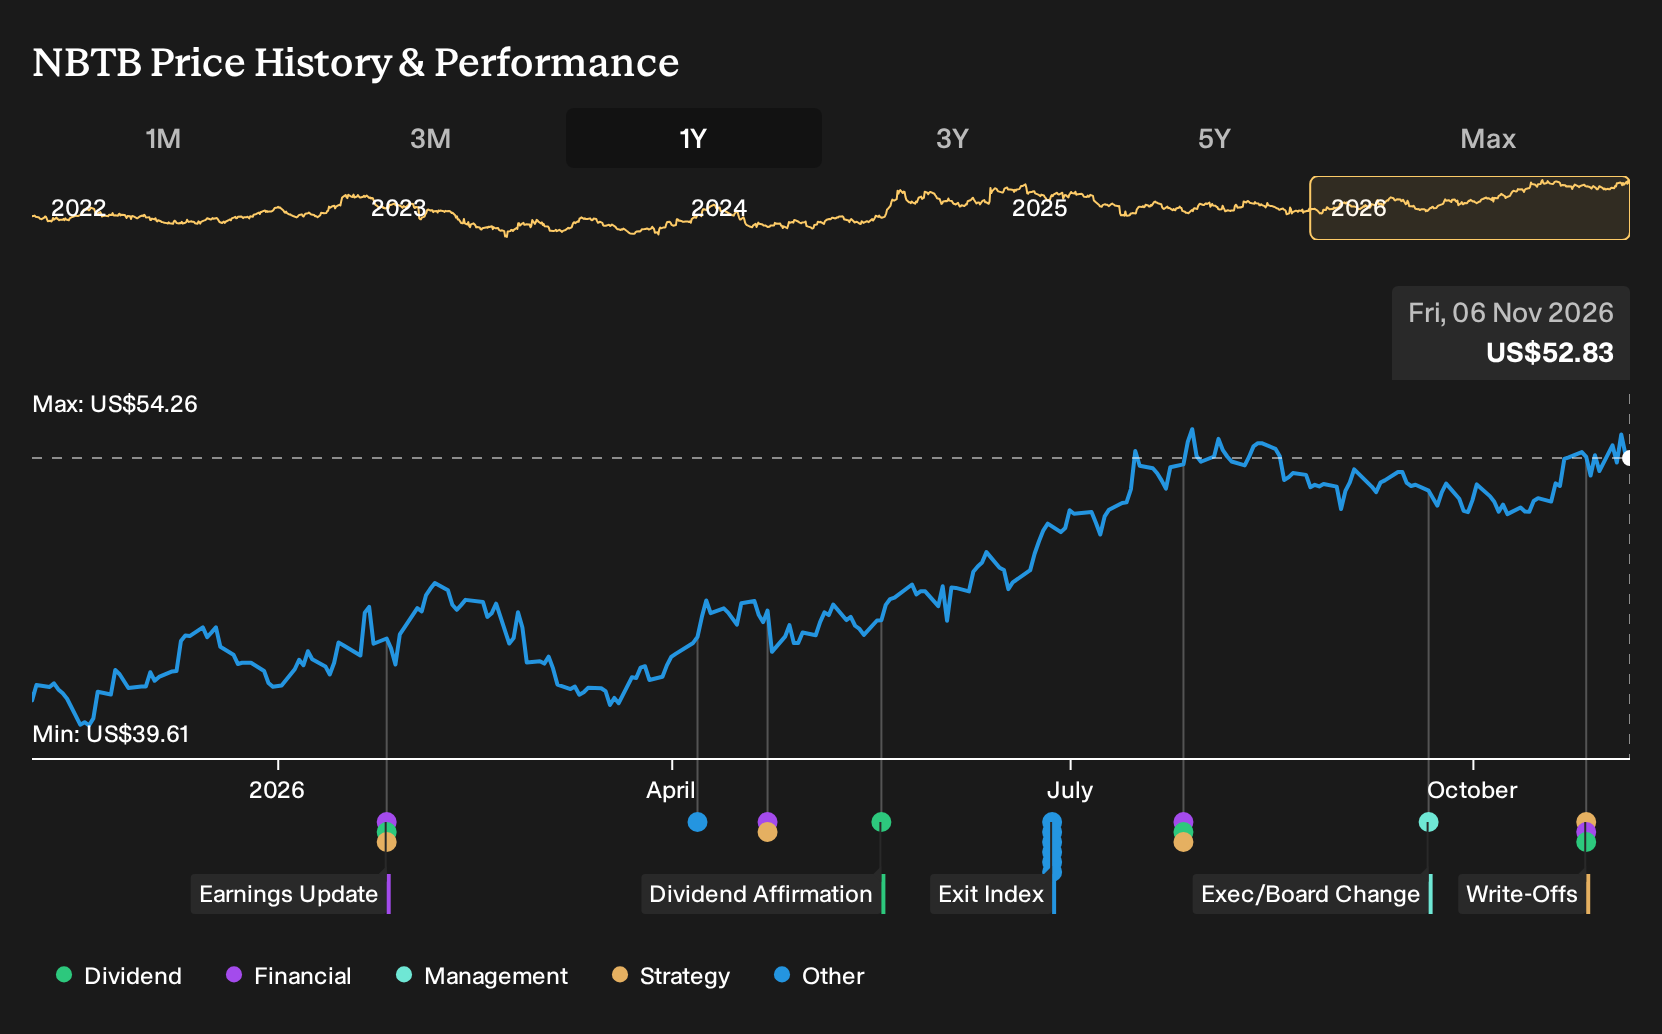
The fourth quarter dividend increase to US$0.40 per share is the clearest signal tied to this earnings update. Fourteen straight years of annual dividend growth, supported by higher net income and earnings per share in the first nine months of 2026, indicate a capital return approach that leans on internally generated funds rather than aggressive balance sheet moves.
For you as an investor, that higher payout fits directly into the current catalyst discussion. If NBT Bancorp can keep growing fee based lines such as wealth and insurance while holding charge offs near recent levels, the stock’s appeal will likely hinge on the mix of income and perceived value. If regional growth or digital adoption underwhelm, that same dividend could limit flexibility just as costs or credit pressure the story.
NBT Bancorp's current earnings of US$214.2 million are set against analyst expectations for earnings of US$269.0 million by 2029. This implies an earnings increase of about US$54.8 million and aligns with forecasts that revenues could reach US$891.4 million by the same year, alongside a projected 7.2% yearly revenue growth rate.
Uncover how NBT Bancorp's fair value indicates an 8% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Community members on Simply Wall St put fair value for NBT Bancorp anywhere between about US$56.8 and US$90.1 across 2 separate estimates, which already shows how wide opinions can run. Set that against ongoing digital spending, Western New York expansion and Micron linked exposure, and you have several moving parts worth cross checking with alternative views.
Explore another NBT Bancorp fair value estimate, including one that suggests it could be worth just $56.83.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NBT Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for NBT Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NBT Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond NBT Bancorp?
Once you have formed a view on NBT Bancorp, it can help to compare that thesis with other companies that share similar qualities or offer a different balance of risk and income. The Simply Wall St Screener makes that process quicker by letting you filter for very specific traits instead of sifting through the whole market on your own.
- For investors who want income with staying power, focus on companies that appear able to support their payouts over time by scanning the 8 dividend fortresses.
- If capital preservation ranks high on your list, concentrate on businesses with stronger finances and lower risk profiles by reviewing the 29 resilient stocks with low risk scores.
- To widen the opportunity set beyond well covered companies, look across the market for quality that has less attention by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com