


EN
Enphase Energy (ENPH) Could Be 30% Undervalued Following Weaker Earnings And IQ SST Progress
Enphase Energy (ENPH) is back in focus after a sharp year over year drop in earnings and fresh fourth quarter guidance, along with a new milestone for its IQ Solid-State Transformer aimed at data center power conversion.
Markets have reacted sharply to the weaker earnings and new guidance, with Enphase Energy now trading at US$28.47 after the share price fell 15.03% over the past 30 days and 32.02% over 90 days, while the 1‑year total shareholder return declined 5.81% and the 3‑year total shareholder return dropped 63.50%. This signals fading momentum even as the IQ SST progress keeps the long term story in play for investors focused on data center power and AI demand.
Look beyond Enphase Energy to discover additional power and AI infrastructure opportunities moving on similar themes with our curated 52 AI infrastructure stocks
The sharp reset in Enphase Energy’s share price after weaker earnings and fresh guidance now collides with the IQ SST data center story. Does that mix still tilt the risk reward toward new buyers or caution?
Most Popular Narrative: 30% Undervalued
Against Enphase Energy’s last close at $28.47, the most followed narrative points to a fair value of $40.58 that implies a sizable valuation gap and leans on a slower, but still constructive, recovery story in residential solar and new products.
Upcoming launches of next generation hardware including the IQ Battery G5 with roughly 50% higher energy density at about 40% lower cost per kWh, the IQ Vault 80 kWh commercial storage system and IQ9 microinverter families are expected to lower unit costs and widen the range of addressable residential and small commercial projects. This can support both revenue growth and gross margin resilience.
See why 147 investors see Enphase Energy as 30% undervalued.
Result: Fair Value of $40.58 (UNDERVALUED)
Still, the bullish Enphase Energy story can crack if U.S. residential demand remains weak for longer and tariff or legal setbacks squeeze profitability harder than expected.
Find out about the key risks to this Enphase Energy narrative.
Another View: What The SWS DCF Model Says About Enphase Energy
While the most popular Enphase Energy narrative leans on analyst targets that point to a fair value of $40.58, the SWS DCF model lands in a very different place. Based on projected future cash flows, Enphase Energy screens as overvalued at $28.47 versus a model value of $18.94. This raises a simple question for investors: Is the story strong enough for you to pay above what the cash flow math currently supports?
Look into how the SWS DCF model arrives at its fair value.
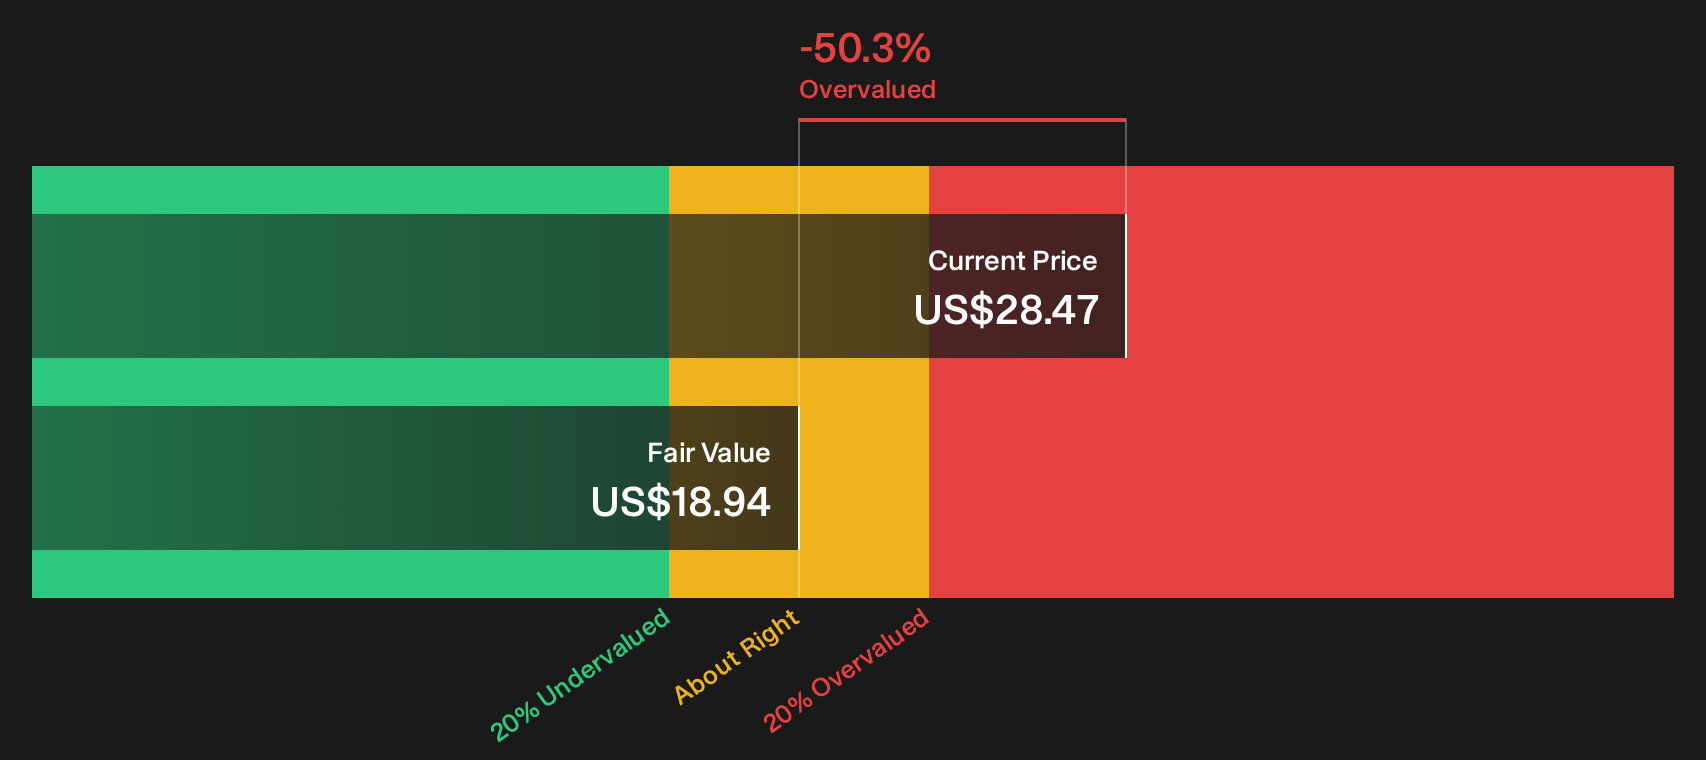
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enphase Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals can be frustrating, especially when Enphase Energy carries both clear concerns and real upside potential that investors are debating in real time. Move quickly, review the underlying data, and anchor your own stance with the 1 key reward and 2 important warning signs.
Looking For More Investment Ideas Beyond Enphase Energy?
If Enphase Energy has you rethinking where you put fresh capital, do not stop here. Broader opportunities are already lining up for you to review.
- Target resilient balance sheets by scanning companies that pass strict debt and liquidity filters with the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispriced opportunities by reviewing businesses that pair strong fundamentals with lower valuations through the 39 high quality undervalued stocks.
- Prioritise stability and income by filtering for companies focused on reliable cash returns using the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com