


EN
BILL Holdings (BILL) Beats On Earnings And Margins, Is It Still A Bargain?
What triggered the latest move in BILL Holdings?
BILL Holdings (BILL) just posted first quarter results that paired an earnings surprise and wider operating margins with a revenue figure affected by an accounting reclassification, putting its AI rollout and multiproduct traction in sharper focus for investors.
The latest rally in BILL Holdings fits into a mixed track record. The 1 month share price return of 19.11% and 90 day gain of 9.21% suggest momentum is picking up, yet the 3 year total shareholder return declined 7.21% and the 5 year total shareholder return fell 84.34%, even with a 14.96% total shareholder return over the past year and active buybacks shaping the recent move.
Surf 41 profitable AI stocks that aren't just burning cash that, like BILL Holdings, pair AI-driven products with positive earnings and active investor attention.BILL Holdings now has a cleaner profit story and a louder AI pitch after the latest quarter. The open question is whether the recent share price jump already reflects that strength or still leaves a margin of safety.
Most Popular Narrative: 8% Undervalued
BILL Holdings last closed at $52.41, while the most followed narrative pegs fair value at $57.05, using a 9.7% discount rate to weigh future cash flows against today’s price.
The main thing that has to go right is that BILL Holdings successfully executes its pivot to an integrated, AI-powered financial operations and embedded payments platform while managing the drag from Spend & Expense and bank-channel pruning.
The current valuation implies the market is heavily discounting BILL Holdings despite guidance for double-digit core revenue growth, higher non-GAAP operating margins above 23%, rising GAAP profitability, and sizeable share repurchases that reduce the share count.
See why 24 investors see BILL Holdings as 8% undervalued.
Result: Fair Value of $57.05 (UNDERVALUED)
Still, this storyline can crack if muted small business spending keeps payment volumes soft, or if Spend & Expense and bank channel pruning drag longer than expected.
Find out about the key risks to this BILL Holdings narrative.
Another View: Multiples Paint a Tougher Picture for BILL Holdings
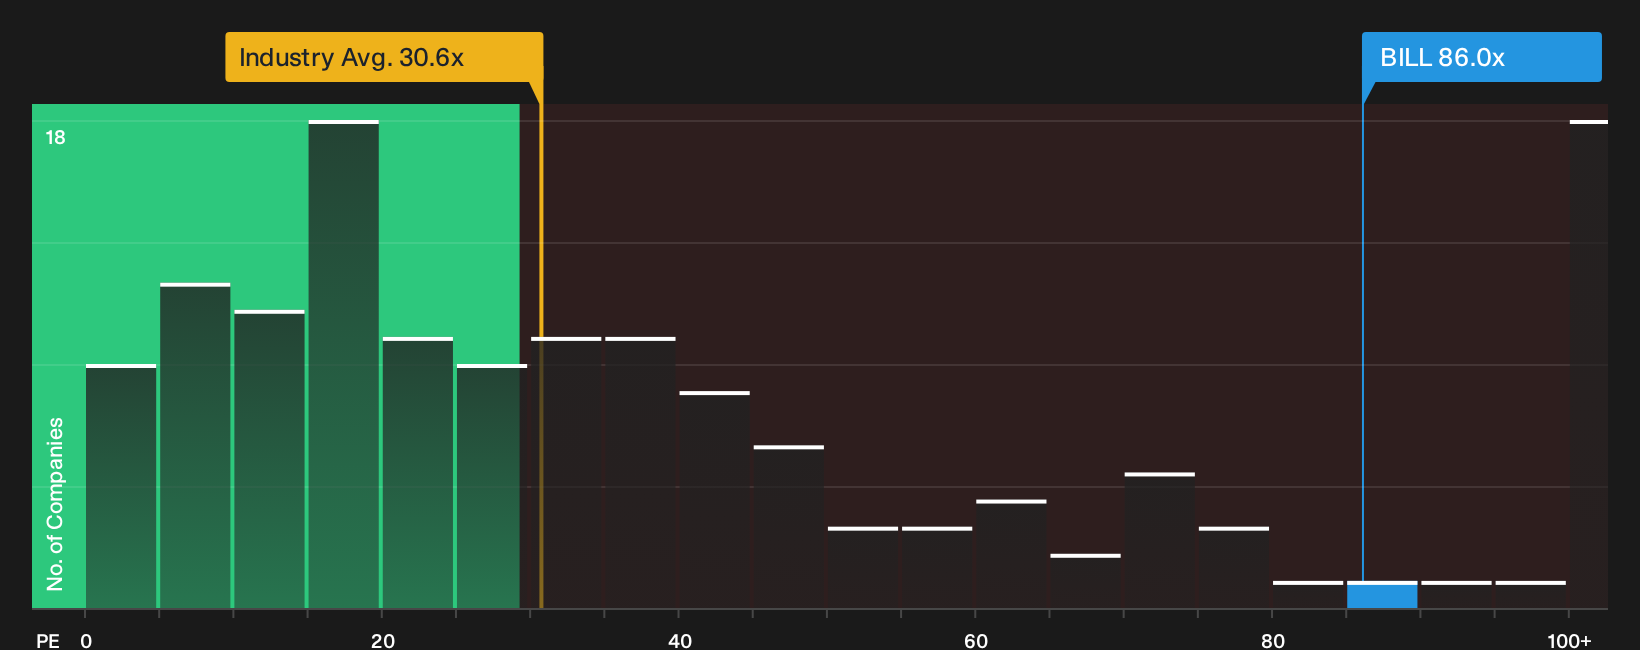
The DCF work points to BILL Holdings trading at a discount to future cash flows, yet the market is applying a rich P/E of 86x. That is higher than the US Software sector at 30.2x and far above a fair ratio of 47.2x, which hints at real de rating risk if expectations cool.
Our assessment using this earnings multiple lens underlines how sensitive BILL Holdings could be to any wobble in growth or margins, even if the long term cash flow story appears supportive. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on BILL Holdings so far. If you want to cut through the noise and form your own view quickly, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BILL Holdings?
If you stop with BILL Holdings, you risk missing other opportunities that match your style, your risk comfort, and the kind of returns you are pursuing.
- Target potential upside by scanning for quality opportunities trading below what fundamentals suggest through the 39 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient payers using the 8 dividend fortresses.
- Dial down portfolio stress by concentrating on sturdier businesses through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com