


EN
Vistra (VST) Lifts Guidance And Buyback, Is The Stock Undervalued?
Vistra (VST) just delivered record adjusted EBITDA growth on strong generation performance and higher realized prices, tightened its 2026 earnings guidance upward, introduced 2027 targets, and approved an extra US$1.5b share buyback authorization.
The latest jump in Vistra’s share price, with a 1-day share price return of 10.55% after the results, comes after a tougher stretch where the 30-day share price return is down 25.14% and the 1-year total shareholder return has fallen 34.28%. Over five years, however, the total shareholder return is up almost sixfold, which suggests that long-term momentum has been strong while shorter-term sentiment has cooled and is now reacting to the upgraded outlook and buyback plan.
Scan how other utilities and infrastructure plays are responding to similar earnings shocks and buyback moves by checking the hand picked 42 power grid technology and infrastructure stocks alongside Vistra.
Vistra now trades well below both analyst targets and one intrinsic value estimate, even after the spike. The key question is whether that gap reflects mispricing or a reset in what investors are willing to pay.
Most Popular Narrative: 58% Undervalued
The most followed narrative on Vistra pegs fair value at about $300 per share, well above the recent $124.80 close, which frames the current share price as a steep discount but also raises the bar for execution.
So, what could actually pull Vistra down after such a massive run? Is it really as invincible as it seems? Not quite, there are a few major roadblocks that could bring it back to earth.
1. Regulatory Roadblocks on Big Tech Deals. Remember those high-profile 20-year power deals with AMZN and META? Regulators like FERC and grid operators like PJM are watching co-located data centers very closely. If they step in and impose heavy transmission tariffs, grid-use fees, or strict usage rules on these setups, it directly affects Vistra's profit margins. In that case, those "guaranteed" long-term contract revenues may look much less certain.
See why 24 investors see Vistra as 58% undervalued.
Result: Fair Value of $300 (UNDERVALUED)
Still, the narrative around Vistra can crack if regulators tighten rules on long term Big Tech power deals or if hyperscaler data center spending slows meaningfully.
Find out about the key risks to this Vistra narrative.
Another View on Vistra’s Valuation
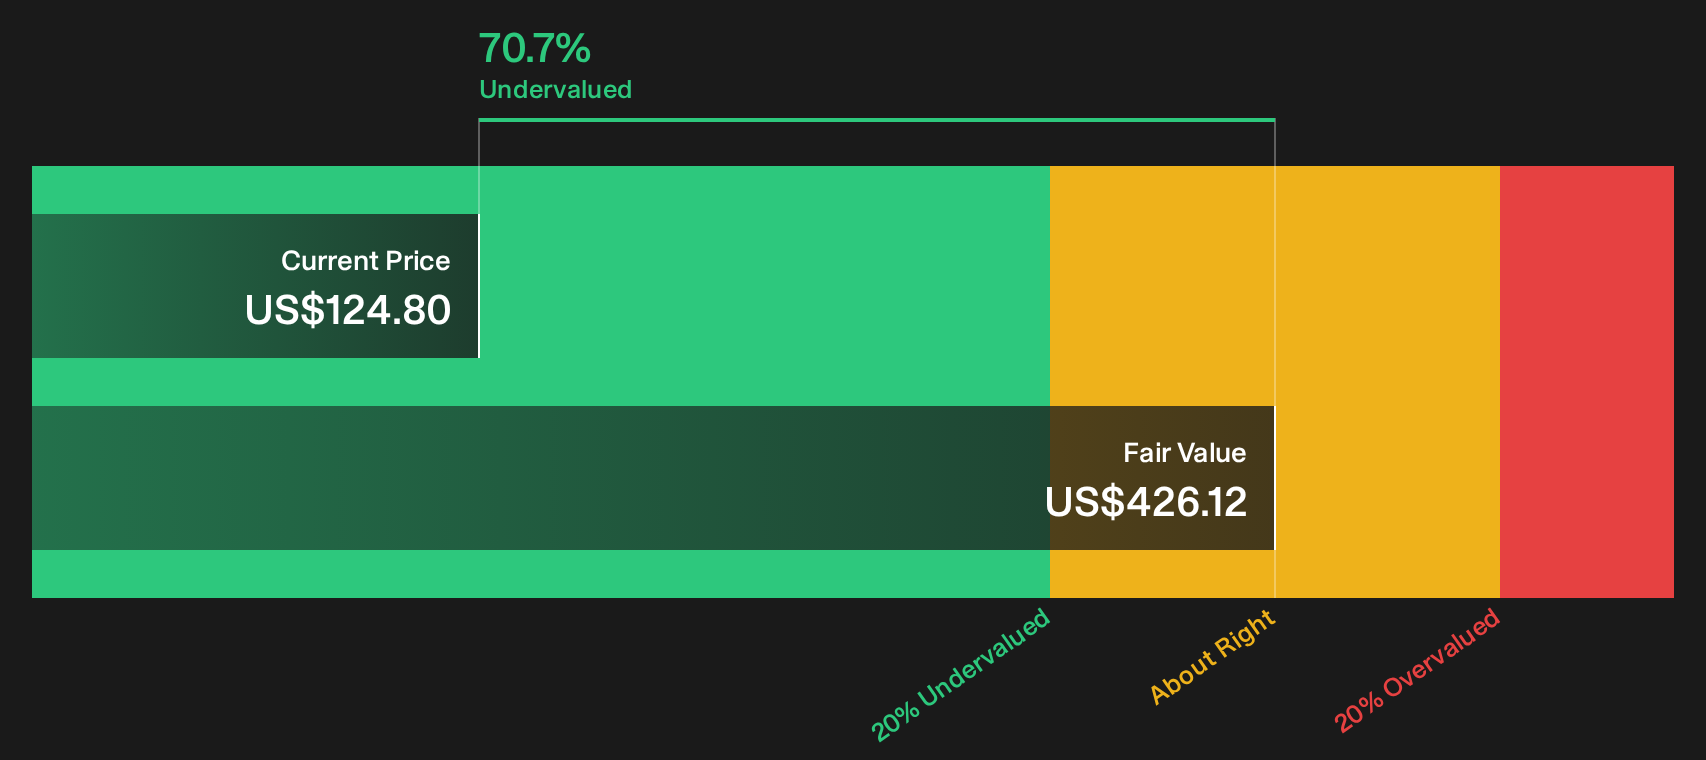
There is a very different signal coming from our DCF model. It points to a future cash flow value of about $426 per share for Vistra, which is far above the current $124.80 price and indicates the stock may be trading at a discount relative to this framework. If one framework relies on earnings multiples and another relies on long term cash generation, which approach is more appropriate for a capital intensive utility?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or clear opportunity for Vistra? Consider the situation while sentiment is still split and evaluate the narrative against the full picture of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Vistra?
If you only stop at Vistra, you could miss other opportunities that fit your goals just as well, or even better, on key fundamentals.
- Target potential mispricing by scanning companies that combine strong fundamentals with attractive valuations through the 39 high quality undervalued stocks.
- Prioritise resilience by reviewing a 29 resilient stocks with low risk scores that focuses on businesses with lower risk scores and more robust profiles.
- Hunt for overlooked opportunities by checking a 19 high quality undiscovered gems that highlights quality companies the market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com