


EN
Is MarineMax (HZO) Priced Too Richly For Its Sales?
MarineMax has had a strong run over the past year, and with the stock now around US$52.70, investors are asking whether that share price still lines up with what its sales can support. With such a move on the board and a buyout agreement in place, the core issue for anyone looking at MarineMax today is how much revenue the market is effectively paying for.
- MarineMax has delivered a 121.7% return over the past 12 months, which puts real pressure on the question of how fully its current sales power is already reflected in the price.
- The company reported US$2.2b in full year revenue and announced a planned US$1.5b acquisition by Safe Harbor, which can reshape how investors think about future scale, margins and the value they place on each dollar of sales.
- The analysts covering MarineMax have run their own numbers. See what analysts think MarineMax's shares could be worth.
The stock's next move may depend on whether the current valuation can be explained by MarineMax's sales when measured against the Fair Ratio benchmark.
If you are weighing whether MarineMax's price still lines up with its sales, it can help to compare it with a wider set of companies screened for our screener containing 19 high quality undiscovered gems.
Does MarineMax Look Pricey on Sales?
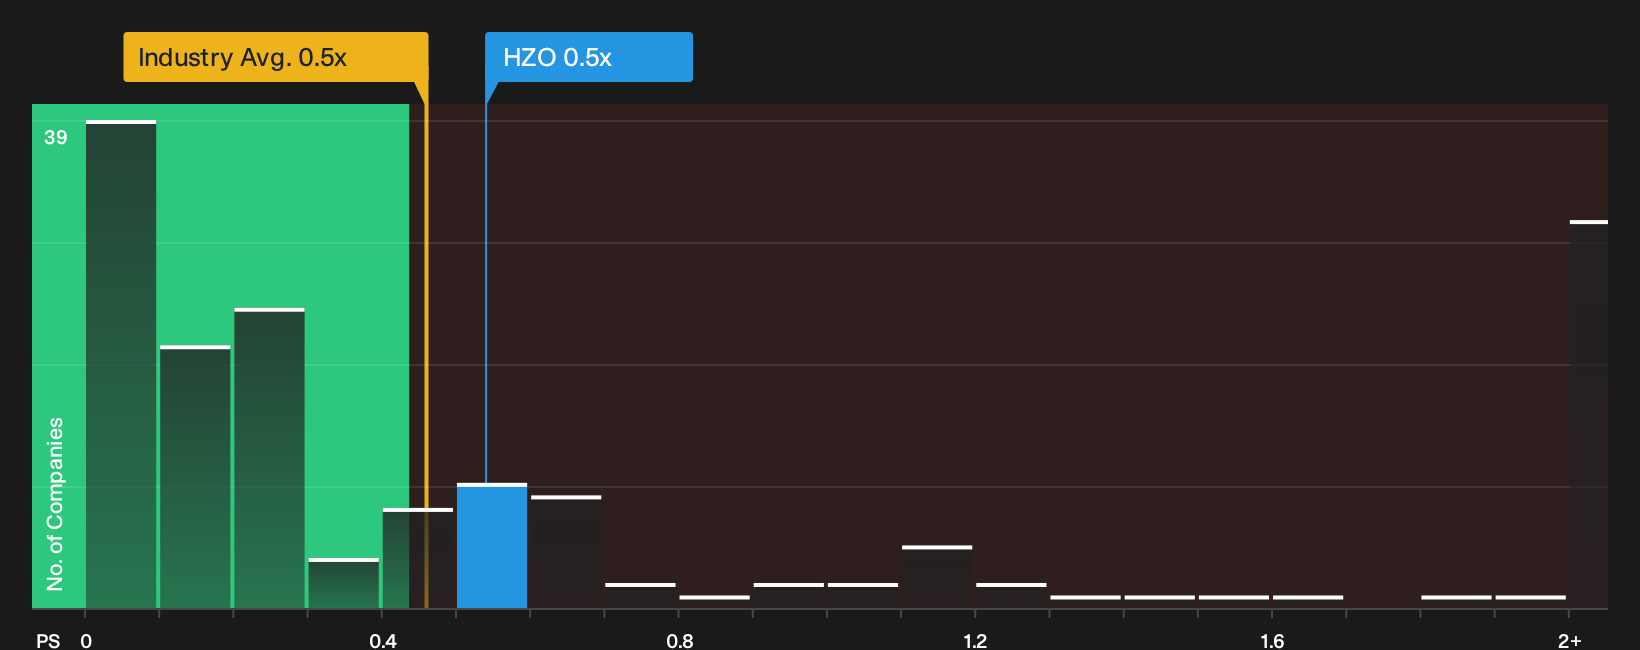
P/S works well for MarineMax because the focus today is squarely on how much investors are paying for each dollar of sales rather than earnings swings. On this lens, the stock trades on a P/S of about 0.5x, which is below the Specialty Retail industry average of roughly 0.5x and far below the peer group at about 2.9x. Despite the planned US$1.5b sale to Safe Harbor, the market is still pricing MarineMax’s revenue base at a clear discount to similar businesses on this simple sales yardstick.
The Fair Ratio framework, which links an appropriate P/S to MarineMax’s margins, scale, sector and risk profile, points to the current 0.5x multiple being above what that tailored model would suggest. That implies the share price already bakes in a richer value per dollar of revenue than this benchmark would support, even if headline comparisons against peers and the sector look cheap at first glance. Explore the numbers behind MarineMax's P/S valuation.
The MarineMax Narrative: What Would Justify Today's Price?
Narratives on MarineMax pick up where this valuation puzzle leaves off, by explaining which paths for future growth, margins and earnings would need to unfold for the stock to be worth materially more or less than it is today. Each scenario links MarineMax's potential catalysts and key risks to a specific estimate of fair worth, so you can monitor over time which version of the story seems to be taking shape on Simply Wall St's Community page.
MarineMax splits opinion in the community, with one camp seeing more to like at current levels than the other.
Bull case: roughly fairly valued
"The New Wave Innovations portfolio, particularly Boatyard with 47% active subscriber growth in the March 2026 quarter, gives MarineMax a growing digital channel..."
Discover why this Narrative puts MarineMax at roughly fairly valued.
Bear case: 51% overvalued
"Management now expects fiscal 2026 same-store sales to fall roughly in line with industry unit volumes that could end down as much as the mid single digits..."
Explore why this Narrative puts MarineMax at 51% overvalued.
MarineMax’s valuation still leaves one big angle unresolved
The numbers you have seen reflect today’s share price against current sales, while a separate layer of broker models sketches where this business might be a few years from now. Explore where analysts expect MarineMax to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com