


EN
How Raised EBITDA Guidance Will Impact Pembina Pipeline Stock Investors
- Pembina Pipeline reported Q3 2026 results that included CAD 2,179 million in sales, CAD 570 million in net income, and basic earnings per share from continuing operations of CAD 0.92, alongside a fourth quarter 2026 dividend declaration of $0.735 per share.
- The quarter highlighted how fee based infrastructure, strong Asian propane pricing, and nearly CAD 3 billion of sanctioned projects, including the Greenlight Electricity Centre and Pacific Link pipeline participation, are reshaping Pembina Pipeline's earnings mix and long term capital commitments.
- We will now look at how Pembina Pipeline's raised 2026 adjusted EBITDA guidance could influence the investment narrative built around contracted growth.
Pembina Pipeline Investment Narrative Recap
To own Pembina Pipeline, you need to be comfortable with a fee based infrastructure story that leans on steady cash flows and a long list of committed projects. The raised 2026 adjusted EBITDA guidance to a range of $4.45b to $4.55b supports that thesis in the near term and ties directly to execution on contracted volumes and export optionality.
The main short term swing factor is how reliably those large capital projects move from spend to cash generation without pushing leverage to the top of the 3.5x to 4.25x range. The biggest risk remains cost or schedule strain on Cedar LNG, Greenlight and pipeline expansions in a still demanding regulatory and funding backdrop.
The most relevant update for this quarter is Pembina Pipeline’s decision to lift 2026 adjusted EBITDA guidance after reporting Q3 2026 adjusted EBITDA of $1.128b, up 9% year on year. That guidance range of $4.45b to $4.55b sits alongside almost $3b of sanctioned projects that are intended to support contracted EBITDA through 2030.
For you, that guidance change frames both the opportunity and the pressure points. Strong Asian propane pricing and export infrastructure help the catalyst side by improving current earnings power. Execution risk on big builds such as the Greenlight Electricity Centre and Pacific Link pipeline, along with toll resets on regulated systems, continue to anchor the downside case.
Pembina Pipeline's current analyst narrative points to revenue of CA$8.8b and earnings of CA$2.2b by 2029, based on an assumed 3.5% yearly uplift in sales and an earnings increase of about CA$500m from CA$1.7b today.
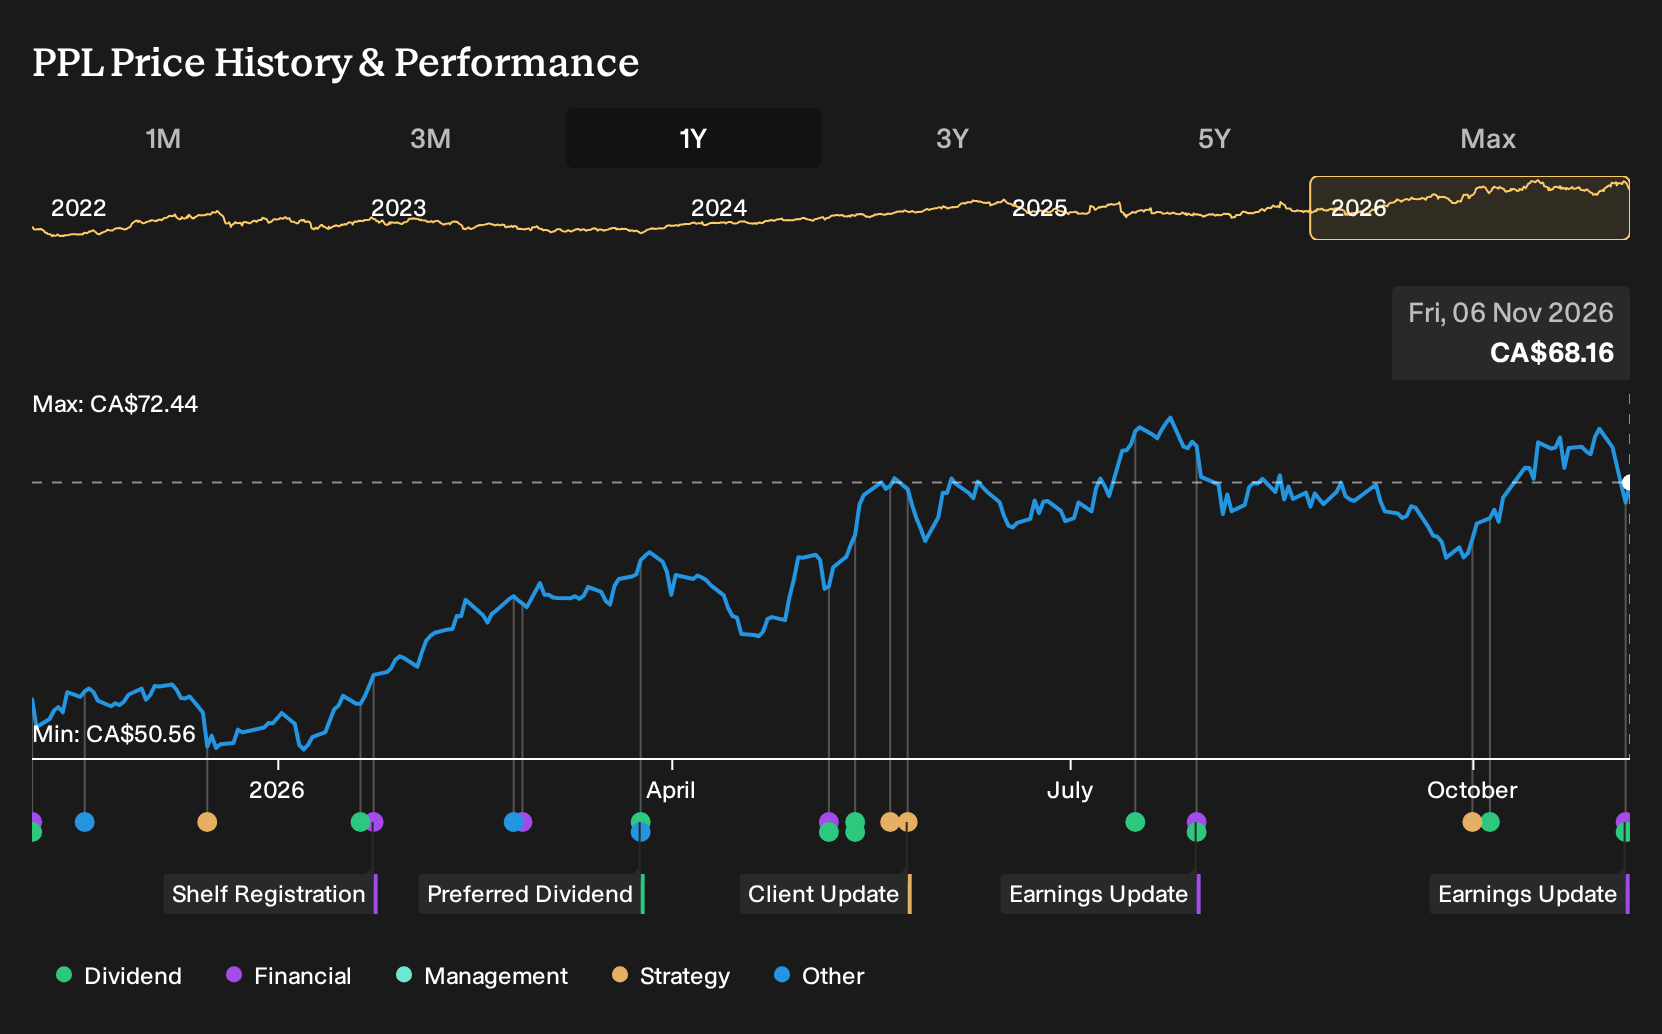
Uncover why Pembina Pipeline's fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from $73 to about $239, so opinions on Pembina Pipeline are spread widely. You see that divergence most during periods of heavy project spending, when some focus on dividend continuity and sanctioned projects as potential catalysts, while others concentrate on toll resets and regulatory risk. Explore those competing views before sizing any position.
Explore 2 other Pembina Pipeline fair value estimates, including one that suggests potential upside of as much as 251% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pembina Pipeline research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pembina Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pembina Pipeline's overall financial health at a glance.
Looking for more investment ideas beyond Pembina Pipeline?
Once you have formed a view on Pembina Pipeline, it often helps to benchmark that thinking against other income and quality focused opportunities using the Simply Wall St screener tools.
- If capital preservation sits high on your list, scan a curated set of resilient companies through the 9 resilient stocks with low risk scores and see which ones line up with your risk tolerance.
- If you want yield backed by healthy finances, start with a list of solid balance sheet and fundamentals (5 results) that filters for steady payers supported by stronger balance sheets.
- If you are hunting for less crowded opportunities, widen your search to a 7 high quality undiscovered gems that surfaces under-the-radar businesses with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com