


EN
NVIDIA And 2 Other Top Value Stocks
Wall Street just watched an all in bet on AI unwind, with a $3.2tn tech sell off reminding investors that hype can reverse fast while cash flow and balance sheet strength still matter. That reset creates room for solid, underappreciated businesses to be mispriced. This article highlights three financially resilient, out of favor US stocks that appear inexpensive on our quality and value framework, and explains why they merit a closer look now.
The three stocks below are just a starting sample. Our full high quality undervalued screen surfaces 36 more companies that share similar cash flow strength, balance sheet discipline, and mispriced narratives that this article does not cover.
To identify your own highest conviction ideas, head straight into the High Quality Undervalued Stocks screener to filter, analyze, and focus on the opportunities that best fit your approach.
NVIDIA (NVDA)
Overview: NVIDIA is a data center scale AI infrastructure company whose Compute & Networking platforms and software power large scale AI workloads worldwide.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with most sales from US$214.9b in United States customers.
Market Cap: US$4,385.1b
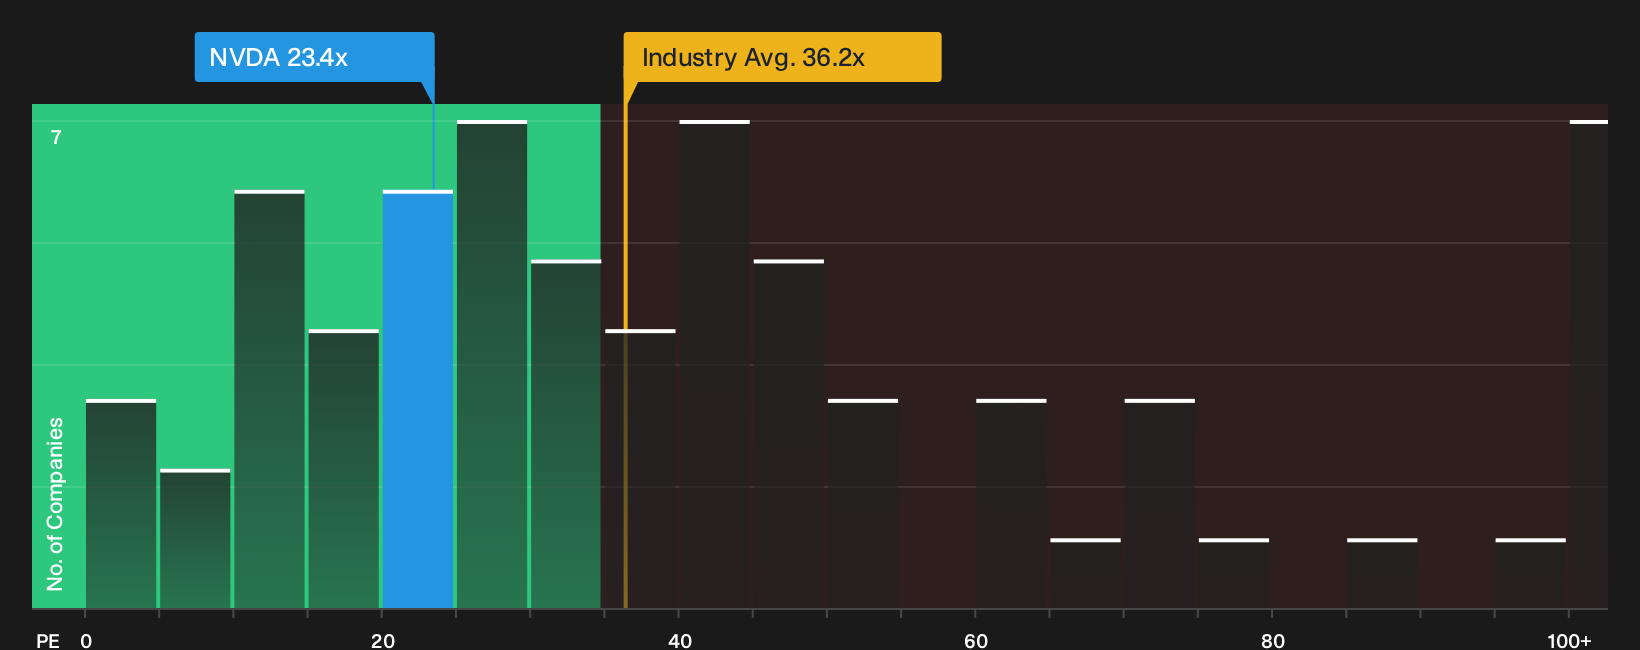
NVIDIA matters for this high quality undervalued screen because its AI focused Compute & Networking engine ties strong cash generation to the potential for a sharp re-rating if investors reassess how durable that advantage is.
"Uptake of an open-source/cheaper/better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
For investors, the real swing factor is what happens if one quiet shift in AI buying behavior starts to squeeze those premium economics.
If that shift is what matters to you, read the full narrative for NVIDIA to see how NVIDIA's moat, pricing power, and cash engine could evolve next.
Microsoft (MSFT)
Overview: Microsoft is a global software and cloud provider. Its Azure and AI driven Intelligent Cloud segment generates large, recurring cash flows within a broader technology portfolio.
Operations: Microsoft produces about US$180.2b from United States customers and US$166.3b from other countries, reflecting a broadly diversified global revenue base.
Market Cap: US$4,000.0b
Microsoft matters for this high quality undervalued theme because the Intelligent Cloud and Azure AI engine converts heavy data center spending into long term, usage based cash flow streams that can re rate if investors regain confidence in the payoff.
"Microsoft's CFO told analysts that capital expenditures will decrease sequentially in the next quarter, and before you get excited, it's not because demand is weakening. It's because of "normal variability in the timing of delivery of finance leases."
What happens to margins and cash generation if one unseen pressure tied to that build out shifts faster than the market expects?
If that inflection risk is what you care about, read the full narrative for Microsoft to see how Microsoft’s cloud cash flows and AI spend could be decoupling.
Meta Platforms (META)
Overview: Meta Platforms runs the Facebook, Instagram, WhatsApp, Messenger and related apps. These generate advertising cash flows that support its emerging VR and AI projects.
Operations: Meta Platforms generates about US$239.4b from Family of Apps and US$2.2b from Reality Labs, with revenue spread across multiple international regions.
Market Cap: US$1,546.7b
Meta Platforms matters for a high quality undervalued theme because its Family of Apps cash engine funds ambitious AI and hardware initiatives without weakening the underlying attention driven advertising franchise.
"Reality Labs lost $19.19 billion in 2025. On $2.21 billion in revenue."
The key question for Meta is what happens to free cash flow if a single assumption about that heavy future AI spending changes.
If that single assumption is what you are weighing, read the full narrative for Meta Platforms to see how Meta Platforms’ cash engine and AI spend could be quietly realigning.

Seeking Fresh Alternatives Before They Fly
Market resets rarely wait. Fresh ideas gain momentum, slow movers get caught, and under the radar for now opportunities start dropping off the radar. Acting early can help investors evaluate new possibilities.
- Target income that may help carry a portfolio through choppy cycles by scanning a curated pool of income payers using the 8 dividend fortresses.
- Look for potential infrastructure leaders before they become widely followed by reviewing a focused group of power grid enablers in the 42 power grid technology and infrastructure stocks.
- Monitor the picks-and-shovels side of AI and data demand by zeroing in on essential enablers inside the 16 top copper producer stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com