


EN
Paychex (PAYX) Draws Fresh Jobs Focus, Is The Stock Fully Priced?
A hotter than expected U.S. jobs report has brought payroll and HR providers back into focus, and Paychex (PAYX) now sits at the crossroads of labor demand, AI efficiencies, and outsourcing growth expectations.
Over the past month, Paychex has seen a 15.3% 30 day share price return to US$117.06, even though the 90 day share price return is down 2.5%, while the 1 year total shareholder return of 9.2% points to moderate longer term momentum as investors weigh AI driven efficiency gains and a stronger labor backdrop against earlier caution.
Scan for other payroll and HR stocks that could benefit from similar labor and AI trends as Paychex by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) in this space.
After a sharp 30 day rebound and a mixed near term return profile, the real question for Paychex now is whether the current valuation still offers an appealing risk reward entry for new money or whether it mostly suits existing holders.
Most Popular Narrative: 2.7% Overvalued
On the most followed view of Paychex, the narrative fair value of $113.93 sits slightly below the last close at $117.06, so the stock screens as modestly rich rather than clearly mispriced.
Continued roll out of the WISE AI engine, which now supports over 2,000 agents and features and has already cut manual payroll processing by about 20% while preventing roughly 90% of top payroll errors in a large pilot, points to further potential efficiency gains that can support operating margin and earnings.
See why 55 investors see Paychex as 3% overvalued.
Result: Fair Value of $113.93 (OVERVALUED)
Still, the Paychex story can shift quickly if Paycor integration stalls or if softer Management Solutions trends persist and dilute the AI and PEO upside case.
Find out about the key risks to this Paychex narrative.
Another View: Paychex Through The Cash Flow Lens
The analyst narrative has Paychex looking 2.7% overvalued at $117.06 versus a fair value of $113.93, yet the SWS DCF model points in the opposite direction. On that cash flow view, PAYX is trading about 38.7% below an estimated future cash flow value of $191.06, which presents the same price as a potential opportunity rather than a stretch. Which lens do you trust more when the story splits like this?
Look into how the SWS DCF model arrives at its fair value.
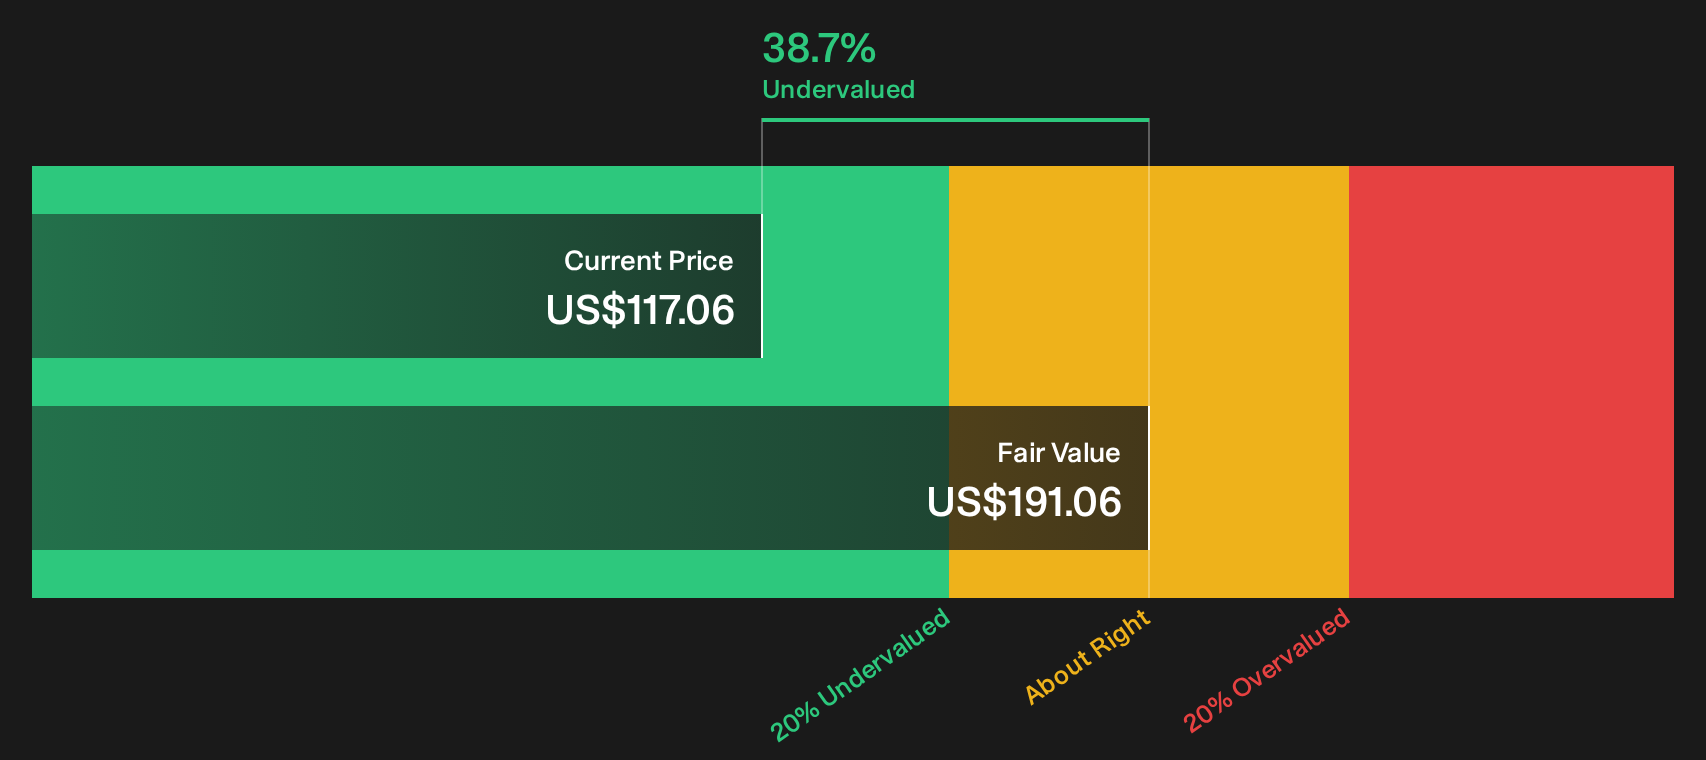
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paychex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split sentiment around Paychex leaves you on the fence, move quickly from reading to testing the numbers yourself and pressure testing the story with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paychex?
If Paychex has sharpened your thinking, do not stop with a single ticker when a wider universe of potential opportunities is just a few clicks away.
- Target resilient income streams by scanning for high yield payers in the 8 dividend fortresses and see which businesses might complement Paychex in a diversified portfolio.
- Hunt for quality at a discount by checking the 39 high quality undervalued stocks and compare how those candidates stack up against Paychex on valuation and fundamentals.
- Protect the downside first by focusing on durability through the 29 resilient stocks with low risk scores, so you are not relying on a single employer services stock to carry your returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com