


EN
How Updated Revenue Guidance Will Impact Noble (NE) Stock Investors
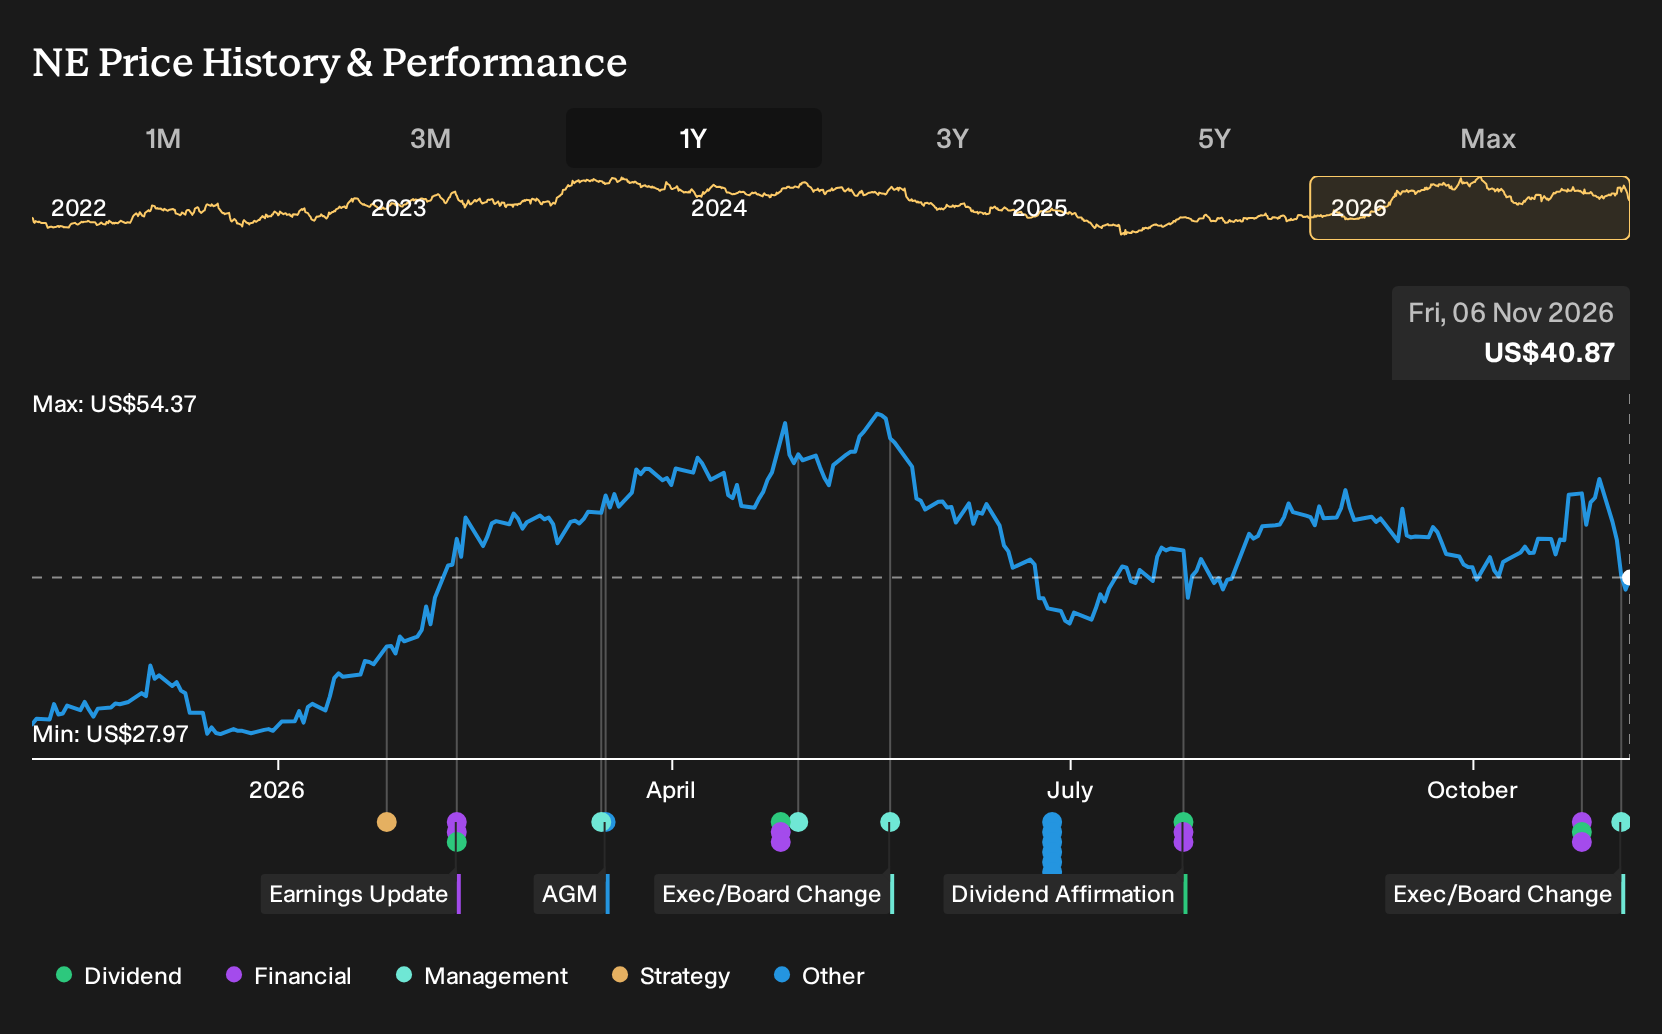
- Noble Corporation reported third quarter 2026 revenue of US$728.76 million and a net loss of US$117.02 million, narrowed full year revenue guidance to US$2.85b to US$2.9b, affirmed a US$0.50 fourth quarter dividend and, on November 1, 2026, promoted Joey M. Kawaja to Executive Vice President and Chief Operating Officer.
- The mix of weaker quarterly profitability, tighter revenue guidance and an unchanged dividend highlights how Noble is balancing current operational pressure with a commitment to capital returns and leadership continuity.
- We will look at how Noble's investment narrative is affected by weaker quarterly earnings alongside reaffirmed full year revenue guidance.
Scan how Noble's latest earnings pressure and dividend decision compare with peers by reviewing the hand picked 29 resilient stocks with low risk scores in the same space.
Noble Investment Narrative Recap
Noble continues to appeal to investors who support a long multiyear offshore drilling cycle and view its US$6.8b backlog as a potential source of steadier earnings and cash generation over time. The third quarter loss and softer nine month results keep execution in focus. The narrowed 2026 revenue range indicates that management sees some visibility, but near term profit quality remains the key swing factor.
The main near term catalyst is how efficiently Noble converts contracted work into margins while managing rig suspensions, impairments and the Brazil investigation. Weaker quarterly profitability does not change that core catalyst. It does, however, keep attention squarely on cost control, downtime management and the sustainability of the current dividend and capital allocation choices.
The reaffirmed US$0.50 fourth quarter dividend is the announcement most directly tied to this earnings update. On one hand, holding the payout steady signals confidence in future cash generation and in the backlog that is expected to support revenue into 2027. For income focused holders, that consistency can be appealing, particularly after a volatile quarter.
The risk considerations are clear. Noble is paying a dividend that current earnings and free cash flow do not fully cover, at a time when profit margins have already compressed compared with last year. For you as a shareholder, the question is whether operational execution and backlog conversion improve quickly enough to support both the payout and the substantial work still required on rigs, legal matters and balance sheet discipline.
Noble's current analyst narrative points to about US$3.6b in revenue and US$748.0 million in earnings by 2029, based on a 7.7% yearly revenue growth rate and an earnings increase of roughly US$598.4 million from US$149.6 million today.
Uncover why Noble's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Noble focuses on capital returns as the key risk. The most cautious analysts were already pencilling in about US$3.8b of 2029 revenue and US$783.0 million of earnings before this quarter, yet still saw the stock as overvalued. You can use those more pessimistic views to stress test your own expectations after the COO promotion and weaker quarter.
Explore 4 other Noble fair value estimates, including one that suggests as much as 30% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Noble research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Noble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Noble's overall financial health at a glance.
Looking For More Investment Ideas Beyond Noble?
If Noble's mix of earnings pressure, backlog support and dividend commitment has you rethinking portfolio balance, it can help to line it up against other opportunities with different risk and return profiles.
- If you want potential upside but still care about financial resilience, scan through the 19 high quality undiscovered gems that pair quality fundamentals with underfollowed stories.
- For investors who prize lower volatility and steadier balance sheets, compare Noble with a list of solid balance sheet and fundamentals (24 results) to see how its financial footing stacks up.
- Income focused readers can weigh Noble's payout against a 8 dividend fortresses that combine higher yields with robust coverage metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com