


EN
SpyGlass Pharma (SGP) Rally Builds, Is It Still 16% Below Fair Value?
SpyGlass Pharma (SGP) has attracted fresh attention after recent trading, with the share price last closing at US$36.95 and short term returns showing sharp moves over the past week and month.
The latest surge in SpyGlass Pharma's share price sits on top of a much stronger run that has been building for months, with a 1 day share price return of 8.41% and a 30 day share price return of 50.06% contributing to a 39.94% year to date share price gain.
Capture this momentum in context by checking how SpyGlass Pharma compares with other fast moving healthcare names in the 35 healthcare AI stocks.After a near 40% year to date gain and with no current revenue, SpyGlass Pharma now asks a simple question of buyers: Does the potential payoff still justify the risk at this price?
Most Popular Narrative: 16% Undervalued
With SpyGlass Pharma last closing at $36.95 against a narrative fair value of $44.00, attention shifts from the recent rally to whether its glaucoma platform can support that gap.
The plan to complete Phase III BIM‑IOL enrollment in 2027, deliver top line intraocular pressure data in Q4 2027 and file an NDA in 2028 sets up a defined path toward a potential 2029 U.S. launch. This timeline could begin to convert SpyGlass Pharma’s estimated US$13b cataract surgery glaucoma opportunity into revenue.
See why 1 investors see SpyGlass Pharma as 16% undervalued.
Result: Fair Value of $44 (UNDERVALUED)
Still, the whole SpyGlass Pharma narrative leans heavily on BIM IOL hitting Phase III milestones and on reimbursement holding up, while any extra equity raises could dilute that upside story fast.
Find out about the key risks to this SpyGlass Pharma narrative.
Another View: SpyGlass Pharma Through The P/B Lens
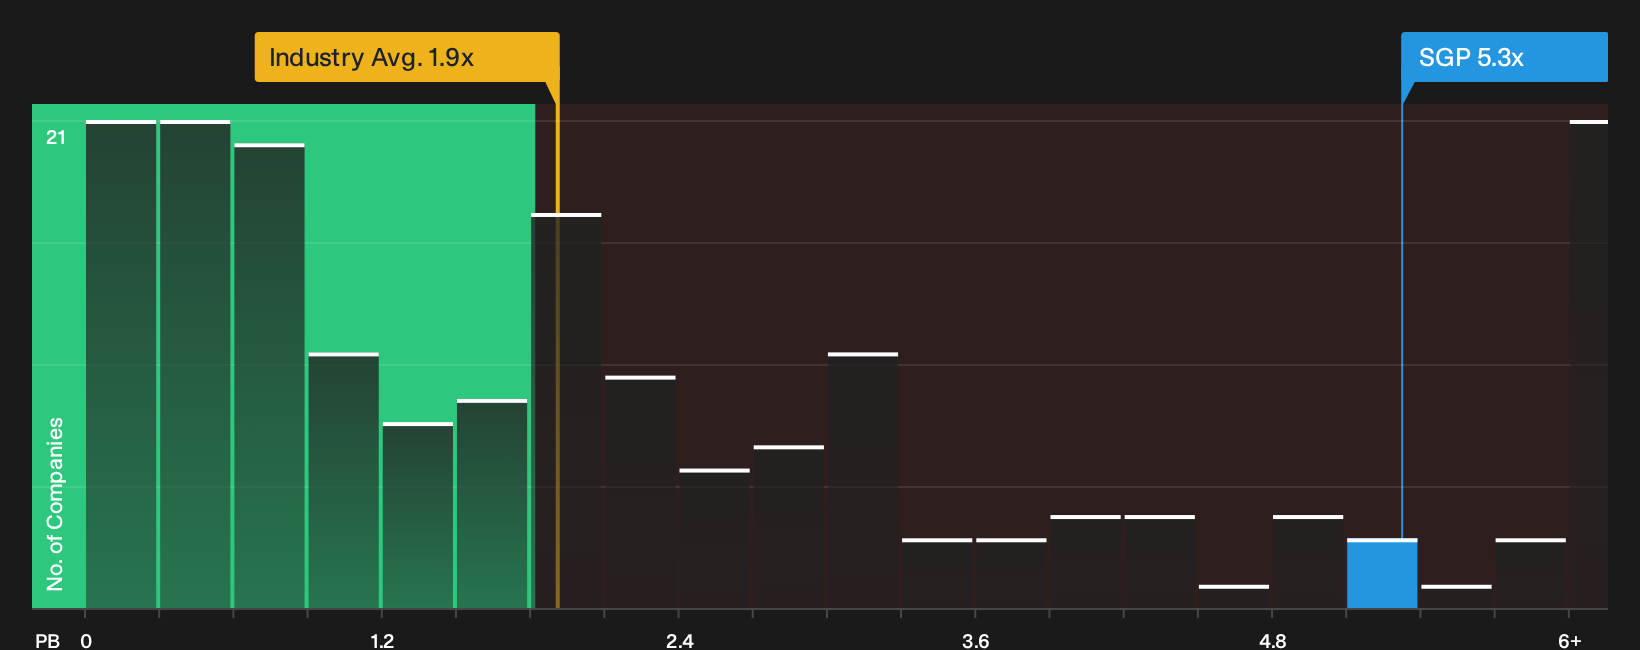
Analyst narratives frame SpyGlass Pharma as 16% undervalued at $36.95 versus a $44 fair value. The balance sheet tells a tougher story. The stock trades on a P/B of 5.3x, which is far richer than the US Pharmaceuticals average of 1.9x and still below a peer group closer to 19x.
That gap means you are already paying a premium to the broader sector for a pre revenue business, even if the price still looks cheaper than some direct comparables. The key issue is whether BIM IOL progress and cash runway justify that richer multiple or leave little room for disappointment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the recent optimism around SpyGlass Pharma matches your own risk tolerance and time horizon? Act quickly, review the numbers carefully, and weigh the trade off between potential upside and dilution risk in light of the 3 important warning signs.
Looking for more SpyGlass Pharma style investment ideas?
If SpyGlass Pharma has your attention, do not stop here. Broaden your watchlist with fresh ideas built from different strengths, risk profiles, and balance sheets.
- Target stronger balance sheets and sturdier fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) so your next idea rests on financial strength rather than hope.
- Hunt for mispriced opportunities by running through the 39 high quality undervalued stocks and see which companies the market might be overlooking right now.
- Stack potential income on top of growth by reviewing the 8 dividend fortresses and spot yields that could support your portfolio through different market conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com