


EN
Celsius Holdings (CELH) Could Be 32% Undervalued Following Strong Q3 Results
Celsius Holdings (CELH) just posted Q3 2026 results that put earnings and its multi-brand shift in the spotlight, combining higher sales, improved profitability, a new structure and fresh leadership appointments.
The latest earnings and restructuring news hit a stock that has been trying to rebuild confidence. Celsius Holdings shares closed at US$32.16, with a 1 day share price return of 7.06% and a 30 day share price return of 19.47%. However, the year to date share price return has fallen 32.65% and the 3 year total shareholder return is down 44.07%. Recent momentum is therefore improving off a weaker long term record as investors reassess growth hopes and execution risks around the multi brand plan.
Scan how Celsius Holdings compares to other fast-growing consumer stocks by reviewing our hand picked 19 high quality undiscovered gems in similar high-growth niches.
Bulls point to Celsius Holdings’ sharp profit swing, Alani Nu’s record quarter and the share buyback, while bears focus on the rich P/E and execution risks. Which story does the current valuation support?
Most Popular Narrative: 32% Undervalued
Celsius Holdings closed at $32.16, while the most followed narrative on the stock pegs fair value at roughly $47. That gap frames a bullish storyline that leans heavily on earnings momentum, brand strength and the Pepsi partnership as key drivers.
I believe Celsius Holdings stock can reach a price of $47.00 per share (+42%) over the next two months, with potential to reach $71.00 per share within the next few years. This will be driven by continued earnings and revenue gains, international expansion, and the long-term integration of Alani Nu and Rockstar, which were both recent acquisitions.
See why 12 investors see Celsius Holdings as 32% undervalued.
According to Bullish4YaMotha, this thesis leans on Celsius Holdings becoming a long term energy drink fixture for younger consumers, backed by Pepsi distribution and a broader brand portfolio across CELSIUS, Alani Nu and Rockstar. The narrative also highlights a sharp earnings ramp over the last year and argues that the market is still weighing short term legal questions and execution risk more heavily than the longer term cash generation potential implied by that $47 fair value.
Result: Fair Value of $47 (UNDERVALUED)
Still, the bullish Celsius Holdings pitch relies on a rich P/E and assumes that legal issues and Pepsi’s execution all break positively, which could prove overly optimistic.
Find out about the key risks to this Celsius Holdings narrative.
Another View: Celsius Holdings Through The Earnings Lens
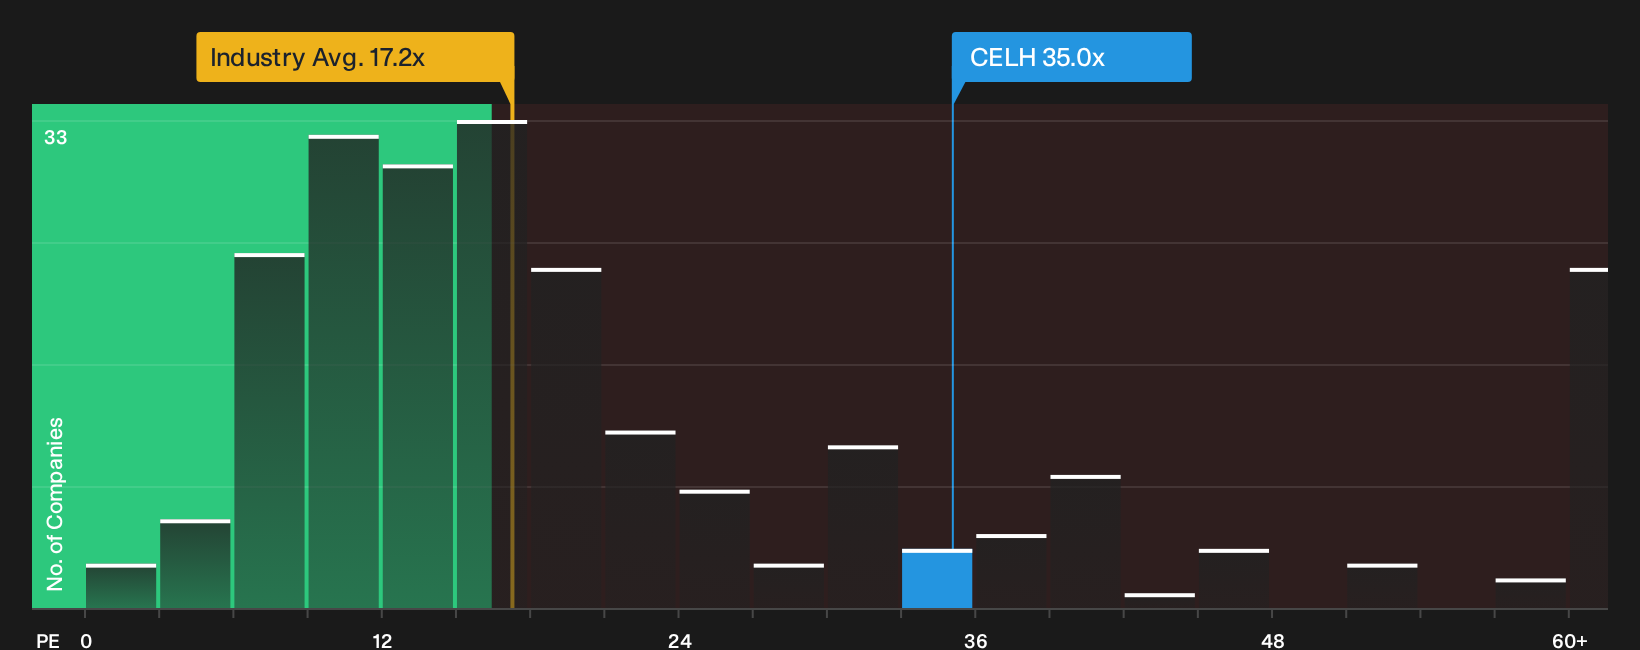
The fair value story shifts when you look at Celsius Holdings through earnings multiples instead of user narratives and cash flow estimates. The stock trades on a P/E of 35x, while the fair ratio sits at 23.5x and peers cluster around 28.6x and the global beverage group at 17.2x. That richer tag suggests valuation risk if growth or margins stumble, so investors may consider how much premium they are willing to pay for this energy drink play.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Celsius Holdings so far, with sharp recent gains sitting against a weaker multi year track record, mean the next move comes down to your own judgment. Act while sentiment is still resetting and weigh the trade off between execution risks and potential upside by reviewing the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Celsius Holdings?
If Celsius Holdings has your attention, do not stop here. Broaden your opportunity set by lining up a few more candidates that match your risk and return preferences.
- Target strong value potential and solid fundamentals by reviewing our hand picked 39 high quality undervalued stocks that may offer more attractive entry points than headline names.
- Strengthen your portfolio’s resilience by scanning the 29 resilient stocks with low risk scores that aim to keep volatility in check while you focus on long term compounding.
- Zero in on balance sheets that can handle shocks by assessing our curated list of solid balance sheet and fundamentals (24 results) before the crowd chases the next story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com