


EN
3 Data Center REIT Stocks Worth Watching As AI Infrastructure Fears Rise
Volatility has rushed back into global markets as investors question how far newly empowered Democrats might go in slowing AI data center build outs, just as Asian indices from the Kospi to the Nikkei 225 signal broader risk off sentiment. Sharp moves like these can punish anything linked to AI infrastructure and sometimes create mispriced opportunities. This article breaks down three data center related stocks exposed to the latest AI headlines and explains why their stories deserve a closer look at this time.
The three stocks covered below are just a starting sample, as the full screen surfaced 9 more listed data center and colocation operators with equally compelling narratives that are not profiled in this article. To go straight to the source, analyze the full peer set, and identify your own highest conviction plays, head into the Global Data-Center REITs and Colocation Operators screener.
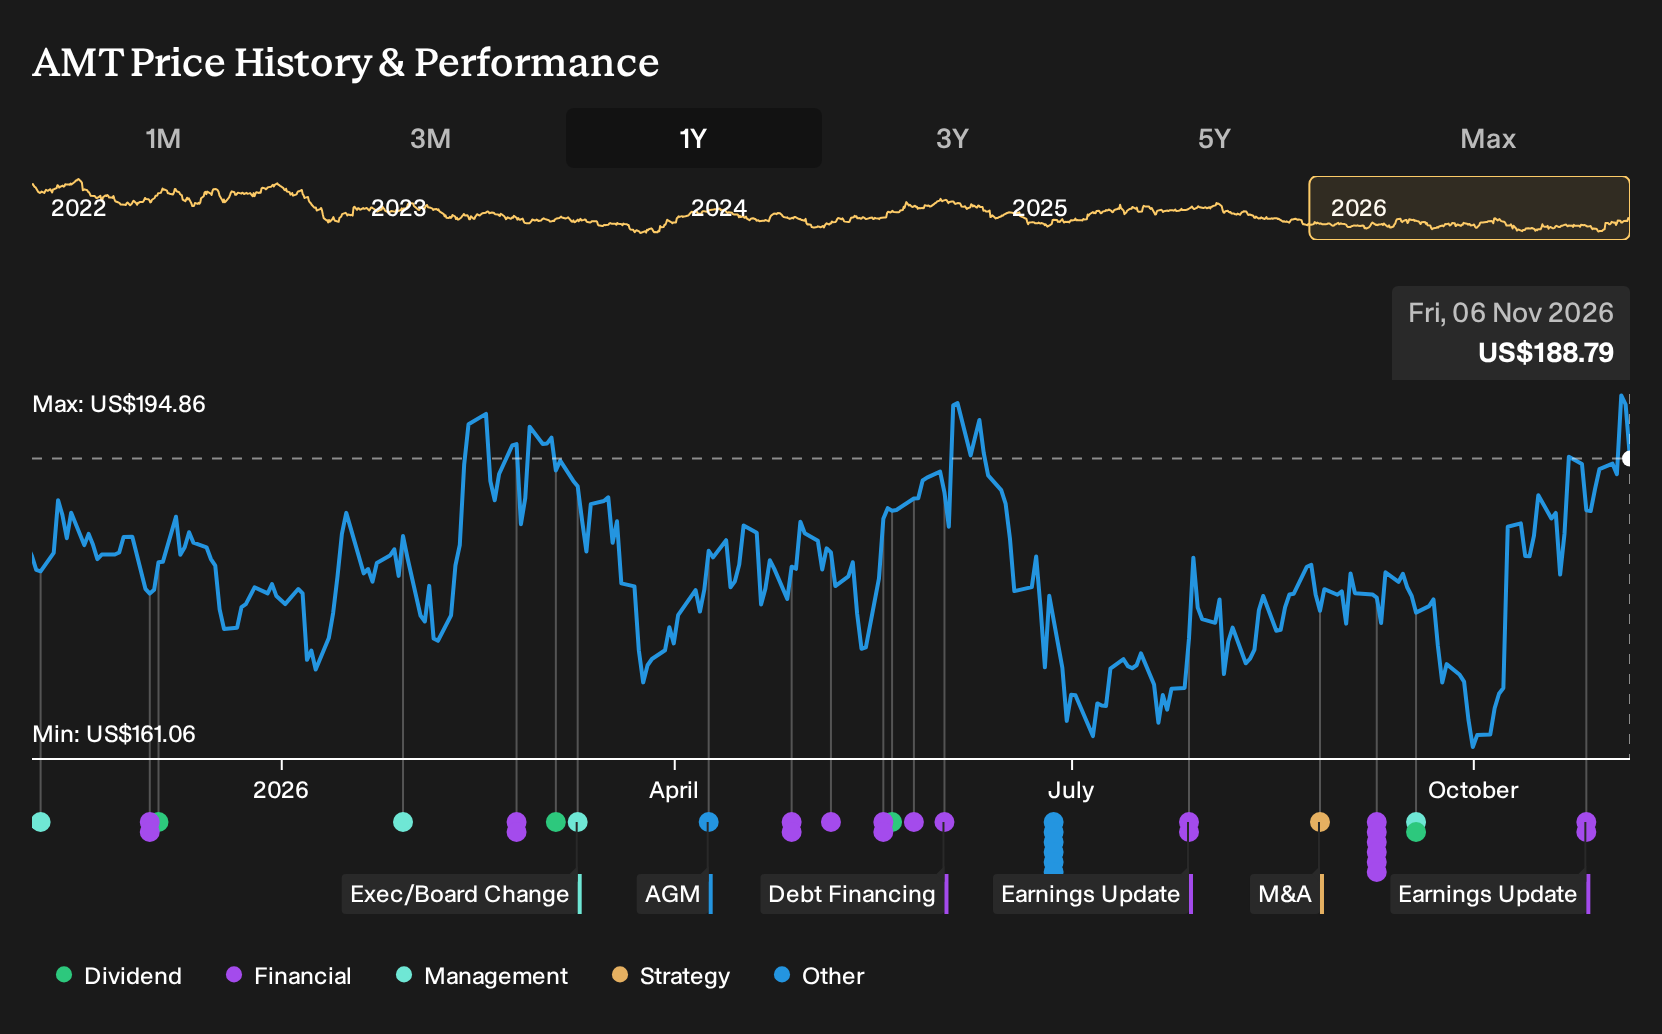
American Tower (AMT)
American Tower plugs into the data infrastructure theme from a different angle by renting communication towers and data center space that carry cloud and AI traffic rather than hosting the compute itself. This gives investors exposure to digital demand through long leases and diversified tenants.
American Tower runs more than 147,000 communication sites and a U.S. data center network, earning about US$5.1b from U.S. and Canada properties, US$1.8b from Latin America, US$1.6b from Africa and APAC, US$1b from Europe, US$1.2b from data centers and US$245m from services, with a market value near US$90b.
"Like the rest of the sector, AMT has been hit by higher interest rates in recent weeks. REITs fund growth with debt, so higher rates weigh on refinancing costs and on how investors value their cash flows."
What really matters now is how one quiet shift in digital traffic demand filters through pricing power and future cash generation for American Tower.
That shift in demand sits at the core of the full narrative for American Tower, where American Tower’s tower scale, data center footprint and rate sensitivity are pulling in different directions.
Mapletree Industrial Trust (SGX:ME8U)
Mapletree Industrial Trust gives you more direct exposure to the screener’s data centre theme, pairing a global server-focused footprint with traditional industrial assets, and the next quote goes to the crux of how its portfolio reshuffle could shape that income story.
"Although Mapletree Industrial Trust has executed sizeable divestments and improved leverage, the plan to recycle a further S$500 to S$600 million of assets into new data centre exposure could crystallise the S$230 million of recent portfolio revaluation losses if buyers demand discounts on weaker US properties. This would constrain future earnings growth and reduce flexibility to support distributions."
What happens if a single pressure point in that capital recycling plan shifts the balance between reliable payouts and future growth will be critical.
Mapletree Industrial Trust is a Singapore listed REIT focused on income producing industrial properties and global data centres, generating about S$219.9 million from North American data centres, S$48.4 million from Asian data centres, S$229.9 million from Singapore general industrial buildings and S$156.6 million from hi tech and business space, with a market value near S$5.0b.
That trade off between today’s distributions and tomorrow’s data centre mix is exactly what the full narrative for Mapletree Industrial Trust unpacks, including where capital recycling risk may be masking upside potential.

NTT DC REIT (SGX:NTDU)
NTT DC REIT is a pure play on the Global Data-Center REITs and Colocation Operators theme. It owns six carrier neutral Tier III equivalent facilities built for cloud and AI workloads. It earns about US$155 million from commercial data center leases and has a roughly US$946 million market value.
NTT DC REIT gives you direct exposure to global data-center real estate at a time when investors are questioning how durable AI infrastructure demand really is. The trust offers focused data-center income and potential growth. However, what happens when that income stream meets a debt heavy funding model will matter a lot for future returns.
That funding question is exactly where the 4 key rewards and 2 important warning signs (2 are major!) picks up, separating durable NTT DC REIT cash flow from balance sheet pressure hiding in the fine print.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum hits and prices start flying, the easier entry points tend to be crowded. Scan these under-the-radar lists while it matters and consider potential opportunities early.
- Target dependable income streams by reviewing the 8 dividend fortresses that currently combine strong payouts with balance sheets built to handle tougher conditions.
- Track the next potential breakout trend by scanning 52 AI infrastructure stocks positioned to benefit as demand shifts toward the picks and shovels behind AI.
- Position ahead of money moving into automation by assessing 90 robotics and automation stocks where real businesses are already turning robotics and software into cash flow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com