


EN
Is OPKO Health (OPK) Too Expensive After Its Recent Sales Shift?
OPKO Health has delivered a sharp mix of outcomes for shareholders, with a long stretch of value erosion followed by a recent rebound. That raises a simple question for you as an investor: Does the current US$1.73 share price make sense when judged purely against the sales the business is generating today and expected to produce from here?
- The stock is down 58.0% over 5 years, which puts the focus on whether the recent recovery really lines up with the underlying sales base.
- Recent transaction activity around its diagnostics operations and financing tied to drug development may support different expectations for future revenue mix and timing, which directly feeds into how much investors are willing to pay per dollar of sales.
- Your read on OPKO Health is one view; the desks covering it have another. See what analysts think OPKO Health's shares could be worth.
The stock's next move may depend on whether OPKO Health's current market value is well supported by its sales.
If you want a broader starting point while you weigh OPKO Health against its sales, you can apply the same approach to a wider group using 39 high quality undervalued stocks.
Does OPKO Health Look Pricey on Sales?
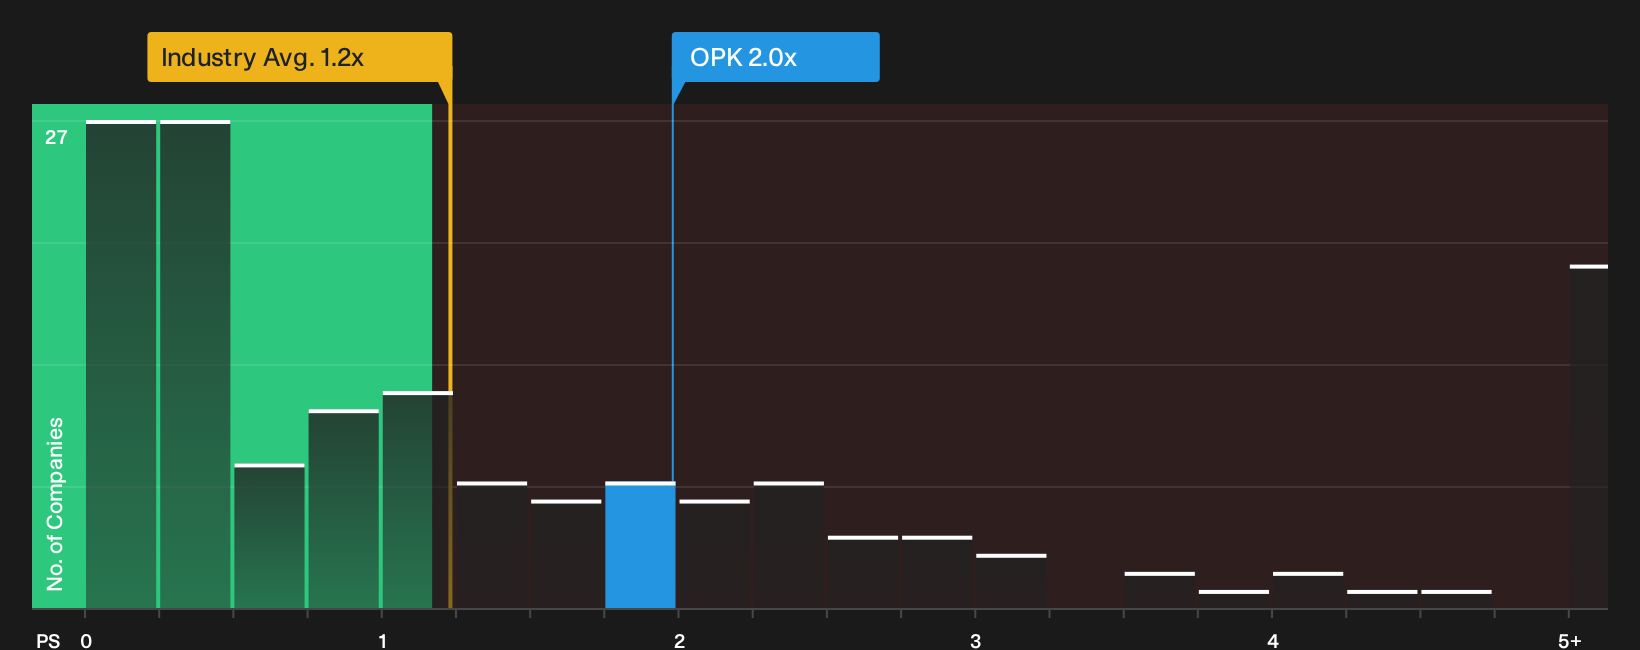
The P/S ratio suits OPKO Health because investors are currently putting more weight on its revenue base than on near term profits or cash flow. On this yardstick, the stock trades at about 2.0x trailing sales, compared with a Healthcare industry average of roughly 1.2x and a peer group closer to 0.8x. That means the market is paying a noticeably higher price for each dollar of OPKO Health revenue than for many sector alternatives.
Because the Fair Ratio model adjusts for the company’s growth profile, margins, size and risk, it points to a lower multiple than the one attached to the shares today and it does so by a wide margin. The gap suggests the framework is heavily penalising OPKO Health for its recent losses and the quality and timing of expected revenue, so the current 2.0x screens as expensive on this measure rather than landing near a finely tuned fair value. Despite the Q3 2026 earnings beat and the agreed US$722m sale of most BioReference operations to Labcorp, the stock still prices in a rich P/S versus what this model implies. Explore the numbers behind OPKO Health's P/S valuation.
The OPKO Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for OPKO Health pick up where the valuation puzzle leaves off by spelling out which paths for revenue growth, margins and earnings would make the shares look meaningfully higher or lower than they do today on the Community page. Instead of just giving you a single ratio from a model, they map the future that number relies on so you can see, over time, whether OPKO Health's actual progress fits the story that price implies.
One of the top community narratives on OPKO Health: 58% undervalued
"The sale of OPKO Health's remaining BioReference clinical diagnostics, women's health, urology, corrections testing businesses and over 80 patient service centers to Labcorp..."
Discover why this Narrative puts OPKO Health at 58% undervalued.
OPKO Health's valuation still leaves one key issue unanswered
Price is only one piece of the puzzle for OPKO Health, since Simply Wall St's checks also highlight specific business risks that could reshape how you view the stock's appeal. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com