


EN
DraftKings (DKNG) Missed Third Quarter Expectations, Is The Stock 12% Undervalued?
DraftKings (DKNG) triggered a sharp market reaction after third quarter results missed analyst expectations and the business cut its 2026 revenue and EBITDA outlook, largely due to heavier spending on its Predictions platform and related regulatory uncertainty.
The latest move has punctuated a rough stretch for DraftKings. The 1-day share price return declined 21.3%, adding to a 7-day share price return down 11.48% and a year-to-date share price return down 48.09% as investors reassess the balance between Predictions driven upside and higher execution risk. In total shareholder terms, the stock is down 39.11% over one year and 54.31% over five years, which signals fading momentum despite earlier enthusiasm around online betting and new products.
Spot fresh setups beyond DraftKings by scanning a curated group of 39 high quality undervalued stocks that combine balance sheet strength with cash flow support.The share price reset now leaves DraftKings trading far below both analyst targets and some intrinsic value estimates. Is the market overreacting to Predictions risk, or simply pulling fair value closer to the new guidance range?
Most Popular Narrative: 12% Undervalued
DraftKings is trading at $18.51 against a widely followed fair value marker of $20.97. This frames the recent pullback as a steep discount rather than a minor dip. That gap only matters if the underlying story on growth, regulation, and Predictions driven spending holds up.
The legalization of online sports betting created one of the fastest-growing industries in consumer discretionary. DraftKings emerged as one of its biggest winners, rapidly expanding their customer base as more states embraced regulated wagering.
See why 8 investors see DraftKings as 12% undervalued.
Result: Fair Value of $20.97 (UNDERVALUED)
Still, several pressure points could break this DraftKings narrative, including rising state tax burdens and prediction market rivals pulling higher value bettors away from the platform.
Find out about the key risks to this DraftKings narrative.
Another View On DraftKings Valuation
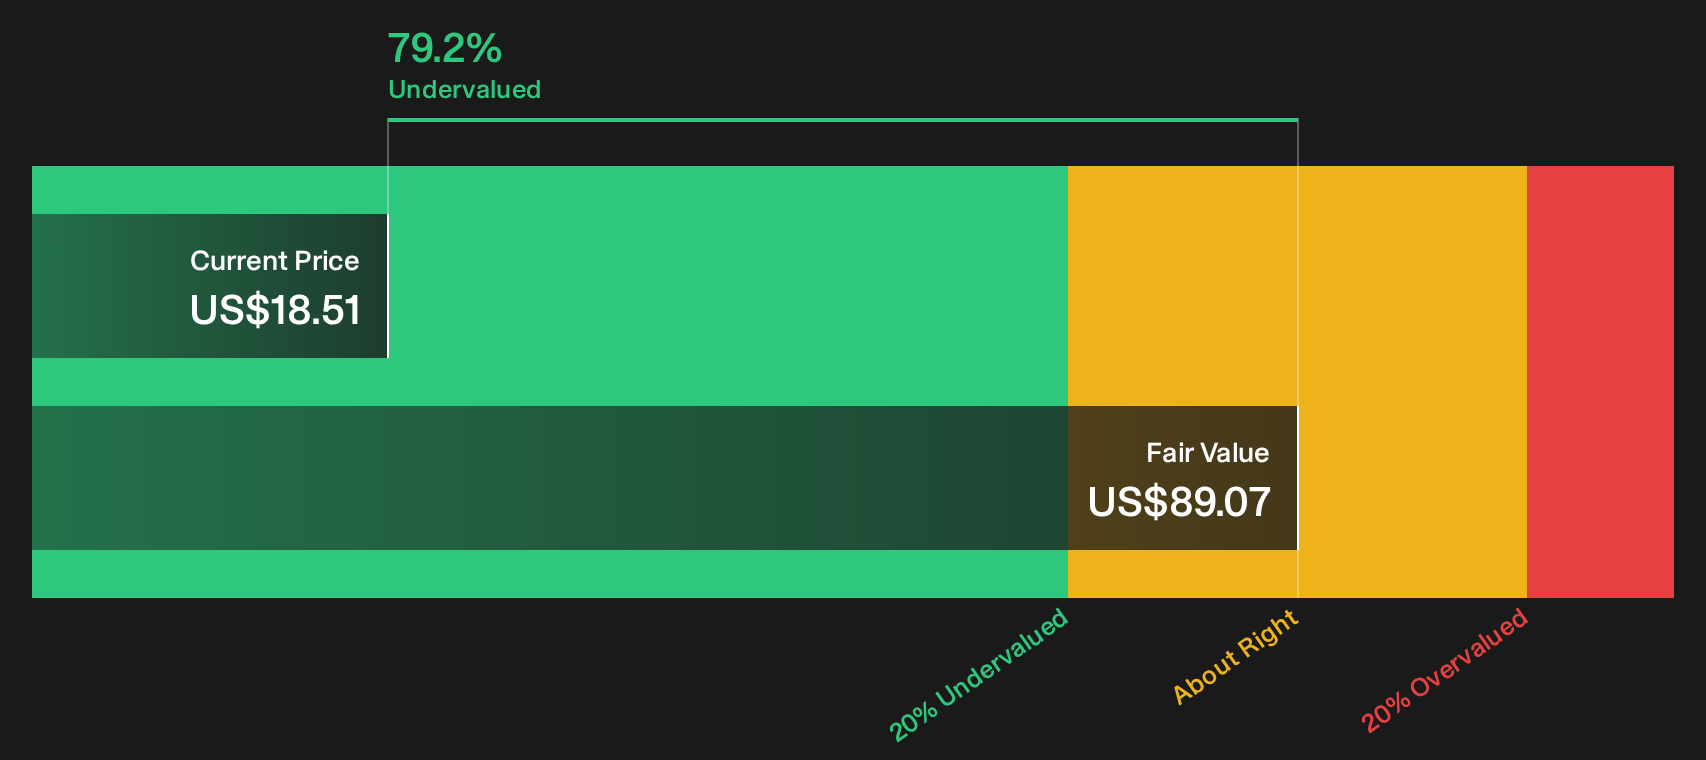
That 12% discount to a $20.97 fair value comes from narrative driven estimates, but the SWS DCF model points to a very different picture. On that approach, DraftKings at $18.51 is trading at a steep 79.2% discount to an $89.07 future cash flow value. Which story do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around DraftKings is unsettled, which is exactly when fresh data can help you separate short term noise from lasting opportunity. Act quickly, review the upside factors for yourself, and then test your own conclusion against the 2 key rewards.
Looking for more investment ideas beyond DraftKings?
If DraftKings has you rethinking your playbook, use this moment to widen your hunt for opportunities that better fit your risk, income, and balance sheet preferences.
Skip waiting for the next headline and build your own watchlist with the Simply Wall Street Screener. Fresh ideas are already there. Do not miss them.
- Target stability first and let potential upside follow with a 29 resilient stocks with low risk scores that screens for businesses showing more resilient risk profiles than the broader market.
- Grow your income stream by focusing on a carefully filtered pool of companies described as 8 dividend fortresses that aim to combine yield with staying power.
- Hunt for tomorrow's leaders early by working through a 19 high quality undiscovered gems that highlights underfollowed stocks with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com